Aerospace Plastics Market
Aerospace Plastics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710891 | Published On : September 14, 2026 |
Format : 


 | Author : Ashraf Shehata
Aerospace Plastics Market Size
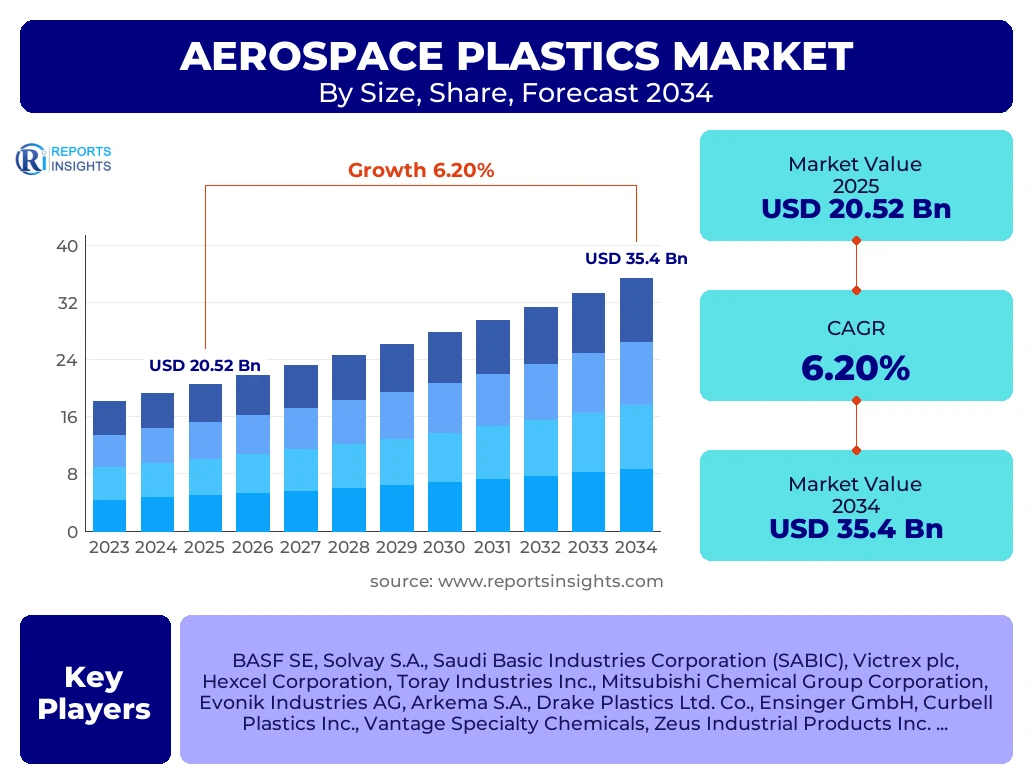
According to Reports Insights Consulting Pvt Ltd, The Aerospace Plastics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2026 and 2034. The market is estimated at USD 21.8 Billion in 2026 and is projected to reach USD 35.4 Billion by the end of the forecast period in 2034.
Key Aerospace Plastics Market Trends & Insights
The global aerospace plastics sector is undergoing a transformative shift driven by the relentless pursuit of fuel efficiency and the integration of advanced manufacturing technologies. Market intelligence indicates a significant pivot toward high-performance thermoplastics such as Polyetheretherketone (PEEK) and Polyphenylene Sulfide (PPS) due to their exceptional strength-to-weight ratios and thermal stability. Stakeholders are increasingly focusing on the decarbonization of the aviation industry, which mandates the replacement of traditional heavier metallic components with lightweight polymer alternatives. Furthermore, the rise of Urban Air Mobility (UAM) and the expansion of commercial space exploration are creating new frontiers for specialized plastic applications that can withstand extreme environmental conditions.
- Largest Region: North America remains the dominant regional market, underpinned by a robust aerospace manufacturing ecosystem and the presence of major aircraft original equipment manufacturers (OEMs).
- Fastest Growing Region: Asia-Pacific is identified as the fastest-growing market, fueled by increasing air passenger traffic in emerging economies and substantial investments in indigenous aircraft production programs.
- Leading Material Segment: High-performance Engineering Plastics, particularly PEEK and Polyetherimide (PEI), hold the largest market share due to their widespread use in engine components and structural interior parts.
- Dominant Application: Aircraft Interiors represent the primary application segment, driven by constant cabin retrofitting and the demand for lightweight seating, partitions, and overhead bins.
Key Takeaways Aerospace Plastics Market Size & Forecast
The aerospace plastics market forecast reflects a stable upward trajectory, closely aligned with the recovery of the global tourism sector and the modernization of military aircraft fleets. Analysts emphasize that the transition from traditional thermosets to recyclable thermoplastics is a critical takeaway, as it addresses both manufacturing throughput and environmental sustainability goals. The integration of 3D printing or additive manufacturing is also identified as a core growth lever, allowing for the production of complex, consolidated plastic parts that were previously impossible to manufacture via traditional injection molding. This shift is expected to reduce assembly times and secondary waste significantly over the forecast period.
- Strategic Weight Reduction: Every kilogram removed from an aircraft structure results in significant lifetime fuel savings, making plastic adoption a non-negotiable strategy for modern fleet operators.
- Sustainability Mandates: Regulatory pressure regarding aircraft emissions is accelerating the adoption of bio-based and recyclable aerospace-grade polymers.
- Supply Chain Resilience: Companies are diversifying their polymer sourcing to mitigate geopolitical risks and ensure the steady supply of specialized resins required for next-generation narrow-body aircraft.
- Regional Hub Expansion: The establishment of localized manufacturing hubs in India and Southeast Asia is projected to lower logistics costs for regional aircraft assembly lines.
Aerospace Plastics Market Drivers Analysis
The primary driver for the aerospace plastics market is the critical need for weight reduction to enhance fuel economy and reduce carbon footprints. As airlines face stricter environmental regulations and volatile fuel prices, the demand for lightweight materials that do not compromise structural integrity has surged. Additionally, the rapid development of the low-cost carrier (LCC) model globally necessitates aircraft that are efficient to operate and maintain, further pushing the adoption of corrosion-resistant plastics over traditional metals.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Demand for Fuel-Efficient Aircraft | +2.4% | Global | 2025-2034 |
| Growth in Urban Air Mobility (UAM) | +1.1% | United States, Germany | 2027-2034 |
| Expansion of Low-Cost Carriers (LCCs) | +1.5% | India, China, SE Asia | 2025-2030 |
| Advancements in Additive Manufacturing | +1.2% | North America, Europe | 2026-2034 |
Aerospace Plastics Market Restraints Analysis
Despite the growth prospects, the market faces significant restraints, most notably the high cost of raw materials. High-performance polymers required for aerospace applications are significantly more expensive than standard industrial plastics or aluminum. Furthermore, the stringent certification and safety standards imposed by aviation authorities (such as the FAA and EASA) result in long lead times for the approval of new materials, which can stifle immediate innovation and adoption in critical structural components.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Material and Processing Costs | -1.3% | Global | 2025-2034 |
| Stringent Regulatory Approval Processes | -0.9% | United States, European Union | Continuous |
| Recycling and End-of-Life Challenges | -0.5% | Europe | 2028-2034 |
Aerospace Plastics Market Opportunities Analysis
The emergence of bio-derived plastics and the increasing focus on the "Circular Economy" present substantial opportunities for market players. Developing resins that are both high-performing and compostable or easily recyclable could provide a competitive edge. Additionally, the modernization of aging military fleets and the increasing production of unmanned aerial vehicles (UAVs) for both defense and commercial logistics offer a massive untapped market for durable, lightweight plastic components that can operate in diverse climates.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-Based Aerospace Polymers | +1.8% | Europe, North America | 2026-2034 |
| Modernization of Military Aircraft | +1.4% | United States, Middle East, India | 2025-2032 |
| Rise of Commercial Space Tourism | +0.8% | United States (Private Sector) | 2028-2034 |
Aerospace Plastics Market Challenges Impact Analysis
One of the foremost challenges is the technical limitation of plastics in extreme high-temperature environments compared to specialized metal alloys. While polymers like PEEK offer high heat resistance, they still face boundaries in engine "hot zones." Additionally, the global supply chain volatility for precursor chemicals and the specialized nature of the machinery required for processing aerospace-grade plastics pose significant operational challenges for small and medium-sized enterprises (SMEs) in the sector.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Thermal Limitation in Propulsion Systems | -0.7% | Global | 2025-2034 |
| Supply Chain Instability for Precursor Resins | -1.1% | Asia-Pacific, Europe | 2025-2027 |
| Lack of Standardized Testing for 3D Printed Parts | -0.6% | Global | 2025-2029 |
Aerospace Plastics Market - Updated Report Scope
This report provides a comprehensive examination of the global aerospace plastics landscape, covering material science innovations, regional production trends, and the competitive dynamics of the supply chain. The scope encompasses detailed quantitative and qualitative analysis across various segments, including material types, aircraft platforms, and specific application areas, ensuring that stakeholders have a granular view of growth pockets and risk factors from 2025 through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 20.52 Billion |
| Market Forecast in 2034 | USD 35.4 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Solvay S.A., Saudi Basic Industries Corporation (SABIC), Victrex plc, Hexcel Corporation, Toray Industries Inc., Mitsubishi Chemical Group Corporation, Evonik Industries AG, Arkema S.A., Drake Plastics Ltd. Co., Ensinger GmbH, Curbell Plastics Inc., Vantage Specialty Chemicals, Zeus Industrial Products Inc., Quadrant AG (Mitsubishi Chemical), PolyOne Corporation (Avient), Saint-Gobain Performance Plastics |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the aerospace plastics market reveals a diverse ecosystem where material properties are strictly matched to operational demands. Thermoplastics are currently outperforming thermosets in growth due to their ability to be reshaped and recycled, which is pivotal for modern high-volume aircraft production. Interior applications remain the largest segment by volume, whereas structural and engine components are the highest-value segments due to the specialized nature of the high-heat and high-stress resins required.
- By Material Type: Focus on Engineering Plastics (PEEK, PPS, PEI), Commodity Plastics (ABS, Polycarbonate), and Specialty Thermosets.
- By Aircraft Platform: Detailed analysis of Commercial, Military, Business Jets, and the emerging Space/UAV sectors.
- By End-Use Application: Cabin interiors, cockpit instruments, external fairings, engine components, and electrical insulation.
- By Manufacturing Process: Injection Molding, Thermoforming, CNC Machining, and 3D Printing/Additive Manufacturing.
Regional Highlights
- North America: Currently the largest market share holder, driven by the presence of Boeing and a massive network of Tier 1 and Tier 2 suppliers. The region leads in R&D spending for advanced composite and plastic integration.
- Asia-Pacific: The fastest-growing region with a high CAGR. China's COMAC and India's growing aerospace manufacturing initiatives are creating a surge in demand for aerospace-grade polymers.
- Europe: A center for innovation in sustainable and recyclable aerospace plastics, supported by the Clean Sky initiatives and the presence of Airbus. Germany and France are the key contributors.
- Middle East: Increasing significance as a global aviation hub, leading to high demand for cabin interior plastics for fleet modernization and maintenance, repair, and overhaul (MRO) activities.
- Latin America & MEA: Developing markets with growth centered around regional aircraft manufacturing (e.g., Embraer in Brazil) and increasing defense expenditure.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Aerospace Plastics Market.- BASF SE
- Solvay S.A.
- Saudi Basic Industries Corporation (SABIC)
- Victrex plc
- Hexcel Corporation
- Toray Industries Inc.
- Mitsubishi Chemical Group Corporation
- Evonik Industries AG
- Arkema S.A.
- Drake Plastics Ltd. Co.
- Ensinger GmbH
- Curbell Plastics Inc.
- Zeus Industrial Products Inc.
- Saint-Gobain Performance Plastics
- Avient Corporation
- Teijin Limited
- Kaman Corporation
- Premium AEROTEC
Frequently Asked Questions
What is the primary reason for the transition from metal to plastic in aerospace?
The primary driver is weight reduction. Replacing traditional aluminum and titanium with high-performance plastics can reduce the weight of specific components by up to 50%, leading to significant improvements in fuel efficiency and a reduction in carbon emissions.
Which plastic material is most commonly used for high-temperature aerospace applications?
Polyetheretherketone (PEEK) is the leading material for high-temperature applications due to its excellent thermal stability, chemical resistance, and mechanical strength, allowing it to perform reliably in engine compartments and demanding structural areas.
How is 3D printing impacting the aerospace plastics market?
Additive manufacturing or 3D printing allows for the creation of complex, lightweight geometries and consolidated parts that reduce the need for fasteners and assembly. This speeds up production, reduces waste, and enables rapid prototyping of specialized aircraft components.
What are the main regulatory hurdles for new aerospace plastics?
New materials must pass rigorous Fire, Smoke, and Toxicity (FST) tests, as well as structural integrity certifications by bodies like the FAA. These processes ensure passenger safety but can take years and require significant investment for new polymer formulations.
Which region is expected to see the most significant growth by 2034?
The Asia-Pacific region is expected to exhibit the highest CAGR through 2034, driven by a rapid increase in air travel demand, the expansion of regional aircraft manufacturing programs, and increasing government investment in the aerospace and defense sectors.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted