Driveline Market
Driveline Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711626 | Published On : November 10, 2026 |
Format : 


 | Author : Ashraf Shehata
Driveline Market Size
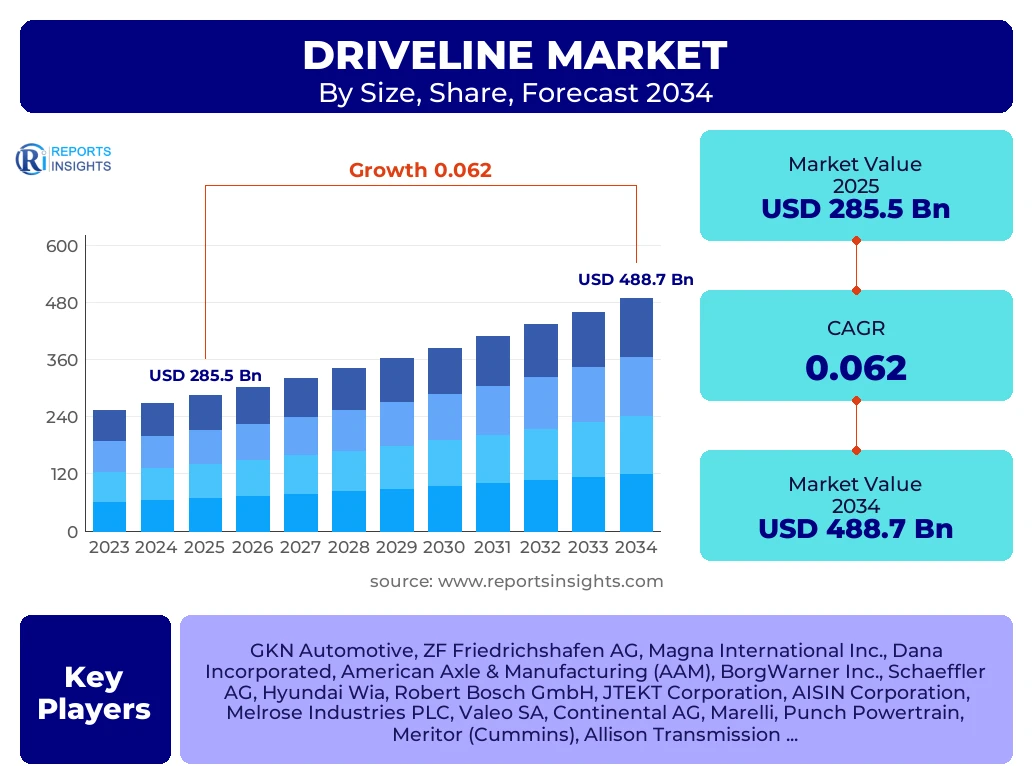
According to Reports Insights Consulting Pvt Ltd, The Driveline Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 303.2 Billion in 2026 and is projected to reach USD 488.7 Billion by the end of the forecast period in 2034.
Key Driveline Market Trends & Insights
The global driveline landscape is undergoing a radical transformation driven by the aggressive electrification of the automotive sector and the consumer shift toward Sport Utility Vehicles (SUVs) and Crossovers. As original equipment manufacturers (OEMs) pivot toward sustainable mobility, the demand for traditional internal combustion engine (ICE) driveline components is being supplemented—and in many cases replaced—by high-efficiency e-axles and integrated electric drive modules. Insights into regional dynamics indicate that the Asia-Pacific region remains the dominant powerhouse due to high production volumes in China and India, while North America and Europe are leading the charge in sophisticated All-Wheel Drive (AWD) and electric driveline innovations. Market benchmarking suggests that lightweighting and the reduction of frictional losses are no longer optional but are critical requirements to meet stringent global emission standards and extend the range of battery electric vehicles (BEVs).
- Largest Region: Asia-Pacific, driven by massive automotive production hubs in China, Japan, and India.
- Fastest-Growing Region: Asia-Pacific, due to rapid EV adoption and expanding middle-class demand for SUVs.
- Largest Segment by Share: Front-Wheel Drive (FWD) remains the volume leader, though AWD and Electric Drivelines are gaining significant market share.
- Integration Trend: The rise of 3-in-1 electric drive systems (motor, inverter, and gearbox) is streamlining driveline architectures.
- Material Innovation: Increased utilization of carbon fiber and high-strength alloys in driveshafts to reduce unsprung mass.
Key Takeaways Driveline Market Size & Forecast
The driveline market is characterized by a dual-track growth strategy where OEMs must optimize mature ICE architectures while simultaneously scaling modular electric drive platforms. Market forecasts indicate a steady upward trajectory, supported by the recovery of global vehicle production and the increasing complexity of drivetrain systems that command higher value per vehicle. Analysis of user inquiries suggests a high level of interest in the longevity of traditional transmission components versus the accelerated deployment of single-speed reduction gears in EVs. The forecast highlights a shift from mechanical complexity to mechatronic and software-defined torque management systems, which are becoming the new standard for vehicle dynamics and safety.
- Leading Country: China continues to lead in both production and consumption of advanced driveline systems, particularly for the NEV (New Energy Vehicle) sector.
- Value Growth: Higher CAGR in the electric driveline sub-segment compared to conventional mechanical drivelines.
- SUV Proliferation: The global surge in SUV sales is a primary catalyst for the growth of AWD and 4WD driveline configurations.
- Efficiency Mandates: Regulatory pressures in the EU and North America are forcing a move toward regenerative braking-compatible drivelines.
- Technological Convergence: The merging of power electronics with mechanical transmission components is creating new high-margin opportunities for Tier-1 suppliers.
Driveline Market Drivers Analysis
The global driveline market is primarily propelled by the necessity for enhanced vehicle efficiency and the escalating demand for premium driving experiences. As global emission regulations become more punitive, manufacturers are investing heavily in driveline architectures that minimize mechanical drag and optimize power delivery. Furthermore, the rise of the "Adventure" lifestyle has spurred a significant uptick in All-Wheel Drive (AWD) and Four-Wheel Drive (4WD) vehicle sales, necessitating more complex transfer cases and differential systems.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Electrification and EV Adoption | +2.8% | China, Germany, United States | 2025–2034 |
| Growing Demand for AWD and SUV Vehicles | +1.5% | North America, Middle East | 2025–2030 |
| Stringent Fuel Efficiency Regulations (CAFE/Euro 7) | +1.2% | European Union, Japan | 2025–2034 |
| Advancements in Lightweight Composite Materials | +0.7% | Global | 2027–2034 |
Driveline Market Restraints Analysis
Despite the growth, the driveline market faces significant headwinds, particularly concerning the high cost of transitioning manufacturing lines from ICE to EV components. The volatility of raw material prices, such as aluminum and specialized steel, continues to squeeze margins for component manufacturers. Additionally, the increasing complexity of electronic driveline controllers introduces new challenges in terms of cybersecurity and software reliability, which can hinder rapid market deployment.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High R&D and Transition Costs for E-Axles | -1.1% | Europe, North America | 2025–2028 |
| Raw Material Price Volatility (Steel/Aluminum) | -0.8% | Global | Ongoing |
| Complexity in Supply Chain for EV Electronics | -0.5% | Global | 2025–2027 |
Driveline Market Opportunities Analysis
The transition toward autonomous and software-defined vehicles presents a significant opportunity for the development of "Smart Drivelines" capable of predictive torque distribution based on sensor data. There is also a burgeoning aftermarket for driveline components in emerging economies where vehicle parc age is increasing. Furthermore, the development of multi-speed transmissions for high-performance electric vehicles represents a high-value niche market that is currently underserved.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Smart/Predictive Torque Vectoring | +1.4% | South Korea, Japan, Germany | 2028–2034 |
| Aftermarket Expansion in Emerging Markets | +0.9% | India, Brazil, Southeast Asia | 2025–2034 |
| Multi-speed Electric Drive Units for Luxury EVs | +0.6% | North America, EU | 2026–2034 |
Driveline Market Challenges Impact Analysis
One of the primary challenges facing the industry is the dual-system production requirement, where suppliers must maintain legacy ICE production while simultaneously investing in future-state EV technologies. This creates a capital allocation dilemma. Furthermore, the integration of complex electronic components into the driveline increases the risk of thermal management issues, particularly in high-performance or heavy-duty applications.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Thermal Management in High-Output E-Drivelines | -0.6% | Global | 2026–2030 |
| Managing Legacy ICE Asset Stranding | -0.9% | Western Europe, North America | 2025–2034 |
| Cybersecurity Threats in Connected Drivelines | -0.4% | Global | 2027–2034 |
Driveline Market - Updated Report Scope
This report provides a granular analysis of the global driveline market, covering technical architectures across passenger, commercial, and off-highway vehicles. It evaluates the shift from mechanical to electronic drive systems and offers detailed competitive benchmarking of Tier-1 suppliers and emerging technology providers. The scope encompasses the entire value chain from raw material sourcing to final assembly of e-axles and conventional transmissions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 285.5 Billion |
| Market Forecast in 2034 | USD 488.7 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | GKN Automotive, ZF Friedrichshafen AG, Magna International Inc., Dana Incorporated, American Axle & Manufacturing (AAM), BorgWarner Inc., Schaeffler AG, Hyundai Wia, Robert Bosch GmbH, JTEKT Corporation, AISIN Corporation, Melrose Industries PLC, Valeo SA, Continental AG, Marelli, Punch Powertrain, Meritor (Cummins), Allison Transmission, Showa Corporation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The driveline market is segmented based on vehicle architecture, propulsion type, and component categories to provide a holistic view of the technological shifts occurring within the industry. The transition from internal combustion engines to electric powertrains is the most significant segment-level trend, influencing everything from transmission design to final drive configurations. Passenger cars remain the largest vehicle segment, but the commercial vehicle segment is seeing rapid innovation in heavy-duty e-axles for long-haul applications.
- By Architecture:
- Front-Wheel Drive (FWD): The dominant segment for economy and mid-range passenger vehicles.
- Rear-Wheel Drive (RWD): Preferred for performance vehicles and heavy-duty trucks.
- All-Wheel Drive (AWD) & Four-Wheel Drive (4WD): Fast-growing due to the SUV boom and safety requirements.
- By Propulsion Type:
- Internal Combustion Engine (ICE): Steady demand in developing regions and heavy-duty transport.
- Hybrid Electric Vehicle (HEV/PHEV): A critical bridge technology requiring complex dual-power drivelines.
- Battery Electric Vehicle (BEV): The highest growth segment focusing on integrated electric drive units.
- By Component:
- Transmission: Including manual, automatic, CVT, and DCT architectures.
- Drive Shafts & CV Joints: Evolving with new materials for noise, vibration, and harshness (NVH) reduction.
- Differentials & Transfer Cases: Shifting toward electronic locking and torque-on-demand systems.
- E-Axles: High-value integrated units combining motor and transmission.
Regional Highlights
- Asia-Pacific: The largest market globally, accounting for over 45% of the total share. China leads in EV driveline production, while India shows massive growth in ICE-based commercial and passenger vehicle drivelines.
- North America: A major market for AWD and 4WD systems, driven by high consumer preference for full-size pickups and large SUVs. The region is also a pioneer in autonomous vehicle driveline integration.
- Europe: The epicenter of high-tech driveline engineering and stringent emission-led innovation. Leading the transition to premium electric drive modules and highly efficient hybrid transmissions.
- Latin America & MEA: Markets focused on durability and cost-effective driveline solutions for rugged terrains and heavy-duty commercial operations, with a slow but steady move toward hybridization.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Driveline Market.- GKN Automotive
- ZF Friedrichshafen AG
- Magna International Inc.
- Dana Incorporated
- American Axle & Manufacturing (AAM)
- BorgWarner Inc.
- Schaeffler AG
- Hyundai Wia
- Robert Bosch GmbH
- JTEKT Corporation
- AISIN Corporation
- Melrose Industries PLC
- Valeo SA
- Continental AG
- Marelli
- Punch Powertrain
- Allison Transmission
- Meritor (part of Cummins)
- Showa Corporation
- Sona Comstar
Frequently Asked Questions
What is the projected growth rate of the Driveline Market through 2034?
The Driveline Market is expected to grow at a CAGR of 6.2% from 2025 to 2034, reaching a total market valuation of approximately USD 488.7 Billion by the end of the forecast period.
Which region currently dominates the global driveline industry?
Asia-Pacific is the dominant region, holding the largest market share due to the high volume of vehicle production in China, Japan, and India, coupled with rapid electrification in the Chinese market.
How is the shift to electric vehicles (EVs) affecting the driveline market?
The shift to EVs is driving a move from complex multi-speed mechanical transmissions to integrated electric drive units or "e-axles," which combine the motor, inverter, and gearbox into a single, efficient package.
What are the key drivers for the All-Wheel Drive (AWD) segment?
The primary drivers include the global consumer preference for SUVs and Crossovers, as well as the safety benefits of electronic torque management and traction control in adverse weather conditions.
Who are the leading players in the driveline market?
Key industry leaders include GKN Automotive, ZF Friedrichshafen, Magna International, Dana Incorporated, and BorgWarner, all of whom are heavily investing in both traditional and electric drivetrain technologies.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
