Adtech Market
Adtech Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711052 | Published On : October 02, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Adtech Market Size
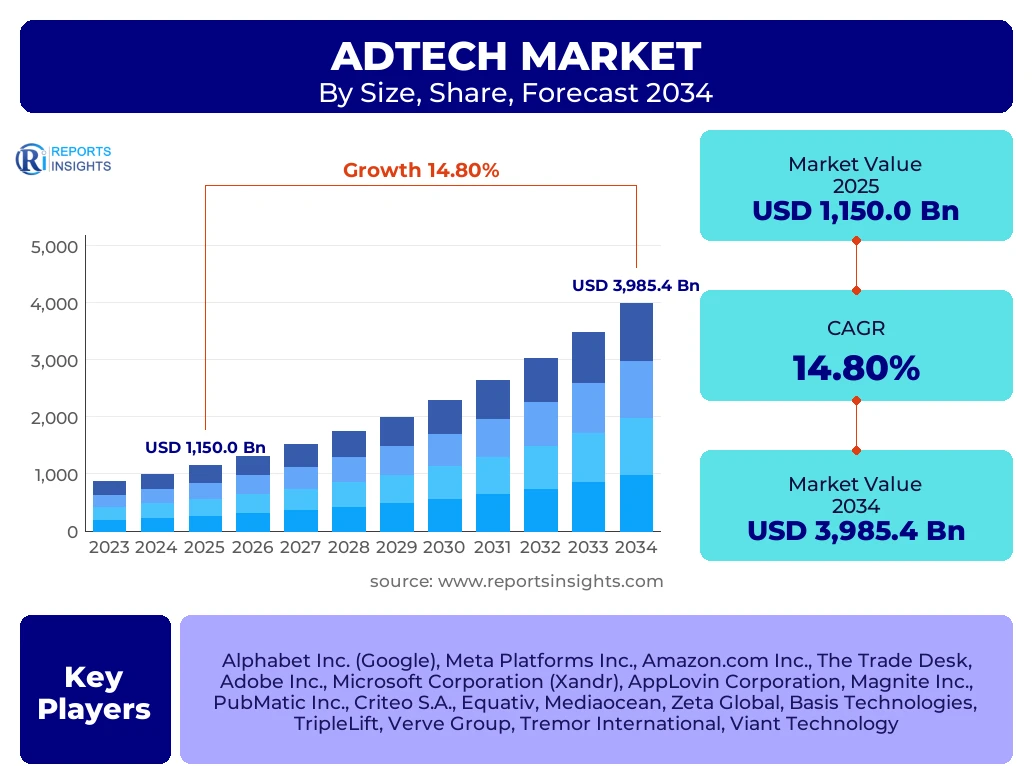
According to Reports Insights Consulting Pvt Ltd, The Adtech Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 14.8% between 2026 and 2034. The market is estimated at USD 1,320.2 Billion in 2026 and is projected to reach USD 3,985.4 Billion by the end of the forecast period in 2034.
Key Adtech Market Trends & Insights
The Adtech market is undergoing a fundamental transformation driven by the integration of Artificial Intelligence (AI) and the shift toward privacy-centric advertising models. Users and stakeholders are increasingly focused on how the deprecation of third-party cookies is reshaping identity resolution and how Connected TV (CTV) is bridging the gap between traditional linear television and digital performance marketing. Our analysis indicates that the rise of Retail Media Networks (RMNs) is creating a new ecosystem where first-party data is the primary currency, allowing brands to reach consumers at the point of purchase with unprecedented precision. Furthermore, the automation of creative assets through Generative AI is significantly reducing the time-to-market for complex global campaigns, while programmatic bidding remains the core infrastructure supporting market scalability.
- North America remains the largest regional market, driven by the presence of major technology incumbents and early adoption of CTV and programmatic audio.
- The Asia-Pacific region is recognized as the fastest-growing market, fueled by massive mobile penetration and the rapid expansion of e-commerce ecosystems in China, India, and Southeast Asia.
- The Demand-Side Platform (DSP) segment holds the largest market share by solution, as advertisers prioritize centralized platforms to manage cross-channel programmatic buying.
- Mobile advertising continues to be the dominant platform segment, though CTV is exhibiting the highest growth rate within the forecast period.
Key Takeaways Adtech Market Size & Forecast
The global Adtech landscape is characterized by high levels of consolidation among major players and a burgeoning long-tail of specialized niche providers focusing on privacy and niche inventory. Strategic analysis reveals that the transition to First-Party Data strategies is no longer optional but a critical requirement for maintaining attribution accuracy. Market participants are heavily investing in Clean Room technologies to facilitate secure data collaboration without compromising consumer privacy. As the industry moves toward 2034, the convergence of Martech and Adtech will likely create unified customer intelligence platforms that provide a 360-degree view of the consumer journey across both paid and owned media channels.
- The United States is the leading country globally in terms of total Adtech spend, accounting for over 35% of the global market valuation.
- The Retail and E-commerce vertical is the primary driver of market volume, as brands shift budgets toward performance-based digital channels.
- Privacy-enhancing technologies (PETs) are becoming a mandatory component of the Adtech stack to comply with evolving global regulations like GDPR, CCPA, and DMA.
- Connected TV (CTV) is projected to disrupt traditional broadcast advertising, with programmatic TV buying expected to grow triple-fold by 2034.
Adtech Market Drivers Analysis
The expansion of the Adtech market is primarily propelled by the exponential growth of digital content consumption and the increasing demand for measurable Return on Ad Spend (ROAS). The proliferation of high-speed internet and smartphone adoption globally has created a massive inventory of digital touchpoints, necessitating automated systems to manage ad placements efficiently. Moreover, the integration of Machine Learning (ML) algorithms into bidding engines allows for real-time optimization, ensuring that the right message reaches the right user at the optimal time, thereby maximizing conversion rates for advertisers.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of Generative AI in Creative Automation | +4.2% | Global (High impact in North America) | 2025 - 2034 |
| Rapid Expansion of Retail Media Networks | +3.8% | North America, Europe, China | 2025 - 2030 |
| Shift from Linear TV to Programmatic CTV | +3.5% | Global | 2026 - 2034 |
Adtech Market Restraints Analysis
Despite the robust growth, the Adtech market faces significant headwinds from evolving privacy regulations and the technical limitations imposed by major platform owners. The deprecation of third-party cookies in major browsers has disrupted traditional tracking and attribution methods, forcing the industry to rethink identity resolution. Additionally, the rising prevalence of ad fraud, including bot traffic and domain spoofing, continues to drain advertising budgets and erode trust between publishers and advertisers, requiring substantial investment in verification and brand safety tools.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Data Privacy Regulations (GDPR/CCPA) | -2.5% | European Union, United States | 2025 - 2034 |
| Third-Party Cookie Deprecation & Tracking Limitations | -2.1% | Global | 2025 - 2027 |
| Increasing Incidences of Digital Ad Fraud | -1.8% | Global (Emerging Markets) | 2025 - 2034 |
Adtech Market Opportunities Analysis
The evolving landscape presents significant opportunities for innovation, particularly in the realm of cookieless identity solutions and contextual targeting. As traditional tracking fades, advertisers are looking for sophisticated contextual AI that can understand the nuance of content to place ads without relying on personal identifiers. Furthermore, the emergence of the Metaverse and Augmented Reality (AR) advertising offers a new frontier for immersive brand experiences. Emerging markets in the Middle East and Africa also present untapped potential as digital infrastructure improves and a young, tech-savvy population enters the workforce.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Universal Identity Solutions | +3.2% | Global | 2026 - 2032 |
| Expansion into Emerging Markets (India, MEA) | +2.9% | India, UAE, Saudi Arabia, Nigeria | 2027 - 2034 |
| Immersive AR/VR and Metaverse Advertising | +1.5% | Global (Early adopters in APAC/US) | 2028 - 2034 |
Adtech Market Challenges Impact Analysis
The primary challenge for the Adtech industry lies in the complexity of the supply chain and the resulting "tech tax" that reduces the actual working media spend for advertisers. Ensuring transparency across multiple intermediaries—from DSPs and exchanges to SSPs—remains a persistent struggle. Additionally, the technical challenge of cross-device attribution in a fragmented ecosystem where users switch between mobile apps, browsers, and smart TVs makes it difficult to maintain a consistent narrative and measure incremental lift accurately.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Complexity and Lack of Transparency | -1.5% | Global | 2025 - 2034 |
| Cross-Device Attribution Accuracy | -1.2% | Global | 2025 - 2030 |
Adtech Market - Updated Report Scope
This report provides a comprehensive analysis of the global Adtech ecosystem, covering the full spectrum of solutions from supply-side to demand-side platforms. It examines the technological shifts from traditional programmatic to AI-driven automated buying and explores the impact of privacy regulations on market dynamics. The scope includes a detailed breakdown of regional growth patterns, industry-specific adoption rates, and a competitive landscape analysis of the leading technology providers shaping the future of digital advertising.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1,150.0 Billion |
| Market Forecast in 2034 | USD 3,985.4 Billion |
| Growth Rate | 14.8% CAGR |
| Number of Pages | 274 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Alphabet Inc. (Google), Meta Platforms Inc., Amazon.com Inc., The Trade Desk, Adobe Inc., Microsoft Corporation (Xandr), AppLovin Corporation, Magnite Inc., PubMatic Inc., Criteo S.A., Equativ, Mediaocean, Zeta Global, Basis Technologies, TripleLift, Verve Group, Tremor International, Viant Technology |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Adtech market is segmented by solution, platform, advertising type, and end-user vertical, reflecting the diverse ways technology is applied to digital advertising. The Solution segment is currently dominated by Demand-Side Platforms (DSPs) as brands seek more control over their media buying. However, the Supply-Side Platform (SSP) segment is evolving rapidly as publishers seek to maximize yield through header bidding and direct-to-consumer relationships. In terms of platforms, mobile remains the core engine of growth, but CTV is emerging as the most significant strategic priority for large-scale brand advertisers.
- By Solution: Demand-Side Platforms (DSP), Supply-Side Platforms (SSP), Ad Exchanges, Ad Networks, Data Management Platforms (DMP), Ad Servers.
- By Platform: Mobile, Desktop, Connected TV (CTV), Digital Out-of-Home (DOOH), Programmatic Audio.
- By Advertising Type: Programmatic, Search, Social Media, Display, Video, Native, Email.
- By Enterprise Size: Large Enterprises, Small and Medium Enterprises (SMEs).
- By Vertical: Retail & E-commerce, BFSI (Banking, Financial Services, and Insurance), Media & Entertainment, Healthcare, Travel & Hospitality, IT & Telecom, Automotive.
Regional Highlights
- North America: Currently the largest market due to high digital ad spending, early adoption of CTV, and the headquarters of major Adtech giants like Google, Meta, and The Trade Desk.
- Asia-Pacific: The fastest-growing region, driven by mobile-first economies like India and Southeast Asia, and the massive e-commerce and social media ecosystems in China.
- Europe: A mature market characterized by strict regulatory compliance (GDPR) which has led to high innovation in privacy-first and contextual advertising solutions.
- Latin America: Experiencing steady growth as digital transformation accelerates in Brazil and Mexico, with increasing programmatic adoption.
- Middle East and Africa: An emerging frontier with high potential for growth in mobile video and social media advertising as digital infrastructure expands.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Adtech Market.- Alphabet Inc. (Google)
- Meta Platforms Inc.
- Amazon.com Inc. (Amazon Advertising)
- The Trade Desk Inc.
- Adobe Inc.
- Microsoft Corporation (Xandr)
- AppLovin Corporation
- Magnite Inc.
- PubMatic Inc.
- Criteo S.A.
- Equativ
- Mediaocean LLC
- Zeta Global
- Basis Technologies
- TripleLift
- Verve Group
- Tremor International (Nexxen)
- Viant Technology Inc.
- Moloco Inc.
- Taboola
Frequently Asked Questions
What is the current size of the global Adtech market?
The Adtech market is estimated to be valued at USD 1,150.0 Billion in 2025 and is projected to grow significantly to nearly USD 4 Trillion by 2034.
How is AI impacting the Adtech industry?
AI is revolutionizing the industry by automating creative production, enhancing predictive bidding algorithms, and enabling more accurate audience modeling in the absence of third-party cookies.
Why is Connected TV (CTV) considered a major growth driver?
CTV offers the "lean-back" experience of traditional TV combined with the precision targeting and measurement capabilities of digital media, making it highly attractive for both brand and performance advertisers.
How will the deprecation of third-party cookies affect the market?
It is forcing a shift toward first-party data strategies, contextual targeting, and the development of new identity resolution frameworks like Unified ID 2.0 and Google's Privacy Sandbox.
Which region is expected to grow the fastest during the forecast period?
Asia-Pacific (APAC) is expected to be the fastest-growing region due to rapid digitalization, increasing smartphone penetration, and the expansion of digital-native retail platforms.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted