Adipic Acid Market
Adipic Acid Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710868 | Published On : September 12, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Adipic Acid Market Size
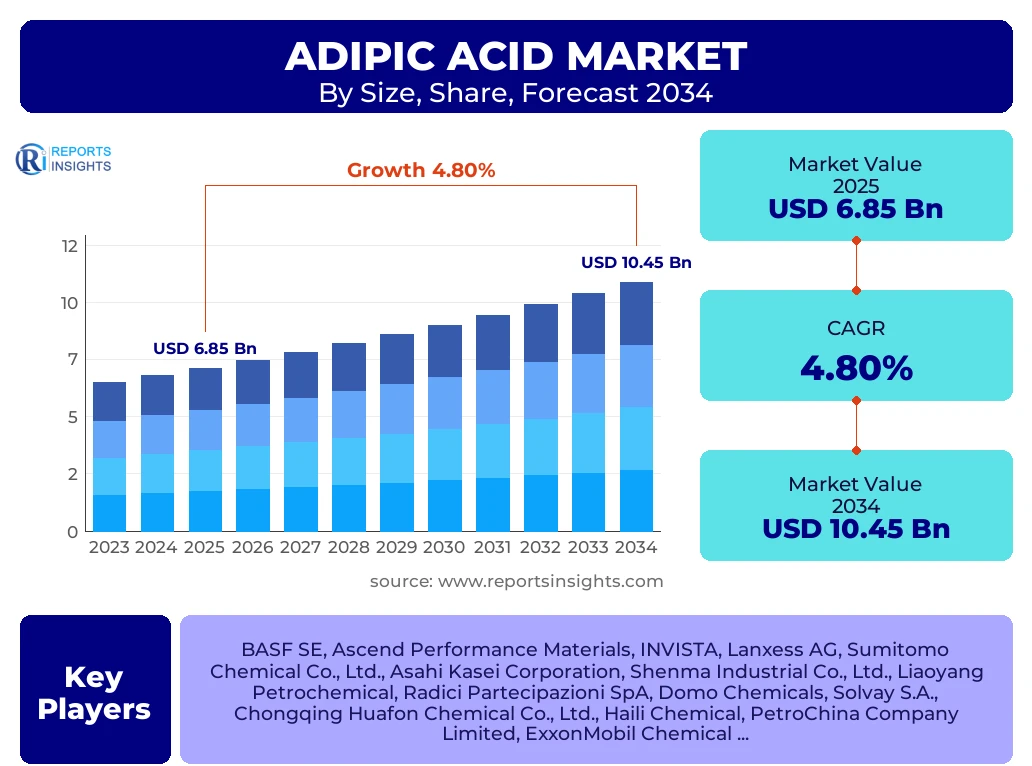
According to Reports Insights Consulting Pvt Ltd, The Adipic Acid Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.8% between 2026 and 2034. The market is estimated at USD 7.18 Billion in 2026 and is projected to reach USD 10.45 Billion by the end of the forecast period in 2034.
Key Adipic Acid Market Trends & Insights
The global adipic acid market is undergoing a significant transformation driven by the increasing demand for high-performance engineering plastics and the automotive industry’s shift toward lightweight materials. As the primary feedstock for Nylon 6,6, adipic acid remains critical to the production of durable components in automotive, electronics, and industrial machinery. Current market dynamics reflect a dual focus on scaling production capacity in emerging economies and investing in sustainable, bio-based alternatives to traditional petrochemical routes. The rise of Electric Vehicles (EVs) is a particularly potent trend, as these vehicles require advanced thermal management systems and lightweight structural components, both of which utilize nylon-based resins. Furthermore, the convergence of stringent environmental regulations regarding nitrous oxide (N2O) emissions and the push for circular economy practices is compelling manufacturers to adopt advanced abatement technologies and explore renewable raw materials like lignin or agricultural waste.
- Largest Region: Asia-Pacific, led predominantly by China, maintains the largest market share due to its massive manufacturing base for textiles and automotive components.
- Fastest Growing Region: Southeast Asia and parts of the Middle East are experiencing the most rapid growth, fueled by industrialization and infrastructure development.
- Largest Segment by Application: The Nylon 6,6 fiber and resin segment continues to dominate, accounting for over 75% of the total market volume.
- Key Trend: Transition toward bio-adipic acid as major brands in the apparel and automotive sectors seek to reduce their scope 3 carbon emissions.
Key Takeaways Adipic Acid Market Size & Forecast
The market trajectory for adipic acid remains robust, characterized by steady demand in traditional sectors and emerging applications in renewable energy and high-end consumer goods. Stakeholders are increasingly focusing on vertical integration to hedge against the volatility of benzene prices, which serves as the primary raw material. The forecast period is expected to see a consolidation of market players as smaller entities struggle with the high capital expenditure required for environmental compliance and technological upgrades. Digitalization of the supply chain and the implementation of AI-driven predictive maintenance in production facilities are also becoming standard practices to optimize yield and reduce operational downtime. The market’s resilience is further supported by the diversification of end-use industries, including footwear, food additives, and pharmaceutical coatings.
- The global market value is expected to surpass the 10 billion dollar mark by 2034, driven by a 4.8% CAGR.
- China remains the manufacturing powerhouse, contributing more than 40% of the global adipic acid production capacity.
- Polyurethane (PU) production is the second-largest application area, growing significantly in the construction and insulation sectors.
- The automotive industry’s move toward vehicle electrification is providing a sustained tailwind for high-grade adipic acid demand.
- Technological advancements in green chemistry are expected to make bio-based adipic acid cost-competitive by the end of the decade.
Adipic Acid Market Drivers Analysis
The primary catalysts for the adipic acid market include the surging demand for lightweight automotive parts and the expansion of the global textile industry. As fuel efficiency standards tighten, automakers are replacing metal parts with high-strength Nylon 6,6, which is derived from adipic acid. Additionally, the rapid growth of e-commerce is increasing the demand for durable packaging solutions, many of which utilize adipic acid-based polymers. The industrialization of emerging economies also plays a vital role as infrastructure projects require high-performance coatings and sealants.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Nylon 6,6 demand for Automotive Lightweighting | +1.5% | Global (High in Germany, US, China) | 2025–2034 |
| Growth of the Electronics and Electrical (E&E) Sector | +1.1% | APAC (South Korea, Taiwan, China) | 2025–2030 |
| Expansion of Polyurethane usage in Construction | +0.9% | North America and Europe | 2026–2034 |
Adipic Acid Market Restraints Analysis
Market growth is hindered by the environmental impact of adipic acid production, specifically the emission of nitrous oxide, a potent greenhouse gas. Stringent environmental regulations in Europe and North America require expensive abatement systems, increasing production costs. Furthermore, the volatility of crude oil prices directly impacts the cost of benzene, the primary feedstock, leading to unpredictable profit margins for manufacturers. The emergence of alternative high-performance polymers that do not rely on adipic acid also presents a competitive threat.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Environmental Regulations and N2O Emission Standards | -0.8% | European Union, United States | 2025–2034 |
| Volatility in Benzene Feedstock Pricing | -0.6% | Global | Continuous |
Adipic Acid Market Opportunities Analysis
The development of bio-based adipic acid offers a significant opportunity for market players to cater to the growing "green" consumer segment and meet corporate sustainability goals. Innovations in manufacturing processes that utilize renewable feedstocks like glucose or lignin are gaining traction. Additionally, the expansion of the high-end footwear and apparel industries, particularly in the athleisure segment, provides a growing market for adipic acid-derived fibers. The market for adipic acid in the pharmaceutical industry as a pH adjuster and pill coating also remains a niche but high-value opportunity.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Commercialization of Bio-based Adipic Acid | +1.2% | Europe and North America | 2027–2034 |
| Rising Demand in High-Performance Footwear | +0.7% | Vietnam, Indonesia, China | 2025–2030 |
Adipic Acid Market Challenges Impact Analysis
One of the most pressing challenges is the disruption of global supply chains, which can lead to shortages of key catalysts and raw materials. Additionally, the high energy consumption associated with traditional adipic acid production makes manufacturers vulnerable to energy price spikes. Geopolitical tensions in key manufacturing hubs can also disrupt trade flows and lead to regional supply-demand imbalances. Maintaining product purity for high-end applications like food and pharma while managing costs remains a technical hurdle for many producers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Energy Consumption in Production Processes | -0.5% | Global (Impactful in EU) | 2025–2034 |
| Supply Chain Instability and Geopolitical Risks | -0.4% | Global | Short to Medium Term |
Adipic Acid Market - Updated Report Scope
This comprehensive market research report provides an in-depth analysis of the global adipic acid industry, covering production volumes, consumption patterns, and trade dynamics. It examines the entire value chain from petrochemical feedstocks to end-use applications in automotive, textiles, and industrial sectors. The scope includes a detailed breakdown of market segments, regional performance, and the competitive landscape, featuring profiles of the world's leading chemical producers. The report also integrates the latest technological advancements and regulatory updates to provide a forward-looking perspective on the market's evolution through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 6.85 Billion |
| Market Forecast in 2034 | USD 10.45 Billion |
| Growth Rate | 4.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Ascend Performance Materials, INVISTA, Lanxess AG, Sumitomo Chemical Co., Ltd., Asahi Kasei Corporation, Shenma Industrial Co., Ltd., Liaoyang Petrochemical, Radici Partecipazioni SpA, Domo Chemicals, Solvay S.A., Chongqing Huafon Chemical Co., Ltd., Haili Chemical, PetroChina Company Limited, ExxonMobil Chemical, Mitsubishi Chemical Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The adipic acid market is segmented based on raw material source, application, and end-use industry. This multifaceted segmentation allows for a precise understanding of which sectors are driving volume and which are contributing to value growth. Nylon 6,6 production remains the cornerstone of the market, but the diversification into specialty esters and high-purity food-grade adipic acid is providing new avenues for revenue. Analyzing these segments reveals the shifting priorities of global manufacturers as they balance industrial demand with environmental responsibility.
- By Application: Nylon 6,6 Fiber represents the largest application, primarily used in carpets, tire cords, and apparel. Nylon 6,6 Resin is the second-largest, crucial for engineering plastics in automotive and electronics.
- By Raw Material: Cyclohexane remains the most widely used raw material, though research into cyclohexane-free pathways is increasing to improve sustainability scores.
- By End-Use: The Automotive industry is the leading consumer, followed by Textiles and Consumer Goods. The Pharmaceutical and Food industries are smaller but represent high-margin segments for high-purity adipic acid.
Regional Highlights
- Asia-Pacific: This region is both the largest producer and consumer of adipic acid. China's rapid industrialization and its status as a global textile hub make it the focal point of the market. The presence of numerous domestic manufacturers like Shenma and Huafon ensures a competitive and high-volume environment.
- Europe: The European market is characterized by a high focus on sustainability and regulatory compliance. It is a leader in the development of bio-based adipic acid and advanced abatement technologies. Germany and Italy are key hubs for automotive and textile applications, respectively.
- North America: Driven by a strong automotive sector and recovering manufacturing activity, the U.S. is a major player. Large-scale producers like Ascend and INVISTA dominate the landscape, with a significant portion of production dedicated to high-performance Nylon 6,6 for the aerospace and defense sectors.
- Latin America & MEA: These regions are emerging markets with growing demand for polyurethane in construction and fibers for the footwear industry. Growth is steady, supported by increasing foreign direct investment in manufacturing.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Adipic Acid Market.- BASF SE
- Ascend Performance Materials
- INVISTA
- Lanxess AG
- Sumitomo Chemical Co., Ltd.
- Asahi Kasei Corporation
- Shenma Industrial Co., Ltd.
- Liaoyang Petrochemical
- Radici Partecipazioni SpA
- Domo Chemicals
- Solvay S.A.
- Chongqing Huafon Chemical Co., Ltd.
- Haili Chemical
- PetroChina Company Limited
- ExxonMobil Chemical
- Mitsubishi Chemical Corporation
- Tangshan Zhonghao Chemical
- Shandong Haili Chemical Industry
- Versalis S.p.A.
- Zhejiang Huafon Thermoplastic Polyurethane
Frequently Asked Questions
What is the primary use of adipic acid in the industrial sector?
The primary use of adipic acid is as a precursor for the production of Nylon 6,6, which is used in fibers for textiles and carpets, as well as in engineering resins for automotive and electronic components.
Which region holds the largest share of the adipic acid market?
Asia-Pacific currently holds the largest share of the adipic acid market, accounting for over 45% of global consumption, largely driven by the massive manufacturing sectors in China and India.
How is the automotive industry's shift to electric vehicles affecting the adipic acid market?
The shift to EVs is driving demand for adipic acid-based Nylon 6,6 because these vehicles require lightweight materials to extend battery range and advanced polymers for thermal management and electrical insulation.
What are the environmental concerns associated with adipic acid production?
The main environmental concern is the emission of nitrous oxide (N2O), a potent greenhouse gas, during the nitric acid oxidation process. Manufacturers are increasingly adopting thermal and catalytic abatement technologies to mitigate this impact.
What is the outlook for bio-based adipic acid?
The outlook for bio-based adipic acid is highly positive, with several pilot projects moving toward commercial scale. It is expected to see a significant increase in market share as companies look to meet carbon neutrality targets by 2030.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
