Active Protection System Market
Active Protection System Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711620 | Published On : November 08, 2026 |
Format : 


 | Author : Ashraf Shehata
Active Protection System Market Size
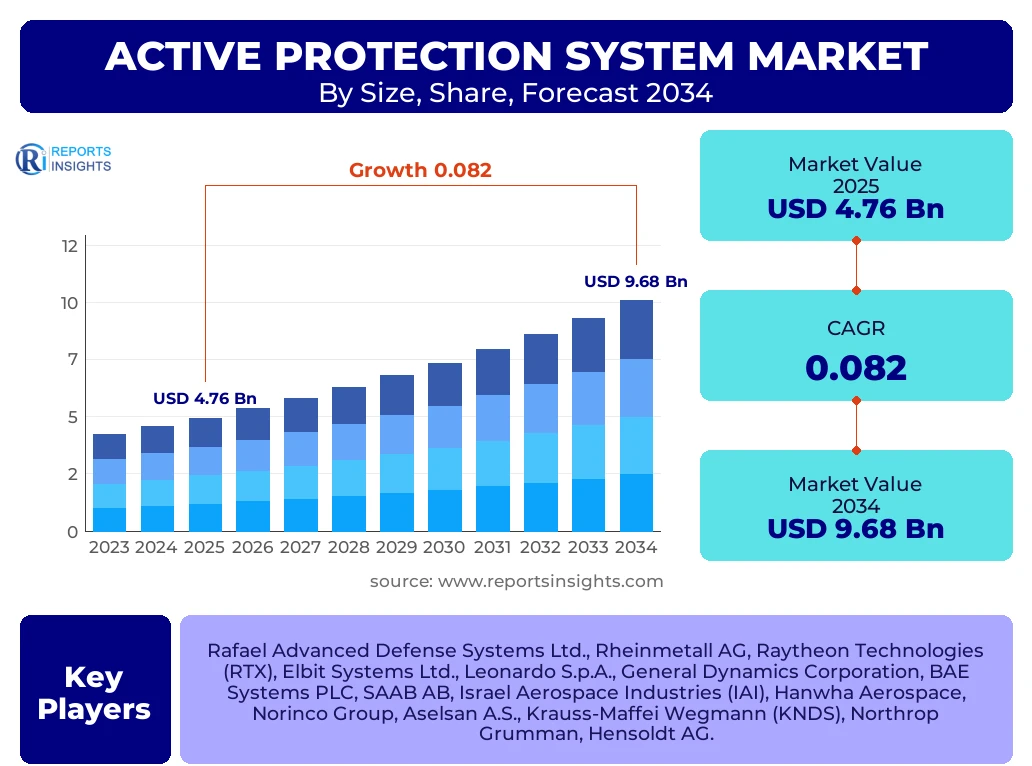
According to Reports Insights Consulting Pvt Ltd, The Active Protection System Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.2% between 2025 and 2034. The market is estimated at USD 5.15 Billion in 2026 and is projected to reach USD 9.68 Billion by the end of the forecast period in 2034.
Key Active Protection System Market Trends & Insights
The global Active Protection System (APS) market is undergoing a transformative phase driven by the rapid evolution of anti-tank guided missiles (ATGMs) and the proliferation of loitering munitions in modern conflict zones. Strategic shifts in land warfare, particularly observed in recent Eastern European and Middle Eastern conflicts, have highlighted the vulnerability of traditional main battle tanks (MBTs) and armored personnel carriers (APCs). As a result, defense ministries are prioritizing the integration of sophisticated hard-kill and soft-kill systems. The integration of Artificial Intelligence (AI) and Machine Learning (ML) into APS suites is a primary trend, enabling systems to differentiate between actual threats and environmental clutter with unprecedented speed. Furthermore, the push for modularity allows for the retrofitting of legacy fleets, ensuring that older platforms remain viable against contemporary precision-guided threats.
- Largest Region: North America remains the largest market due to extensive defense spending, the presence of major aerospace and defense primes, and the ongoing modernization of the U.S. Army's Stryker and Abrams platforms.
- Fastest Growing Region: Asia Pacific is anticipated to exhibit the highest CAGR, fueled by rising geopolitical tensions, territorial disputes, and significant indigenous development programs in countries like India, China, and South Korea.
- Leading Segment by Type: The Hard-Kill System segment holds the largest market share as it provides a physical destruction mechanism against high-velocity kinetic energy penetrators and modern ATGMs.
- Leading Segment by Platform: Land-based platforms, specifically Main Battle Tanks and Infantry Fighting Vehicles, represent the dominant share of the global APS market.
Key Takeaways Active Protection System Market Size & Forecast
The trajectory of the Active Protection System market is defined by a move toward multi-layered defense architectures. Stakeholders are increasingly focusing on systems that offer 360-degree coverage and the ability to intercept multiple simultaneous threats, commonly referred to as "saturation attacks." The forecast period will see a transition from standalone installations to fully integrated vehicle protection suites (VPS) that combine electronic warfare, physical interceptors, and advanced sensor fusion. As electronic signatures become more critical, the development of low-observable and low-probability-of-intercept (LPI) radar for threat detection is becoming a standard requirement for next-generation APS contracts.
- Strategic Modernization: The U.S. and NATO members are aggressively funding the Modular Active Protection Systems (MAPS) framework to prevent vendor lock-in and enhance interoperability.
- Technological Convergence: The convergence of Directed Energy Weapons (DEW) with soft-kill APS is emerging as a high-potential area for naval and high-value land assets.
- Supply Chain Resilience: Significant investments are being made to secure domestic production of high-frequency sensors and semiconductor components essential for APS response times.
- Emergence of Drone Defense: APS providers are recalibrating systems to handle the unique flight profiles of low-slow-small (LSS) drones and top-attack munitions.
Active Protection System Market Drivers Analysis
The primary catalysts for market expansion involve the heightened lethality of the modern battlefield and the critical need to preserve high-value manned assets. As non-state actors and conventional militaries alike gain access to sophisticated shoulder-fired weapons and drone swarms, the traditional reliance on passive armor has become insufficient. This necessitates a proactive defense layer that intercepts threats before they impact the hull.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Proliferation of Advanced ATGMs and RPGs | +2.4% | Global (High in Middle East/Europe) | 2025–2034 |
| Modernization of Legacy Armored Vehicle Fleets | +1.8% | United States, India, Russia | 2025–2030 |
| Integration of AI and Rapid Threat Detection | +1.5% | Israel, Germany, United Kingdom | 2027–2034 |
| Increased Defense Budgets Amidst Geopolitical Volatility | +2.5% | Asia Pacific, NATO Members | 2025–2034 |
Active Protection System Market Restraints Analysis
Despite the high demand, the market faces significant headwinds related to the high cost of implementation and the technical complexities of system integration. Furthermore, concerns regarding collateral damage to dismounted infantry and civilians in urban environments remain a significant deterrent for the widespread deployment of hard-kill systems.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Procurement and Life-cycle Maintenance Costs | -1.2% | Developing Nations (Brazil, South Africa) | 2025–2034 |
| Risk of Collateral Damage to Nearby Infantry | -0.8% | European Union (Urban Warfare focus) | 2025–2029 |
| Interoperability and Weight Constraints on Light Vehicles | -1.0% | United States (L-ATV programs) | 2026–2032 |
Active Protection System Market Opportunities Analysis
The market is ripe with opportunities for innovation in the realm of lightweight APS for tactical vehicles and the application of APS technology in naval and airborne domains. The move toward "Software Defined Protection" provides a lucrative path for companies specializing in digital signal processing and cyber-resilient defense architectures.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Micro-APS for Tactical Unmanned Vehicles | +1.7% | South Korea, Japan, United States | 2028–2034 |
| Export Opportunities to Emerging Defense Markets | +1.3% | Middle East, Southeast Asia | 2026–2034 |
| Directed Energy (Laser) Soft-Kill Enhancements | +2.1% | Israel, Germany, USA | 2029–2034 |
Active Protection System Market Challenges Impact Analysis
Technical challenges such as reducing the "SWaP" (Size, Weight, and Power) footprint and ensuring electromagnetic compatibility (EMC) in sensor-dense environments pose significant hurdles. Additionally, the rapid evolution of threat countermeasures, such as dual-warhead missiles designed to spoof APS, requires continuous software and hardware updates.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Complexity of Multi-Threat Saturation Interception | -0.9% | Global | 2025–2034 |
| Cyber Vulnerabilities in Networked Defense Suites | -0.7% | NATO Members, China | 2027–2034 |
| Long Certification and Regulatory Approval Timelines | -1.1% | European Union, Australia | 2025–2030 |
Active Protection System Market - Updated Report Scope
This comprehensive market analysis covers the global landscape of Active Protection Systems, focusing on the technological advancements, procurement trends, and competitive dynamics across various military branches. The scope includes an in-depth evaluation of hard-kill and soft-kill mechanisms, their integration into land, naval, and airborne platforms, and the emerging role of electronic warfare in preemptive threat neutralization. The report also examines the impact of the shift toward open-architecture systems and the growing importance of domestic manufacturing capabilities in the global defense supply chain.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.76 Billion |
| Market Forecast in 2034 | USD 9.68 Billion |
| Growth Rate | 8.2% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Rafael Advanced Defense Systems Ltd., Rheinmetall AG, Raytheon Technologies (RTX), Elbit Systems Ltd., Leonardo S.p.A., General Dynamics Corporation, BAE Systems PLC, SAAB AB, Israel Aerospace Industries (IAI), Hanwha Aerospace, Norinco Group, Aselsan A.S., Krauss-Maffei Wegmann (KNDS), Northrop Grumman, Hensoldt AG. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Active Protection System market is segmented based on the mechanism of intervention, the platform of installation, and the critical components involved. This granular approach allows for a precise understanding of which technologies are driving growth in specific military sectors. Hard-kill systems remain the gold standard for high-intensity conflict, while soft-kill systems, which utilize jammers and decoys, are increasingly integrated as a first layer of defense to minimize the use of kinetic interceptors. The platform-based segmentation reveals a surging demand in the naval sector for protection against anti-ship cruise missiles, while the land segment continues to dominate in total volume.
- By System Type:
- Hard-Kill Systems: Includes interceptors like launchers and high-speed projectiles. These are the primary choice for main battle tanks.
- Soft-Kill Systems: Focuses on smoke screens, IR decoys, and electronic jamming. High growth in naval applications.
- Hybrid Systems: Combined suites that offer a tiered defense approach.
- By Platform:
- Land-based Platforms: Main Battle Tanks (MBTs), Infantry Fighting Vehicles (IFVs), Armored Personnel Carriers (APCs), and Mine-Resistant Ambush Protected (MRAP) vehicles.
- Naval Platforms: Destroyers, Frigates, and Corvettes requiring defense against sea-skimming missiles.
- Airborne Platforms: Heavy-lift helicopters and tactical transport aircraft.
- By Component:
- Sensors: Active Electronically Scanned Array (AESA) radars and Infrared (IR) cameras.
- Countermeasures: Grenade launchers, laser dazzlers, and jamming pods.
- Fire Control Systems: The central processing unit that manages threat detection and engagement logic.
Regional Highlights
- North America: The largest market globally, characterized by massive procurement of the Trophy APS for the M1 Abrams and the investigation of StrikeShield for lighter vehicle classes. The U.S. remains the primary hub for R&D in modular APS.
- Europe: Driven by the urgent need to modernize armored formations in the wake of renewed continental security threats. Countries like Poland, Germany, and the UK are investing heavily in both indigenous and Israeli-developed systems.
- Asia Pacific: The fastest-growing region. China and India are developing indigenous APS (such as India's focus on the 'Zorawar' light tank protection), while South Korea is exporting its K2 Black Panther, which features high-end integrated APS.
- Middle East: A mature market for APS, with Israel being a global leader in technology development and deployment. The region serves as the primary testing ground for real-world APS performance.
- Latin America & MEA: These regions are showing interest in modular, cost-effective soft-kill solutions to protect assets against insurgent-style RPG threats.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Active Protection System Market.- Rafael Advanced Defense Systems Ltd. (Israel)
- Rheinmetall AG (Germany)
- Raytheon Technologies (RTX) (United States)
- Elbit Systems Ltd. (Israel)
- Leonardo S.p.A. (Italy)
- General Dynamics Corporation (United States)
- BAE Systems PLC (United Kingdom)
- SAAB AB (Sweden)
- Israel Aerospace Industries (IAI) (Israel)
- Hanwha Aerospace (South Korea)
- Norinco Group (China)
- Aselsan A.S. (Turkey)
- Krauss-Maffei Wegmann (KNDS) (Germany)
- Northrop Grumman (United States)
- Hensoldt AG (Germany)
- Thales Group (France)
- Lockheed Martin Corporation (United States)
- Mitsubishi Heavy Industries (Japan)
- Uralvagonzavod (Russia)
Frequently Asked Questions
The following section addresses the most critical inquiries regarding the market dynamics and future outlook of the global Active Protection System industry.
What is the difference between Hard-Kill and Soft-Kill Active Protection Systems?
Hard-kill systems physically intercept and destroy an incoming threat using projectiles or blast effects. Soft-kill systems use non-kinetic means such as electronic jamming, smoke screens, or flares to confuse the threat's guidance system and cause it to miss its target. Many modern platforms now use a hybrid approach combining both.
What is the projected growth rate of the APS market through 2034?
The market is expected to grow at a CAGR of 8.2% from 2026 to 2034, driven by military modernization programs and the increasing use of anti-tank weapons in regional conflicts.
Which region is the global leader in Active Protection System technology?
Israel is widely considered the technological leader, with its Trophy and Iron Fist systems being the only combat-proven hard-kill systems widely adopted by major militaries, including the United States.
How is Artificial Intelligence impacting the APS market?
AI is being used to drastically reduce response times, allowing systems to identify, track, and engage threats within milliseconds. It also helps in reducing false alarm rates caused by non-threatening environmental objects or small-arms fire.
What are the main challenges for APS deployment on light tactical vehicles?
The primary challenges are "SWaP" constraints—Size, Weight, and Power. APS units are traditionally heavy and power-intensive, which can degrade the mobility and fuel efficiency of lighter vehicles like the JLTV or HMMWV. Development of "Micro-APS" is currently underway to address this.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
