Acetic Acid Market
Acetic Acid Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710914 | Published On : September 17, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Acetic Acid Market Size
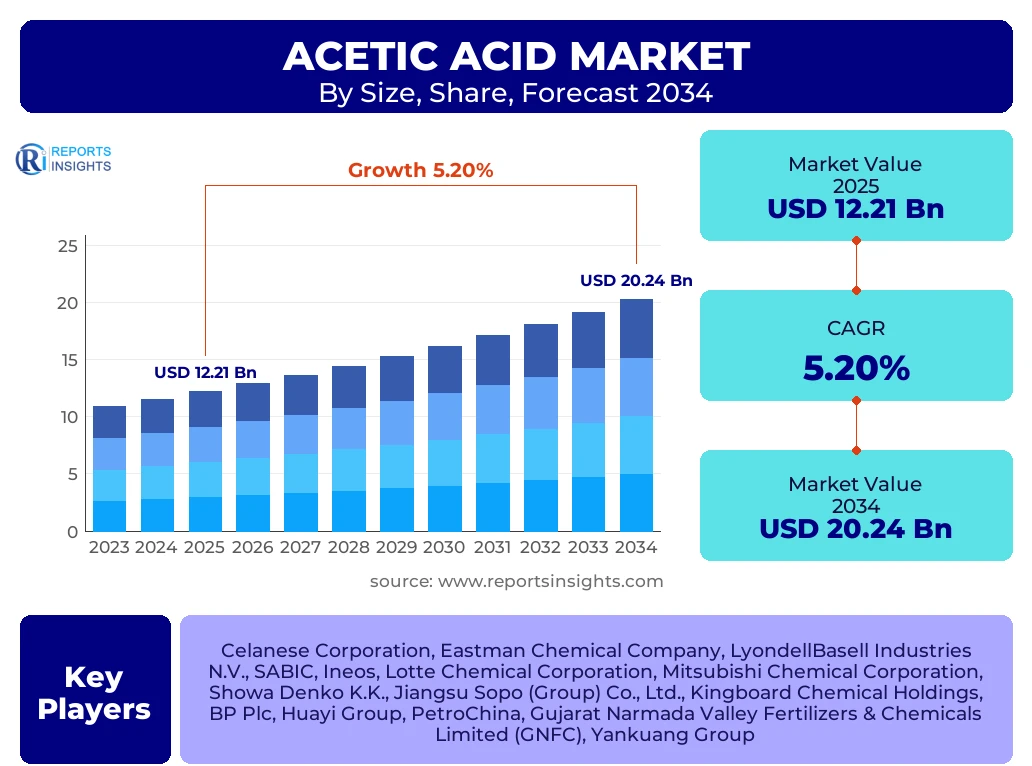
According to Reports Insights Consulting Pvt Ltd, The Acetic Acid Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2026 and 2034. The market is estimated at USD 12.85 Billion in 2026 and is projected to reach USD 20.24 Billion by the end of the forecast period in 2034.
Key Acetic Acid Market Trends & Insights
The global acetic acid market is undergoing a significant transformation driven by the escalating demand for Vinyl Acetate Monomer (VAM) and Purified Terephthalic Acid (PTA). Market participants are increasingly focusing on technological advancements in carbonylation processes to improve yield and reduce carbon footprints. The shift toward bio-based acetic acid is a critical trend, as industries seek sustainable alternatives to traditional petrochemical routes. Furthermore, the integration of digital twins and AI-driven process optimization in manufacturing facilities is enhancing operational efficiency across the supply chain, particularly in high-volume production hubs in the Asia-Pacific region.
- Largest region: Asia-Pacific remains the dominant global market, accounting for over 50% of total consumption due to massive industrialization in China and India.
- Fastest growing region: Southeast Asia is emerging as the fastest-growing sub-region, fueled by expanding textile and construction sectors.
- Largest segment by application: Vinyl Acetate Monomer (VAM) represents the largest application segment, driven by the demand for adhesives, coatings, and paints.
- Largest segment by end-use: The construction and infrastructure sector continues to lead the market share, utilizing acetic acid derivatives for high-performance resins and paints.
Key Takeaways Acetic Acid Market Size & Forecast
The forecast period from 2025 to 2034 indicates a steady upward trajectory for the acetic acid market, underpinned by the recovery of global manufacturing and increased infrastructure spending. Strategic shifts toward green chemistry and the adoption of recycled acetic acid in chemical synthesis are expected to redefine competitive benchmarking. Enterprises are prioritizing long-term supply agreements to mitigate price volatility of raw materials like methanol and natural gas. The convergence of strict environmental regulations and the need for high-purity industrial chemicals is creating a bifurcated market where high-grade acetic acid commands a premium.
- China dominance: China is the single largest producer and consumer of acetic acid, dictating global price movements and supply dynamics.
- Strategic capacity expansions: Major players are announcing brownfield and greenfield expansions in the Middle East to capitalize on low-cost feedstock availability.
- VAM market synergy: The direct correlation between the demand for ethylene-vinyl acetate (EVA) copolymers in solar panels and acetic acid growth is a pivotal market driver.
- Pharmaceutical growth: Increasing use of acetic acid as a solvent and reagent in the pharmaceutical industry, particularly in developing economies, is contributing to high-value market growth.
Acetic Acid Market Drivers Analysis
The primary driver for the acetic acid market is the robust demand for Vinyl Acetate Monomer (VAM), which is an essential building block for adhesives, paints, and coatings used extensively in the construction industry. As urbanization accelerates in emerging economies, the need for architectural coatings and high-performance adhesives has skyrocketed. Additionally, the textile industry’s reliance on polyester—which requires Purified Terephthalic Acid (PTA) produced using acetic acid as a solvent—continues to provide a stable foundation for market expansion.
Furthermore, the food and beverage industry is increasingly utilizing acetic acid as a preservative and flavoring agent, known commercially as vinegar. The growing consumer preference for clean-label preservatives and the expansion of the processed food sector are amplifying this demand. Technological advancements in the Monsanto and Cativa processes have also lowered production costs, making acetic acid more accessible for a wider range of downstream applications.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Demand for VAM in Paints & Coatings | +1.8% | Global (Primary: China, India) | 2025–2034 |
| Expansion of the Polyester and Textile Industry | +1.4% | Asia-Pacific and Africa | 2025–2030 |
| Growth in Food Preservation Requirements | +0.9% | North America and Europe | 2026–2034 |
Acetic Acid Market Restraints Analysis
Market growth is significantly challenged by the extreme volatility in the prices of raw materials, specifically methanol and natural gas. Since methanol carbonylation is the most common production method, any fluctuation in natural gas prices directly impacts the production margins of acetic acid. This volatility often leads to supply chain uncertainties and necessitates frequent price adjustments by manufacturers, which can dampen demand in price-sensitive segments.
Environmental and safety regulations also act as a major restraint. Acetic acid is highly corrosive and poses significant health risks if not handled correctly, leading to stringent transportation and storage mandates. Moreover, the environmental impact of traditional manufacturing processes, which involve high carbon emissions, has led to increased regulatory scrutiny and the implementation of carbon taxes in regions like Europe, forcing manufacturers to invest heavily in carbon capture or greener production alternatives.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Feedstock Price Volatility (Methanol/Natural Gas) | -1.2% | Global | Continuous |
| Stringent Environmental Regulations | -0.8% | European Union, North America | 2025–2034 |
Acetic Acid Market Opportunities Analysis
The emergence of bio-based acetic acid presents a transformative opportunity for the industry. Produced via the fermentation of biomass or industrial waste, bio-acetic acid caters to the rising demand for sustainable and eco-friendly chemical products. As multinational corporations commit to "Net Zero" targets, the adoption of bio-based acetic acid in the production of bio-polymers and sustainable coatings is expected to gain significant traction, particularly in the European and North American markets.
Additionally, the rising demand for Acetic Anhydride in the pharmaceutical sector for the synthesis of aspirin and other essential medicines offers a lucrative growth avenue. The development of new applications for ethyl acetate in the flexible packaging industry, driven by the shift away from plastic to more sustainable solvent-based laminates, further expands the market horizon. Strategic investments in high-growth markets like India and Brazil are also expected to yield high returns as these regions industrialize.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based Acetic Acid | +1.5% | Europe and North America | 2027–2034 |
| Pharmaceutical Industry Expansion | +1.1% | India, China, Germany | 2025–2034 |
| Advancements in Recycled Acetic Acid | +0.7% | Japan and South Korea | 2028–2034 |
Acetic Acid Market Challenges Impact Analysis
One of the primary challenges facing the market is the intense competitive pressure from alternative chemicals and substitutes. In some applications, bio-succinic acid or other organic acids may compete with acetic acid derivatives. Furthermore, the geographical concentration of production in China creates a significant risk of supply chain disruption. Trade tensions, geopolitical conflicts, and regional logistics bottlenecks can lead to sudden shortages and price spikes in the global market.
The high capital expenditure required for setting up modern, low-emission acetic acid plants also serves as a barrier to entry for smaller players. Upgrading legacy facilities to meet new environmental standards is a complex and costly endeavor. Additionally, the transition toward a circular economy requires the development of efficient recovery and recycling technologies for acetic acid used as a solvent, which currently faces technical and economic hurdles.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Dependency on China | -1.0% | Global Supply Chain | 2025–2030 |
| High CAPEX for Greener Technology | -0.6% | Emerging Markets | 2025–2034 |
Acetic Acid Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global acetic acid ecosystem, covering production technologies, downstream derivatives, and end-user industries. It provides granular insights into the competitive landscape, regional market shares, and the strategic maneuvers of key players. The report also evaluates the impact of macroeconomic factors and regulatory shifts on the market's long-term growth trajectory, offering a detailed forecast from 2026 to 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 12.21 Billion |
| Market Forecast in 2034 | USD 20.24 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Celanese Corporation, Eastman Chemical Company, LyondellBasell Industries N.V., SABIC, Ineos, Lotte Chemical Corporation, Mitsubishi Chemical Corporation, Showa Denko K.K., Jiangsu Sopo (Group) Co., Ltd., Kingboard Chemical Holdings, BP Plc, Huayi Group, PetroChina, Gujarat Narmada Valley Fertilizers & Chemicals Limited (GNFC), Yankuang Group |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The acetic acid market is segmented based on application, end-use industry, and manufacturing process. The application segment is dominated by Vinyl Acetate Monomer (VAM), which is the primary raw material for aqueous emulsions and resins. The Purified Terephthalic Acid (PTA) segment follows closely, driven by the global demand for PET bottles and polyester fibers. The end-use industry segmentation reveals the construction sector as the primary consumer, although the pharmaceutical and food sectors are showing significant growth rates due to specialized applications.
- By Application:
- Vinyl Acetate Monomer (VAM)
- Purified Terephthalic Acid (PTA)
- Acetic Anhydride
- Ethyl Acetate
- Butyl Acetate
- Monochloroacetic Acid (MCA)
- By End-Use Industry:
- Construction and Infrastructure
- Textiles and Apparel
- Food and Beverage (Preservatives/Vinegar)
- Pharmaceuticals
- Plastics and Polymers
- Paints and Coatings
- By Production Method:
- Methanol Carbonylation (Monsanto/Cativa)
- Acetaldehyde Oxidation
- Ethylene Oxidation (Wacker Process)
- Bio-fermentation
Regional Highlights
- Asia-Pacific: The region holds the largest market share, with China acting as the global manufacturing hub. Growth is driven by rapid urbanization and the presence of massive textile and plastic industries.
- North America: This market is characterized by technological maturity and a strong presence of major chemical manufacturers. The focus is on high-purity acetic acid for the pharmaceutical and food industries.
- Europe: The market is influenced by strict REACH regulations and a strong push toward bio-based chemicals. Sustainability and carbon reduction are the key themes in this region.
- Middle East & Africa: Growth is fueled by the availability of low-cost feedstock and significant investments in downstream chemical production to diversify economies away from crude oil.
- Latin America: Brazil and Mexico are emerging as key markets due to the expansion of the construction and food processing sectors.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Acetic Acid Market.- Celanese Corporation
- Eastman Chemical Company
- LyondellBasell Industries N.V.
- SABIC
- Ineos
- Lotte Chemical Corporation
- Mitsubishi Chemical Corporation
- Showa Denko K.K.
- Jiangsu Sopo (Group) Co., Ltd.
- Kingboard Chemical Holdings
- BP Plc
- Huayi Group
- PetroChina
- Gujarat Narmada Valley Fertilizers & Chemicals Limited (GNFC)
- Yankuang Group
- Chiba Ethyl Acetate Co., Ltd.
- Sinopec
- Wacker Chemie AG
Frequently Asked Questions
What is the projected growth rate of the global Acetic Acid market?
The global acetic acid market is expected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% from 2025 to 2034, reaching an estimated value of USD 20.24 Billion.
Which application segment holds the largest share in the Acetic Acid market?
The Vinyl Acetate Monomer (VAM) segment currently holds the largest market share, as it is a vital component in the production of adhesives, coatings, and resins used in global construction.
Who are the leading players in the global Acetic Acid market?
The market is led by major chemical corporations including Celanese Corporation, Eastman Chemical Company, Ineos, SABIC, and Lotte Chemical, among others.
What are the key drivers for the Acetic Acid market?
Key drivers include the rising demand for paints and coatings in the construction industry, the expansion of the polyester textile market, and the increasing use of acetic acid in food preservation and pharmaceuticals.
Which region dominates the Acetic Acid market production and consumption?
The Asia-Pacific region, particularly China, dominates the global market in terms of both production capacity and industrial consumption, accounting for over half of the global market share.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted