5G Infrastructure Market
5G Infrastructure Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_700208 | Published On : September 14, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
5G Infrastructure Market Size
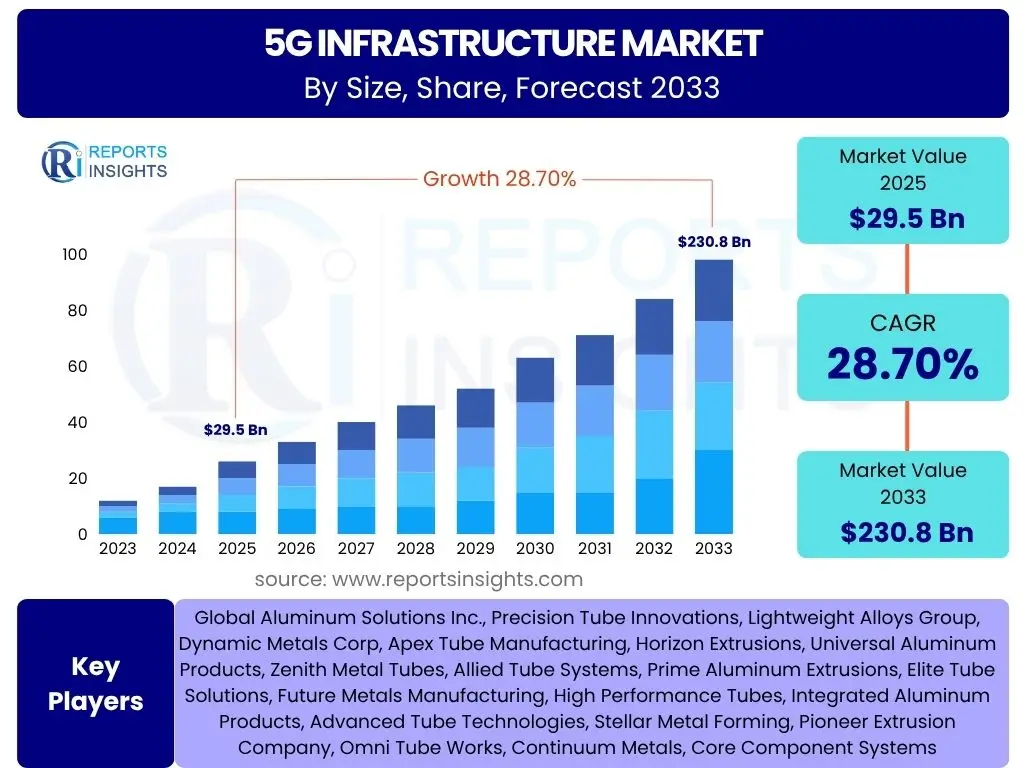
According to Reports Insights Consulting Pvt Ltd, The 5G Infrastructure Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 28.3% between 2026 and 2034. The market is estimated at USD 52.4 Billion in 2026 and is projected to reach USD 492.8 Billion by the end of the forecast period in 2034.
Key 5G Infrastructure Market Trends & Insights
The global 5G infrastructure landscape is undergoing a significant transformation as telecommunication service providers pivot from initial coverage-centric deployments to capacity-driven and enterprise-specific network architectures. Current market intelligence indicates that the integration of Open Radio Access Network (O-RAN) architectures is the most disruptive trend, allowing operators to move away from vendor lock-in and adopt more flexible, software-defined hardware solutions. Furthermore, the convergence of 5G with Edge Computing is facilitating ultra-low latency applications, which are essential for the next generation of industrial automation and smart city initiatives. Market benchmarking reveals that the transition from Non-Standalone (NSA) to Standalone (SA) 5G cores is accelerating, enabling network slicing capabilities that allow operators to offer tiered service levels for diverse user requirements ranging from mission-critical communications to massive machine-type communications (mMTC).
- Asia-Pacific is the largest regional market, driven by massive domestic deployments in China, South Korea, and Japan.
- North America is the fastest-growing region for private 5G network infrastructure, particularly within the manufacturing and logistics sectors.
- The Macro Cell segment currently holds the largest market share due to the initial requirement for broad geographical coverage.
- Small Cell deployments are witnessing the highest growth rate as densification becomes necessary for high-frequency mmWave spectrum utilization.
- Virtual Radio Access Network (vRAN) adoption is increasing as operators seek to reduce operational expenditures through cloud-native solutions.
Key Takeaways 5G Infrastructure Market Size & Forecast
The long-term outlook for the 5G infrastructure market remains exceptionally bullish, supported by a fundamental shift in how global economies utilize connectivity. Analysts observe that the market is no longer solely dependent on consumer mobile broadband upgrades; instead, the primary value proposition has shifted toward industrial digitalization, often referred to as Industry 4.0. The forecast period between 2025 and 2034 will see a massive influx of investment into sub-6 GHz and mmWave bands, with the latter becoming critical for dense urban environments and specialized industrial campus networks. Stakeholders are focusing on the monetization of 5G through enterprise-grade Service Level Agreements (SLAs), leveraging the high reliability and low latency of Standalone 5G networks to replace traditional wired infrastructure in complex environments.
- The global market value is expected to surpass the USD 400 Billion threshold by 2033, reflecting sustained capital investment.
- China remains the leading country in terms of 5G base station installations, accounting for over 35% of the global total.
- The transition to 5G Standalone (SA) architecture is a critical milestone for achieving the full potential of network slicing and edge integration.
- Private 5G networks for the industrial sector represent a multi-billion dollar opportunity that is largely untapped in emerging markets.
- Energy-efficient hardware and "Green 5G" initiatives are becoming a mandatory requirement in procurement cycles for major global operators.
5G Infrastructure Market Drivers Analysis
The expansion of the 5G infrastructure market is primarily propelled by the exponential growth in mobile data traffic and the proliferation of Internet of Things (IoT) devices that require high-bandwidth, low-latency connectivity. Furthermore, the strategic push by governments worldwide to achieve digital sovereignty and national broadband coverage is resulting in favorable regulatory frameworks and subsidies for infrastructure deployment.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Exponential Growth in IoT and Connected Devices | +6.5% | Global | 2025 - 2034 |
| Demand for Ultra-Low Latency in Industrial Automation | +5.2% | Germany, USA, Japan | 2026 - 2030 |
| Government Subsidies and Digital Transformation Initiatives | +4.8% | India, China, EU | 2025 - 2028 |
| Rising Adoption of Virtualized and Open RAN Solutions | +3.9% | North America, UK | 2027 - 2034 |
5G Infrastructure Market Restraints Analysis
Despite the rapid growth, the market faces significant headwinds related to the high capital intensity of deployments, particularly the cost associated with fiber backhaul and site acquisition. Geopolitical tensions also play a role, as bans on certain high-profile vendors have forced some operators to undergo costly "rip and replace" programs, slowing down the overall deployment pace in specific regions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial CAPEX for mmWave and Small Cell Densification | -4.2% | Developing Economies | 2025 - 2029 |
| Geopolitical Trade Restrictions and Vendor Bans | -3.5% | USA, UK, Australia | 2025 - 2027 |
| Complex Regulatory Hurdles for Spectrum Allocation | -2.1% | European Union, India | 2025 - 2030 |
5G Infrastructure Market Opportunities Analysis
The next decade offers massive opportunities in the realm of customized private 5G networks for high-value industries such as mining, healthcare, and logistics. Additionally, the development of 5G-enabled Smart Cities and the integration of Non-Terrestrial Networks (NTN) like satellite-to-phone connectivity present new frontiers for infrastructure expansion into remote and underserved areas.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Private 5G for Industry 4.0 | +7.2% | USA, Germany, South Korea | 2026 - 2034 |
| Integration of 5G with Satellite (NTN) Networks | +4.1% | Global / Remote Regions | 2028 - 2034 |
| Edge Computing and AI-driven Network Management | +5.5% | Global | 2025 - 2034 |
5G Infrastructure Market Challenges Impact Analysis
Key challenges involve the increasing complexity of managing multi-vendor environments and the cybersecurity risks associated with a more software-centric and decentralized network architecture. Moreover, the energy consumption of 5G base stations compared to 4G equivalents poses a sustainability challenge for operators aiming for carbon neutrality.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Vulnerabilities in Virtualized Core | -2.8% | Global | 2025 - 2034 |
| High Energy Consumption and Operational Costs | -3.2% | Global | 2025 - 2034 |
| Interoperability Issues in O-RAN Environments | -1.9% | USA, Europe | 2026 - 2030 |
5G Infrastructure Market - Updated Report Scope
This report provides a comprehensive examination of the global 5G infrastructure ecosystem, covering hardware, software, and services across multiple deployment scenarios. The scope includes a detailed analysis of the transition from legacy 4G systems to 5G Standalone architectures, the rise of Open RAN, and the impact of frequency spectrum variations on hardware specifications. It offers strategic insights into vendor market shares, regional investment patterns, and the technological roadmap through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 40.8 Billion |
| Market Forecast in 2034 | USD 492.8 Billion |
| Growth Rate | 28.3% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Huawei Technologies Co., Ltd., Telefonaktiebolaget LM Ericsson, Nokia Corporation, ZTE Corporation, Samsung Electronics Co., Ltd., NEC Corporation, Cisco Systems, Inc., Fujitsu Limited, Mavenir, Airspan Networks, Affirmed Networks (Microsoft), Altiostar (Rakuten Symphony), CommScope, Comba Telecom Systems, Juniper Networks, Hewlett Packard Enterprise (HPE), Oracle Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The 5G infrastructure market is categorized by the type of hardware deployed, the underlying network architecture, and the frequency bands utilized. The segmentation reflects the diverse technological requirements of different geographic and industrial environments, ranging from broad-area coverage to high-capacity localized networks. Understanding these segments is crucial for stakeholders to identify high-growth niches within the broader telecommunications ecosystem.
- Communication Infrastructure: Divided into Macro Cells and Small Cells. Macro cells provide the foundational coverage layer, while small cells (pico, micro, and femto) are essential for densification in urban centers and indoor industrial environments.
- Network Architecture: Includes Non-Standalone (NSA) and Standalone (SA). NSA relies on existing 4G infrastructure for control signaling, whereas SA uses a dedicated 5G Core, enabling advanced features like ultra-low latency and massive IoT.
- Core Network Technology: Focuses on the virtualization of network functions through Software Defined Networking (SDN) and Network Function Virtualization (NFV), allowing for flexible and scalable service deployment.
- Operating Frequency: Split between Sub-6 GHz (favorable for wide area and building penetration) and mmWave (favorable for extreme data speeds over short distances).
- End-use Industry: Segments applications into Residential (enhanced mobile broadband), Commercial (Smart Offices), Industrial (Industry 4.0, smart factories), and Government/Public Infrastructure (Smart Cities, public safety).
Regional Highlights
- Asia-Pacific: The undisputed leader in market volume, driven by China's aggressive 5G rollout and South Korea's early adoption. The region accounts for over 40% of global infrastructure spending.
- North America: Significant investment in mmWave technology and the world’s leading hub for private 5G network development and Open RAN testing.
- Europe: Focused on industrial 5G applications (Industry 4.0), with Germany leading in private spectrum allocation for manufacturing plants.
- Middle East: Rapid deployment in GCC countries like Saudi Arabia and the UAE as part of national vision programs and smart city initiatives.
- Latin America & Africa: Emerging markets focusing on Sub-6 GHz for widespread connectivity and closing the digital divide, with Brazil and South Africa leading the charge.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the 5G Infrastructure Market.
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- ZTE Corporation
- Samsung Electronics Co., Ltd.
- NEC Corporation
- Cisco Systems, Inc.
- Fujitsu Limited
- Mavenir
- Airspan Networks
- Affirmed Networks (Microsoft)
- Altiostar (Rakuten Symphony)
- CommScope
- Comba Telecom Systems
- Juniper Networks
- Hewlett Packard Enterprise (HPE)
- Oracle Corporation
- Parallel Wireless
- Corning Incorporated
- Extreme Networks
Frequently Asked Questions
What is the projected size of the 5G infrastructure market by 2034?
The global 5G infrastructure market is estimated to reach approximately USD 492.8 Billion by 2034, growing at a robust CAGR of 28.3% during the forecast period.
What are the primary differences between 5G Standalone (SA) and Non-Standalone (NSA) infrastructure?
5G NSA uses the existing 4G LTE core for control functions, while 5G SA uses a dedicated 5G cloud-native core, enabling the full suite of 5G benefits including network slicing and ultra-low latency.
Which region is currently leading the global 5G infrastructure rollout?
Asia-Pacific is the current leader, primarily due to the large-scale deployments and government-backed initiatives in China, South Korea, and Japan.
What role does Open RAN (O-RAN) play in the 5G infrastructure market?
Open RAN allows for interoperability between different hardware and software vendors, reducing vendor lock-in and potentially lowering deployment costs through more competitive and flexible supply chains.
What are the biggest challenges facing 5G infrastructure deployment today?
The key challenges include high capital expenditure (CAPEX) for mmWave density, geopolitical tensions affecting vendor selection, and the high energy consumption requirements of new base stations.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
