Wireless Electric Vehicle Charging Market
Wireless Electric Vehicle Charging Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711619 | Published On : November 08, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Wireless Electric Vehicle Charging Market Size
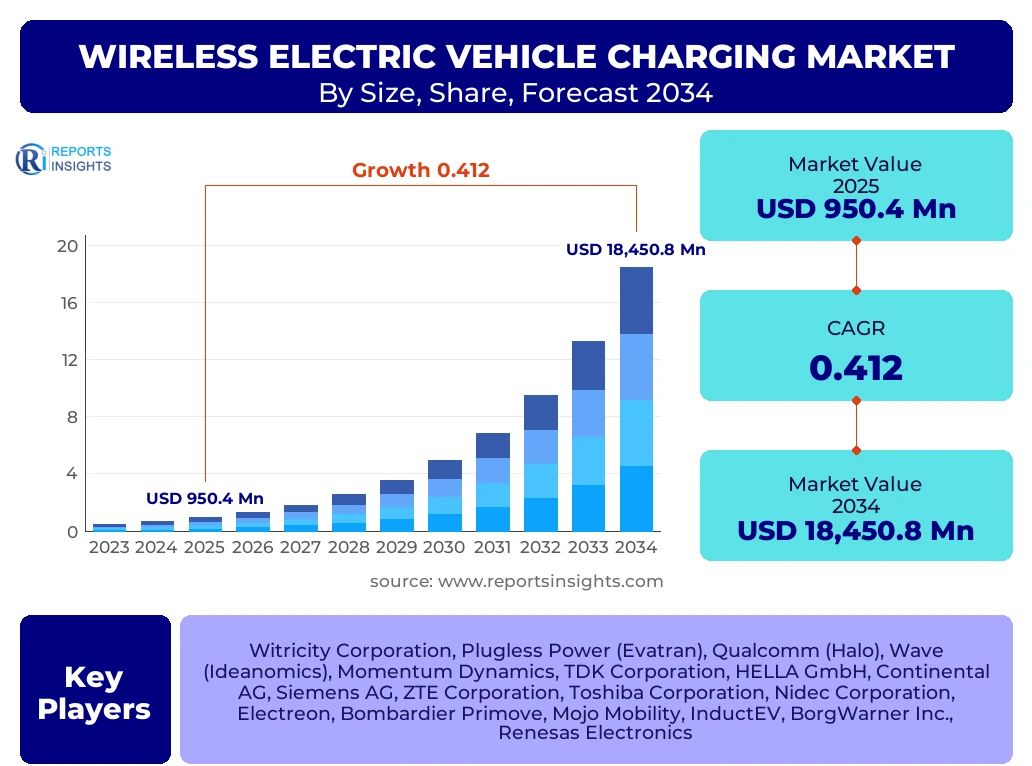
According to Reports Insights Consulting Pvt Ltd, The Wireless Electric Vehicle Charging Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 41.2% between 2025 and 2034. The market is estimated at USD 1,340.5 Million in 2026 and is projected to reach USD 18,450.8 Million by the end of the forecast period in 2034.
The global wireless electric vehicle (EV) charging sector represents a transformative shift in the automotive ecosystem, moving away from traditional plug-in infrastructures toward seamless, autonomous energy transfer solutions. This growth is underpinned by the aggressive electrification of transportation, the pursuit of enhanced user convenience, and the necessary integration of charging systems into smart city architectures. As the adoption of electric vehicles matures, the limitations of physical connectors—including mechanical wear, weather-related vulnerabilities, and the manual effort required—are driving manufacturers and municipalities to invest in inductive and capacitive charging technologies. The market is transitioning from niche pilot projects into large-scale commercial deployments, supported by rigorous international standards that ensure interoperability across different vehicle models and charging pads.
The technical evolution of resonance-based charging has significantly narrowed the efficiency gap between wired and wireless systems, with modern solutions achieving over 90% grid-to-battery efficiency. Furthermore, the development of dynamic wireless charging, which allows vehicles to charge while in motion, is gaining traction as a viable solution to range anxiety and the need for smaller, more cost-effective battery packs. This structural shift is expected to be most prominent in the commercial sector, where transit buses and heavy-duty logistics vehicles can utilize frequent stops or dedicated charging lanes to maintain operational uptime without manual intervention.
Key Wireless Electric Vehicle Charging Market Trends & Insights
The market is currently witnessing a confluence of technological breakthroughs and strategic collaborations aimed at standardizing the wireless charging experience. Stakeholders are focusing on the harmonization of magnetic resonance technology to allow cross-brand compatibility, which is crucial for public charging infrastructure. Regional analysis suggests that while North America leads in initial technology development, the Asia-Pacific region is poised to dominate in terms of volume and implementation due to massive government subsidies and the rapid expansion of EV fleets in China. Additionally, the integration of wireless charging with autonomous driving technologies is a critical trend; as vehicles become capable of self-parking, the need for a system that can automatically initiate charging without human presence becomes a functional necessity rather than a luxury. Competitive benchmarking indicates a heavy emphasis on "Foreign Object Detection" (FOD) and "Living Object Detection" (LOD) systems to ensure safety and regulatory compliance in domestic and public environments.
- Largest Region: Europe currently holds the largest market share due to early adoption of high-efficiency standards and extensive pilot projects in Germany, France, and the UK.
- Fastest Growing Region: Asia-Pacific is the fastest-growing region, driven by the massive automotive manufacturing base in China and South Korea and government mandates for green mobility.
- Largest Segment by Power: The 11 kW to 50 kW segment is currently the largest by share, catering to the primary demand from the passenger car segment for overnight residential charging.
- Leading Technology: Inductive charging remains the dominant technology, though Magnetic Resonance is gaining ground for its higher spatial freedom and misalignment tolerance.
- Key Market Driver: The emergence of Autonomous EVs is the primary driver necessitating the hands-free charging capabilities provided by wireless systems.
Key Takeaways Wireless Electric Vehicle Charging Market Size & Forecast
The trajectory of the wireless EV charging market is characterized by a move toward high-power density and dynamic infrastructure. Market forecasts indicate that by 2034, the infrastructure for dynamic charging on highways will begin to move from the testing phase to commercial reality, significantly impacting the long-haul logistics sector. Analysts highlight that the cost-per-unit for wireless pads is expected to decrease as manufacturing scales and semiconductor components like Silicon Carbide (SiC) and Gallium Nitride (GaN) become more prevalent in power electronics, enhancing heat dissipation and efficiency. The shift from private residential sales to public and fleet-based infrastructure will likely redefine the revenue models for utilities and service providers, turning charging into a passive, background activity integrated into daily commutes and logistics operations.
- Infrastructure Dominance: Public infrastructure projects in smart cities will account for over 60% of the total market value by 2030 as governments look to reduce street clutter from cables.
- Efficiency Benchmarks: Next-generation systems are expected to reach 93-95% efficiency, effectively matching the performance of Level 2 AC plug-in chargers.
- Commercial Vehicle Lead: Electric buses and taxis are the leading early adopters, utilizing "snack charging" at stops to extend daily range without increasing battery size.
- Standardization Milestone: The universal adoption of SAE J2954 standards is the single most important factor in reducing consumer uncertainty and driving OEM integration.
- Cost Reduction: A projected 45% reduction in installation costs over the next decade will make wireless charging a standard feature in premium and mid-range electric vehicles.
Wireless Electric Vehicle Charging Market Drivers Analysis
The primary catalyst for the wireless EV charging market is the urgent need for a more convenient and automated user experience. As the consumer base for EVs shifts from early adopters to the mass market, the demand for "frictionless" charging—where the driver simply parks over a pad—is intensifying. Additionally, the rapid development of self-driving vehicles creates a technical requirement for charging systems that do not require human hands. Government incentives across the EU and North America targeting the reduction of urban carbon footprints are also forcing the expansion of charging networks, where wireless solutions offer a more aesthetic and durable alternative to heavy cables and pedestals that are prone to vandalism and weather damage.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Autonomous Vehicle Integration | +12.5% | United States, Germany | 2026 - 2034 |
| Public Transit Electrification | +9.8% | China, Scandinavia | 2025 - 2030 |
| Frictionless User Experience | +8.4% | Global | 2025 - 2034 |
| Smart City Infrastructure Growth | +7.2% | South Korea, Japan | 2027 - 2034 |
Wireless Electric Vehicle Charging Market Restraints Analysis
Despite the high growth potential, the market faces significant hurdles, primarily related to the high initial capital expenditure required for both the vehicle-side hardware and the ground-side pads. The installation of wireless charging requires significant civil engineering work, especially for dynamic charging lanes, which can be cost-prohibitive for cash-strapped municipalities. Furthermore, there are ongoing concerns regarding the electromagnetic compatibility (EMC) of high-power wireless systems with other electronic devices and the potential health concerns of long-term exposure to magnetic fields, necessitating expensive shielding and safety sensors that add to the total cost.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Installation Costs | -6.5% | Latin America, India | 2025 - 2029 |
| Energy Loss & Efficiency Gaps | -4.2% | Global | Short Term |
| Electromagnetic Interference Concerns | -3.1% | European Union | 2025 - 2028 |
Wireless Electric Vehicle Charging Market Opportunities Analysis
The most lucrative opportunity lies in the development of Dynamic Wireless Power Transfer (DWPT) systems. By embedding charging coils into roadways, EVs can be charged while driving, which could theoretically allow for infinite range and the use of much smaller batteries, drastically reducing the price of EVs. Another significant opportunity is the integration of wireless charging with Vehicle-to-Grid (V2G) technology. Wireless pads can act as bi-directional energy hubs, allowing EVs to discharge power back into the grid or a home during peak demand periods without the user needing to remember to plug the vehicle in, thus maximizing the utility of the vehicle’s battery as a distributed energy storage asset.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Dynamic Charging Roads (DWPT) | +15.2% | Sweden, Israel, USA | 2028 - 2034 |
| Bi-directional Wireless V2G | +6.8% | Japan, Netherlands | 2027 - 2034 |
| Premium Fleet Partnerships | +5.5% | Global (Luxury Segment) | 2025 - 2034 |
Wireless Electric Vehicle Charging Market Challenges Impact Analysis
Technical challenges remain a bottleneck, particularly the issue of parking alignment. While magnetic resonance allows for some leeway, significant misalignment between the vehicle and ground pad still leads to substantial efficiency drops. Automated parking systems (APA) help solve this, but their integration into lower-end vehicle segments is slow. Additionally, the lack of a standardized global regulatory framework for billing and energy accounting in wireless public spaces complicates the commercialization for third-party charging station operators. Managing heat dissipation during high-power fast charging (above 50 kW) also requires advanced thermal management systems, which increases the complexity and weight of the onboard vehicle equipment.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Interoperability Standards | -5.8% | Global | 2025 - 2027 |
| Thermal Management in High-Power Units | -4.4% | All high-temp regions | 2026 - 2030 |
| Positioning & Alignment Precision | -3.9% | Global | 2025 - 2034 |
Wireless Electric Vehicle Charging Market - Updated Report Scope
The report provides a deep-dive analysis into the global wireless EV charging landscape, covering the entire value chain from semiconductor providers and coil manufacturers to automotive OEMs and infrastructure developers. It examines the market through various lenses, including technology type (Inductive, Magnetic Resonance, Capacitive), installation type (Stationary vs. Dynamic), and application (Residential, Commercial, Public). The scope also includes a detailed breakdown of power levels, ranging from slow chargers for home use to ultra-fast systems for commercial heavy-duty vehicles, and provides a 10-year forecast period to help stakeholders understand long-term infrastructure shifts.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 950.4 Million |
| Market Forecast in 2034 | USD 18,450.8 Million |
| Growth Rate | 41.2% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Witricity Corporation, Plugless Power (Evatran), Qualcomm (Halo), Wave (Ideanomics), Momentum Dynamics, TDK Corporation, HELLA GmbH, Continental AG, Siemens AG, ZTE Corporation, Toshiba Corporation, Nidec Corporation, Electreon, Bombardier Primove, Mojo Mobility, InductEV, BorgWarner Inc., Renesas Electronics |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The wireless EV charging market is segmented based on technology, power delivery, and vehicle application to reflect the diverse operational requirements of the automotive industry. Inductive charging currently dominates the market because of its proven reliability and high efficiency in stationary settings. However, the commercial vehicle segment is increasingly favoring higher power outputs (above 50 kW) to minimize downtime for city buses and delivery vans. Dynamic charging, although currently the smallest segment by revenue, is expected to see the highest growth rate toward the end of the forecast period as road infrastructure projects in Europe and Asia begin to incorporate embedded coils into major transit corridors.
- By Technology: Inductive charging is the primary choice for residential applications, while Magnetic Resonance is preferred for its tolerance to ground clearance variations in SUVs and trucks.
- By Power Supply: The 11 kW to 50 kW range is becoming the industry standard for home and workplace charging, striking a balance between charging speed and thermal efficiency.
- By Vehicle Type: Passenger cars remain the highest volume segment, but commercial vehicles (buses/trucks) offer the highest revenue-per-unit due to the complexity of high-power wireless systems.
- By Installation: Stationary charging pads for garages and parking lots are the current market mainstays, with dynamic charging representing the future of highway infrastructure.
- By Component: Onboard vehicle pads and power electronics represent the most critical high-margin components for automotive suppliers.
Regional Highlights
- Europe: The region is the global leader in wireless charging implementation, with countries like Germany and Sweden hosting extensive dynamic charging road trials. Stringent CO2 targets and high EV adoption rates drive the demand for public wireless infrastructure.
- North America: Driven by Silicon Valley-based tech giants and automotive OEMs like Tesla and Ford, this region leads in R&D and the development of magnetic resonance technology. The US government’s focus on autonomous vehicle regulation is a key catalyst.
- Asia-Pacific: China is the dominant player in terms of scale, with massive investments in wireless charging for electric buses. South Korea and Japan are leaders in component manufacturing and standardization, focusing on high-density urban solutions.
- Middle East & Africa: Emerging interest from oil-rich nations like Saudi Arabia and the UAE to build futuristic smart cities (e.g., NEOM) provides a niche but high-value market for premium wireless charging installations.
- Latin America: While currently in the early stages, Brazil and Chile are exploring wireless charging for public transport systems as part of their urban modernization programs.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Wireless Electric Vehicle Charging Market.- Witricity Corporation
- Plugless Power (Evatran Group)
- Wave (Ideanomics Company)
- Momentum Dynamics
- TDK Corporation
- HELLA GmbH & Co. KGaA
- Continental AG
- Siemens AG
- ZTE Corporation
- Toshiba Corporation
- Nidec Corporation
- Electreon
- Bombardier Primove
- Mojo Mobility
- InductEV
- BorgWarner Inc.
- Renesas Electronics
- DAIHEN Corporation
- Integrated Device Technology (IDT)
- Aptiv PLC
Frequently Asked Questions
How efficient is wireless EV charging compared to traditional plug-in chargers?
Modern wireless EV charging systems, particularly those using magnetic resonance, achieve efficiencies of 90% to 93%. This is nearly equivalent to the 94-95% efficiency typical of wired Level 2 AC chargers. The small loss is generally attributed to air-gap transmission but is being minimized through better coil alignment and high-frequency power electronics.
Is wireless charging safe for people and pets?
Yes, wireless charging systems are designed with advanced safety features. They include Foreign Object Detection (FOD) to identify metal objects that might heat up and Living Object Detection (LOD) to shut down the system if a pet or person enters the magnetic field. They also comply with strict ICNIRP guidelines for electromagnetic exposure.
Can any electric vehicle use a wireless charger?
A vehicle must be equipped with an onboard receiving pad and compatible power electronics to use a wireless charger. While most current EVs are not factory-equipped, many OEMs are beginning to offer it as an option, and companies like Plugless Power provide aftermarket retrofitting kits for popular models like the Tesla Model S and Nissan Leaf.
What is dynamic wireless charging and when will it be available?
Dynamic wireless charging involves embedding charging coils under the surface of the road, allowing EVs to charge while in motion. Currently, it is in the pilot and demonstration phase in countries like Sweden, Israel, and the USA. Commercial-scale deployment on major highways is expected to begin between 2028 and 2032.
How does weather affect the performance of wireless charging pads?
Wireless charging pads are typically rated IP67 or higher, meaning they are completely sealed and waterproof. Unlike plug-in chargers, they have no exposed metal contacts, making them safer and more reliable in snow, rain, or ice. The magnetic field passes through snow and water with virtually no loss in efficiency.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
