Water Borne Resins Market
Water Borne Resins Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711724 | Published On : November 13, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Water Borne Resins Market Size
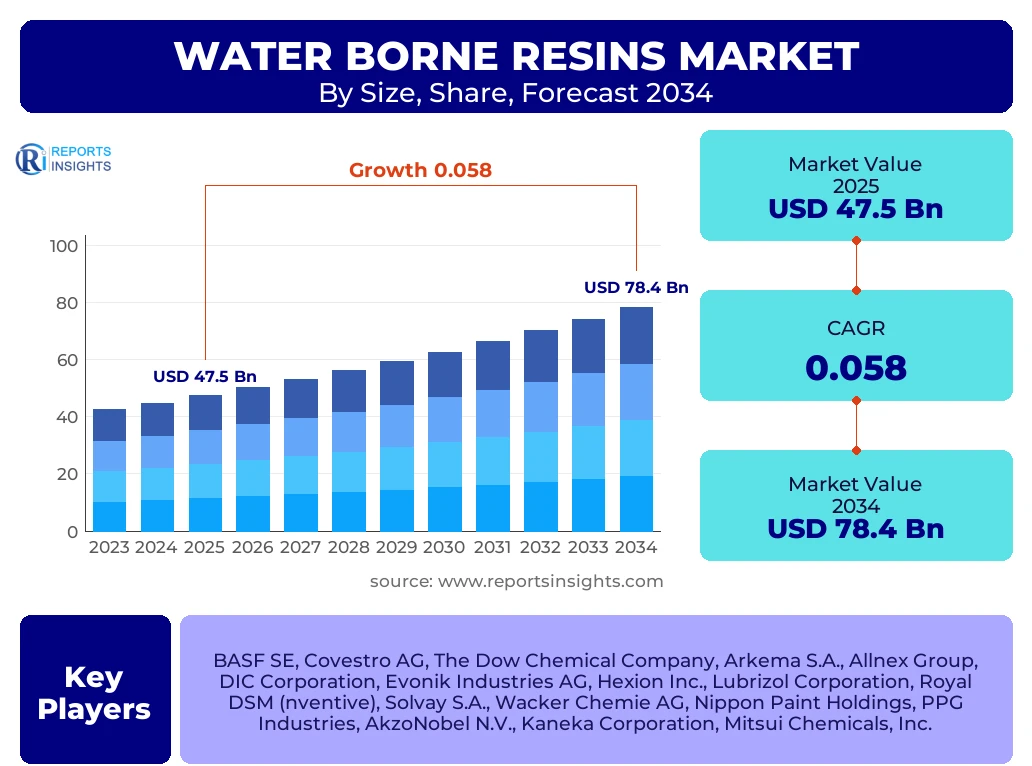
According to Reports Insights Consulting Pvt Ltd, The Water Borne Resins Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2025 and 2034. The market is estimated at USD 50.2 Billion in 2026 and is projected to reach USD 78.4 Billion by the end of the forecast period in 2034.
Key Water Borne Resins Market Trends & Insights
The global shift toward sustainable chemistry and the rigorous implementation of Volatile Organic Compound (VOC) regulations are fundamentally reshaping the water-borne resins landscape. Market intelligence suggests that industrial manufacturers are moving beyond simple compliance, treating water-based systems as a primary platform for innovation in high-performance coatings and adhesives. The integration of hybrid resin technologies—specifically acrylic-polyurethane hybrids—is gaining traction as users seek the durability of solvent-based systems without the associated environmental footprint. Furthermore, the rapid expansion of the construction and automotive sectors in emerging economies is driving a localized but high-volume demand for low-odor, quick-drying resin formulations.
- Largest Region: Asia-Pacific (APAC) remains the dominant force, accounting for over 40% of the global market share, fueled by massive infrastructure projects and automotive manufacturing hubs in China and India.
- Fastest Growing Region: Southeast Asia and parts of Latin America are exhibiting the highest growth rates due to rapid urbanization and the adoption of greener building standards.
- Largest Segment by Type: Acrylic resins lead the market in terms of volume and value, prized for their versatility, cost-effectiveness, and excellent UV resistance.
- Largest Segment by Application: Architectural coatings represent the primary application area, driven by the residential housing boom and the DIY home improvement trend.
Key Takeaways Water Borne Resins Market Size & Forecast
The forecast period is characterized by a definitive pivot toward bio-based feedstocks and circular economy principles. As global supply chains stabilize, the emphasis is shifting toward performance parity with solvent-borne counterparts, particularly in aggressive environments like marine and heavy-duty industrial settings. Market participants are increasingly investing in research and development to overcome traditional limitations such as sensitivity to humidity and longer drying times under specific climatic conditions.
- Leading Country: China stands as the single largest consumer and producer, dictated by the government’s stringent Blue Sky initiatives and industrial upgrade policies.
- Performance Parity: Recent breakthroughs in cross-linking technologies have allowed water-borne epoxies and polyurethanes to match the chemical resistance of traditional solvent-based systems.
- Regulatory Influence: REACH in Europe and the EPA’s Clean Air Act in the United States continue to be the primary structural drivers for market migration.
- Sustainability Premium: While initial costs can be higher, the total cost of ownership is decreasing as insurance and hazardous material handling costs for solvent-based alternatives rise.
Water Borne Resins Market Drivers Analysis
The primary catalyst for market expansion is the global legislative crackdown on hazardous air pollutants and VOC emissions. Regulatory bodies worldwide are tightening the permissible limits for solvent use in paints, coatings, and inks, forcing a mandatory transition to water-dispersed systems. Additionally, the escalating consumer preference for eco-friendly and low-odor products in the home improvement and architectural sectors provides a strong pull-factor for manufacturers to innovate within the water-borne space.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Environmental Regulations (VOC Limits) | +2.1% | European Union & North America | 2025 - 2034 |
| Infrastructure Expansion in Emerging Economies | +1.8% | China, India, Indonesia | 2025 - 2030 |
| Growth in Automotive OEM Coatings | +1.2% | Germany, Japan, South Korea | 2027 - 2034 |
| Rising Demand for Bio-based Water-borne Resins | +0.7% | Global | 2028 - 2034 |
Water Borne Resins Market Restraints Analysis
Despite the positive trajectory, the market faces significant hurdles regarding the inherent physical properties of water as a carrier. High humidity levels and low temperatures can severely impede the drying and film-formation process, making these resins less versatile in certain geographic locations. Furthermore, the specialized storage requirements to prevent freezing or bacterial growth add layers of complexity and cost to the logistics chain that solvent-borne products do not encounter.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Sensitivity to Climatic Conditions (Humidity/Temp) | -0.9% | Tropical Regions (SEA, Brazil) | Continuous |
| Higher Raw Material Costs for Specialized Additives | -0.6% | Global | 2025 - 2029 |
Water Borne Resins Market Opportunities Analysis
The development of smart and functional water-borne coatings presents a lucrative frontier for market players. Innovations such as self-healing coatings, anti-microbial surfaces, and hyper-durable industrial finishes are opening doors in the aerospace and healthcare sectors. Additionally, the packaging industry’s shift away from plastic-based films toward paper-based barriers provides a massive opportunity for water-borne barrier coatings that are both recyclable and compostable.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Nanotechnology Integration | +1.5% | USA, Germany, China | 2026 - 2034 |
| Sustainability-linked Packaging Solutions | +1.3% | Global | 2025 - 2034 |
Water Borne Resins Market Challenges Impact Analysis
The complexity of the formulation remains a significant technical challenge. Water-borne systems require a sophisticated balance of surfactants, defoamers, and thickeners, which can sometimes lead to issues like foaming, cratering, or poor substrate wetting. Moreover, the transition for small and medium-sized enterprises (SMEs) to switch production lines from solvent-borne to water-borne often requires substantial capital investment in stainless steel equipment to prevent corrosion, which can slow down market penetration in developing regions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Technical Performance Gaps in Marine Environments | -0.5% | Coastal Regions Global | 2025 - 2030 |
| Capital Intensive Infrastructure Upgrades for SMEs | -0.4% | India, Latin America | 2025 - 2028 |
Water Borne Resins Market - Updated Report Scope
This report provides a granular analysis of the global water-borne resins ecosystem, covering the technical evolution of polymer dispersions and their commercial adoption across diverse industrial verticals. The scope encompasses detailed historical data, current market valuation, and a robust ten-year forecast, emphasizing the transition from conventional chemical building blocks to sustainable alternatives.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 47.5 Billion |
| Market Forecast in 2034 | USD 78.4 Billion |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Covestro AG, The Dow Chemical Company, Arkema S.A., Allnex Group, DIC Corporation, Evonik Industries AG, Hexion Inc., Lubrizol Corporation, Royal DSM (nventive), Solvay S.A., Wacker Chemie AG, Nippon Paint Holdings, PPG Industries, AkzoNobel N.V., Kaneka Corporation, Mitsui Chemicals, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The water-borne resins market is characterized by its high degree of specialization across different polymer types. While acrylics dominate the volume share due to their widespread use in decorative paints, high-performance resins like Water-borne Polyurethane Dispersions (PUDs) are seeing rapid growth in the automotive and textile sectors where durability and flexibility are paramount. The market is also witnessing a resurgence in alkyd resins, specifically water-reducible alkyds, as they provide the traditional "look and feel" of oil-based paints with significantly lower emissions.
- Acrylic Resins: The most widely used segment, dominant in architectural and decorative coatings due to cost-efficiency and color retention.
- Polyurethane Dispersions (PUDs): Leading the high-growth curve in automotive, leather, and premium wood coatings owing to superior abrasion resistance.
- Epoxy Resins: Essential for industrial anti-corrosive primers and heavy-duty floor coatings, particularly in the construction and marine sectors.
- Alkyd Resins: Re-engineered for water-based delivery, these are vital for the DIY wood care and metal coating markets.
- Vinyl Acetate Ethylene (VAE): Predominantly used in the adhesives and sealants sector for packaging and construction.
Regional Highlights
- Asia-Pacific (APAC): The largest market by value and volume. China's "Coal-to-Gas" and "Blue Sky" policies have accelerated the industrial shift to water-borne systems. India’s housing for all initiatives and infrastructure projects further bolster demand.
- Europe: The most mature market with the highest regulatory standards. Demand is driven by innovation in bio-based resins and high-performance industrial coatings in Germany, France, and Italy.
- North America: Significant growth in the automotive and aerospace sectors. The U.S. market is increasingly focused on high-solids water-borne systems to maximize efficiency and minimize environmental impact.
- Latin America: Brazil and Mexico are emerging as key hubs for automotive manufacturing, driving the demand for specialized water-borne OEM coatings.
- Middle East & Africa: Growth is concentrated in the construction sector, particularly in the GCC countries, though climatic challenges (extreme heat) require specialized resin formulations.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Water Borne Resins Market.
- BASF SE
- Covestro AG
- The Dow Chemical Company
- Arkema S.A.
- Allnex Group
- DIC Corporation
- Evonik Industries AG
- Hexion Inc.
- Lubrizol Corporation
- Royal DSM (Part of dsm-firmenich)
- Solvay S.A.
- Wacker Chemie AG
- Nippon Paint Holdings Co., Ltd.
- PPG Industries, Inc.
- AkzoNobel N.V.
- Kaneka Corporation
- Mitsui Chemicals, Inc.
- Huntsman Corporation
- Sumitomo Bakelite Co., Ltd.
- Olin Corporation
Frequently Asked Questions
Analyze common user questions about the Water Borne Resins market and generate a concise list of summarized FAQs reflecting key topics and concerns.
What are the primary advantages of water-borne resins over solvent-borne resins?
Water-borne resins significantly reduce Volatile Organic Compound (VOC) emissions, offering a lower environmental impact, improved worker safety, and reduced flammability. They are easier to clean up and often meet stringent government air quality regulations that solvent-based systems cannot.
Which industry is the largest consumer of water-borne resins?
The architectural and construction industry is the largest consumer, primarily using water-borne acrylic resins for interior and exterior wall paints due to their low odor, fast drying times, and ease of application.
How do climate conditions affect the application of water-borne coatings?
High humidity can slow the evaporation of water, leading to longer drying times and potential film defects. Conversely, very low temperatures can prevent proper coalescence. Manufacturers address this by adding specialized coalescents and additives to ensure performance across various climates.
What are the emerging trends in water-borne resin technology?
Key trends include the development of 2K (two-component) water-borne polyurethanes for high-durability industrial use, the rise of bio-renewable feedstocks to further lower carbon footprints, and the integration of nanostructures for self-cleaning or anti-corrosive properties.
Is the cost of water-borne resins higher than traditional alternatives?
While the initial price per gallon can sometimes be higher due to the complexity of the formulation and the cost of specialized additives, the overall "applied cost" is often competitive when considering lower insurance premiums, reduced hazardous waste disposal fees, and less stringent ventilation requirements.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
