Waste Energy Market
Waste Energy Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711434 | Published On : November 01, 2026 |
Format : 


 | Author : Seema Bhateja
Waste Energy Market Size
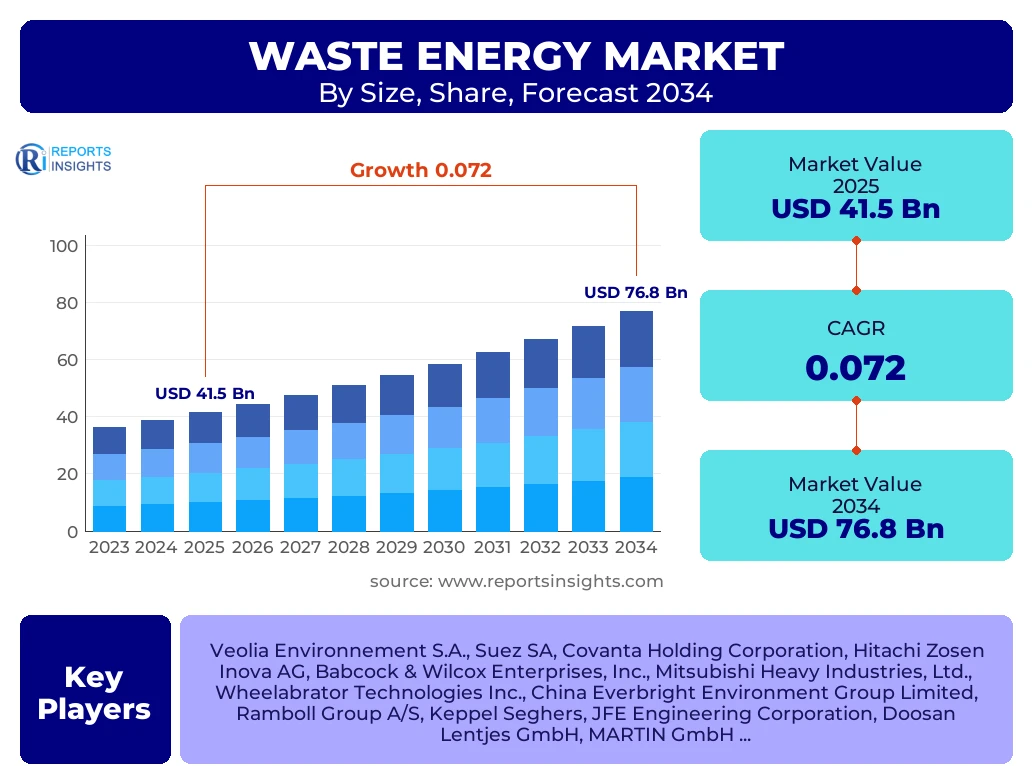
According to Reports Insights Consulting Pvt Ltd, The Waste Energy Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.2% between 2025 and 2034. The market is estimated at USD 44.2 Billion in 2026 and is projected to reach USD 76.8 Billion by the end of the forecast period in 2034.
The Waste Energy market, commonly referred to as Waste-to-Energy (WtE), represents a critical intersection of waste management and renewable energy production. As global municipal solid waste volumes continue to surge alongside rapid urbanization, the transition from traditional landfilling to energy recovery has become a strategic priority for municipal authorities and private energy developers. The market's expansion is fundamentally underpinned by the dual necessity of reducing the environmental footprint of waste and securing sustainable, baseload power sources that can complement intermittent renewables like solar and wind.
The technical evolution within the sector has seen a shift from basic mass-burn incineration toward more sophisticated thermal and biological conversion technologies. Modern facilities are increasingly integrated with Carbon Capture and Storage (CCS) systems and advanced flue-gas cleaning technologies to meet stringent emission standards. Furthermore, the integration of circular economy principles is redefining waste not as a liability, but as a high-value feedstock for generating electricity, district heating, and even synthetic fuels, thereby driving long-term investment across both developed and emerging economies.
Key Waste Energy Market Trends & Insights
The global Waste Energy landscape is undergoing a significant transformation driven by the integration of digital twins and AI-driven sorting mechanisms that optimize the calorific value of feedstock. Analysis of regional inquiries indicates a massive pivot toward Asia-Pacific as the primary engine of volume growth, while European markets are focusing on the deep decarbonization of existing plants. Competitive benchmarking shows that leading players are diversifying their portfolios to include "Waste-to-Hydrogen" and "Waste-to-Fuel" pathways, reflecting a broader trend of cross-industry collaboration between waste management firms and the petrochemical sector.
- Largest Region: Europe currently maintains the largest market share, bolstered by the EU Landfill Directive and established district heating networks.
- Fastest Growing Region: Asia-Pacific is the fastest-growing region, fueled by massive capacity expansions in China, India, and Southeast Asia to manage skyrocketing municipal waste.
- Largest Segment: Thermal technology, specifically incineration, remains the dominant segment in terms of revenue share due to its proven scalability and efficiency in volume reduction.
- Emerging Trend: The adoption of "Advanced Thermal Treatment" (ATT) such as gasification and pyrolysis is gaining momentum for processing hazardous and industrial waste.
- Strategic Focus: Implementation of high-efficiency flue gas cleaning systems to comply with tightening global NOx and dioxin emission standards.
Key Takeaways Waste Energy Market Size & Forecast
The trajectory of the Waste Energy market through 2034 suggests a robust transition toward high-efficiency recovery systems that prioritize environmental compliance and resource recovery. Stakeholders are increasingly focusing on the bankability of WtE projects in emerging markets, where public-private partnerships (PPPs) are becoming the standard model for infrastructure development. The forecast indicates that while incineration continues to lead, the biological segment (anaerobic digestion) is carving out a significant niche in the processing of organic and agricultural waste streams.
- Market Leadership: China is the leading country in terms of installed capacity, driven by aggressive national waste management targets and subsidized feed-in tariffs.
- Sustainability Impact: WtE plants are projected to play a vital role in achieving "Net Zero" targets by diverting organic waste from landfills, thus preventing significant methane emissions.
- Technological Convergence: The convergence of WtE with district heating systems in Northern and Eastern Europe is a primary driver for high energy recovery efficiency ratings.
- Investment Climate: Institutional investors are showing increased interest in WtE as a "green asset" class, provided projects demonstrate high environmental, social, and governance (ESG) compliance.
- Policy Influence: Carbon pricing and landfill taxes are the most significant economic levers accelerating the transition from disposal to energy recovery globally.
Waste Energy Market Drivers Analysis
The primary catalysts for the Waste Energy market include the critical shortage of landfill space in metropolitan areas and the global mandate to diversify energy mixes. Governments are increasingly viewing waste as a domestic energy resource that enhances energy security by reducing reliance on imported fossil fuels. Additionally, the rising calorific value of municipal waste in developing nations, due to changing consumption patterns, has made energy recovery more economically viable than ever before.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Depletion of Landfill Capacities | +2.1% | Global (High in APAC and Western Europe) | 2025 - 2034 |
| Stringent Government Emission Norms | +1.5% | European Union, North America | 2026 - 2030 |
| Rising Demand for Renewable Baseload Power | +1.8% | Japan, South Korea, Germany | 2025 - 2034 |
| Circular Economy Policy Frameworks | +1.3% | China, UK, Scandinavia | 2027 - 2034 |
Waste Energy Market Restraints Analysis
Despite the growth, the market faces hurdles such as high initial capital expenditure (CAPEX) for state-of-the-art facilities and public opposition related to perceived environmental risks. The complexity of managing heterogeneous waste streams also poses operational challenges, requiring sophisticated pre-treatment and sorting facilities that can strain the project's overall financial feasibility.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Investment and Operational Costs | -1.2% | Developing Economies (Africa, Latin America) | 2025 - 2029 |
| Public "NIMBY" (Not In My Backyard) Sentiments | -0.8% | USA, Australia, UK | 2025 - 2034 |
| Fluctuating Feedstock Quality and Supply | -0.5% | Global | 2026 - 2030 |
Waste Energy Market Opportunities Analysis
The integration of WtE facilities with Green Hydrogen production represents a frontier opportunity for the industry. By utilizing the electricity and heat generated from waste to power electrolyzers, companies can produce carbon-neutral hydrogen. Furthermore, the recovery of precious metals and minerals from incinerator bottom ash (IBA) is emerging as a lucrative secondary revenue stream that aligns perfectly with resource recovery goals.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Waste-to-Hydrogen Technology Integration | +1.9% | Japan, Germany, USA | 2028 - 2034 |
| Carbon Capture, Utilization, and Storage (CCUS) | +1.4% | Norway, Netherlands, UK | 2027 - 2034 |
| Bottom Ash Metal Recovery Technologies | +0.9% | Global | 2025 - 2034 |
Waste Energy Market Challenges Impact Analysis
Market volatility in energy prices can significantly affect the revenue stability of WtE plants, particularly those without long-term Power Purchase Agreements (PPAs). Additionally, the competition with recycling initiatives for high-calorific waste like plastics and paper poses a strategic challenge, forcing WtE operators to adapt to a lower-calorific "residual" waste stream as circularity matures.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition with Increasing Recycling Rates | -0.7% | EU-27 Countries | 2025 - 2034 |
| Stringent Regulatory Compliance for Air Emissions | -0.6% | USA, China, South Korea | 2026 - 2031 |
Waste Energy Market - Updated Report Scope
This report provides a comprehensive examination of the global waste-to-energy ecosystem, encompassing technological advancements, regulatory shifts, and economic feasibility. It offers granular insights into the competitive landscape, project pipelines, and the integration of digital technologies in waste management. The scope includes a detailed analysis of municipal, industrial, and hazardous waste streams and their conversion into various energy forms including electricity, steam, and transport fuels.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 41.5 Billion |
| Market Forecast in 2034 | USD 76.8 Billion |
| Growth Rate | 7.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Veolia Environnement S.A., Suez SA, Covanta Holding Corporation, Hitachi Zosen Inova AG, Babcock & Wilcox Enterprises, Inc., Mitsubishi Heavy Industries, Ltd., Wheelabrator Technologies Inc., China Everbright Environment Group Limited, Ramboll Group A/S, Keppel Seghers, JFE Engineering Corporation, Doosan Lentjes GmbH, MARTIN GmbH, Steinmüller Babcock Environment GmbH, Viridor Limited, Biffa plc, EEW Energy from Waste GmbH, Abu Dhabi National Energy Company (TAQA). |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Waste Energy market is segmented primarily by technology, with thermal conversion remaining the cornerstone of the industry due to its ability to handle large volumes of non-recyclable waste. Incineration leads this segment, but gasification and pyrolysis are gaining traction for their higher efficiency and lower emission profiles. The biological segment, led by anaerobic digestion, is witnessing rapid growth in regions with high organic waste components, such as agricultural zones and food-processing hubs. Segmentation by application reveals a strong move toward Combined Heat and Power (CHP) configurations, which maximize the energy utilization rate from the feedstock.
- By Technology: Thermal (Incineration, Pyrolysis, Gasification), Biological (Anaerobic Digestion), Physical (RDF/SRF).
- By Waste Type: Municipal Solid Waste (MSW), Industrial Waste, Agricultural Waste, Hazardous & Medical Waste.
- By Application: Electricity, District Heating, Combined Heat and Power (CHP), Transport Fuel/Syngas.
- By Plant Capacity: Small-Scale (<10 MW), Medium-Scale (10-50 MW), Large-Scale (>50 MW).
Regional Highlights
- Europe: The largest market share holder, dominated by Germany, France, and the Nordic countries, where district heating integration is standard.
- Asia-Pacific: The fastest-growing region, with China leading in new plant commissions and Japan focusing on high-tech thermal recovery.
- North America: Steady growth driven by state-level mandates in the US and Canada to reduce landfill reliance and modernize aging WtE infrastructure.
- Middle East: Emerging as a high-potential market with massive projects in the UAE and Saudi Arabia as part of their "Zero Waste to Landfill" initiatives.
- Latin America: Growing interest in Brazil and Mexico for MSW-to-electricity projects to address urban sanitation challenges.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Waste Energy Market.- Veolia Environnement S.A.
- Suez SA
- Covanta Holding Corporation
- Hitachi Zosen Inova AG
- Babcock & Wilcox Enterprises, Inc.
- Mitsubishi Heavy Industries, Ltd.
- Wheelabrator Technologies Inc.
- China Everbright Environment Group Limited
- Ramboll Group A/S
- Keppel Seghers
- JFE Engineering Corporation
- Doosan Lentjes GmbH
- MARTIN GmbH
- Steinmüller Babcock Environment GmbH
- Viridor Limited
- Biffa plc
- EEW Energy from Waste GmbH
- Abu Dhabi National Energy Company (TAQA)
- A2A S.p.A.
- Fortum Oyj
Frequently Asked Questions
What is the current global market size of Waste-to-Energy?
The market is valued at approximately USD 41.5 Billion in 2025 and is expected to grow steadily at a CAGR of 7.2% through 2034.
Which technology dominates the Waste Energy market?
Thermal technology, particularly incineration (mass-burn), remains the dominant technology due to its maturity, reliability, and capability to process large-scale municipal waste.
How does Waste-to-Energy contribute to climate goals?
WTE helps reduce greenhouse gas emissions by diverting waste from landfills—where it would produce methane—and by displacing fossil fuel-based electricity with energy recovered from waste.
What are the main challenges facing WtE project developers?
Key challenges include high upfront capital costs, the need for long-term feedstock guarantees, and navigating complex environmental regulations regarding air emissions.
Which region is expected to see the fastest growth by 2034?
The Asia-Pacific region is projected to be the fastest-growing market, driven by rapid urbanization and government-led waste management infrastructure expansions in China and India.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
