Used Semi Truck Market
Used Semi Truck Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711314 | Published On : October 26, 2026 |
Format : 


 | Author : Shamin Verma
Used Semi Truck Market Size
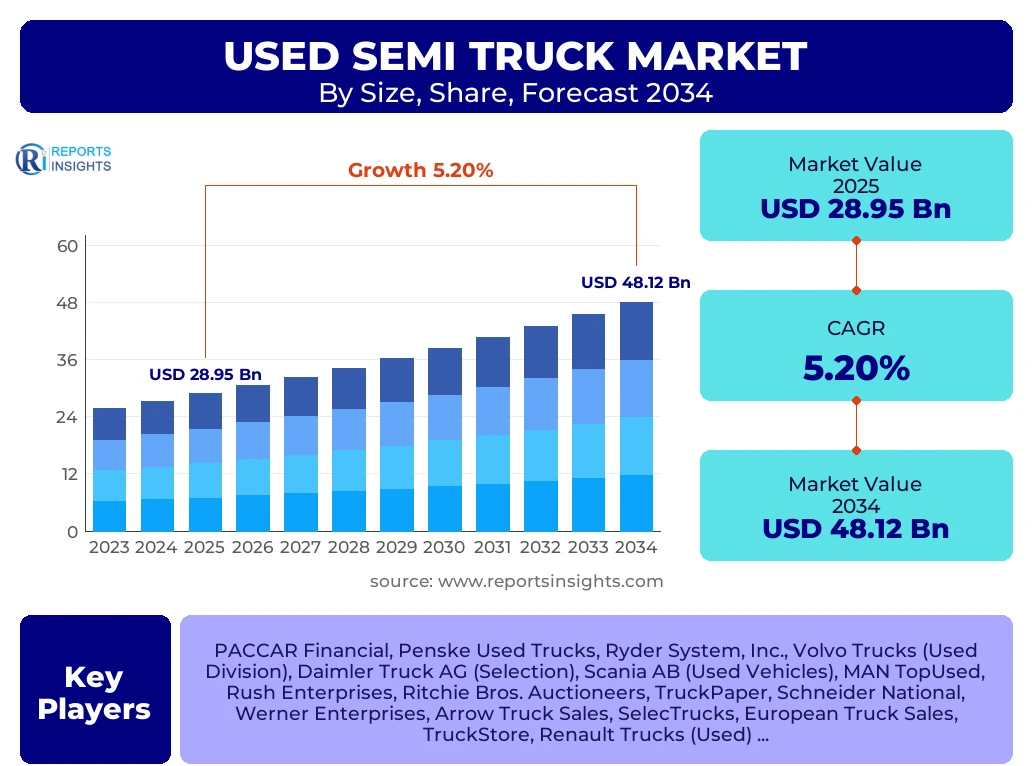
According to Reports Insights Consulting Pvt Ltd, The Used Semi Truck Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2025 and 2034. The market is estimated at USD 30.45 Billion in 2026 and is projected to reach USD 48.12 Billion by the end of the forecast period in 2034.
Key Used Semi Truck Market Trends & Insights
The global landscape for pre-owned heavy-duty vehicles is undergoing a significant transformation driven by the integration of digital sales platforms and the increasing demand for cost-effective logistics solutions. Industry analysis reveals that small to medium-sized enterprises (SMEs) are increasingly opting for used semi-trucks to bypass the high initial capital expenditure of new models while maintaining operational efficiency. Furthermore, the market is seeing a notable trend toward the professionalization of the used truck segment, with major manufacturers launching certified pre-owned (CPO) programs that offer warranties and inspection certifications similar to new vehicle standards. Competitive benchmarking indicates that companies leveraging telematics and predictive maintenance data in their used inventory are gaining a significant edge in buyer trust and resale value retention.
- Largest Region: North America remains the dominant market share holder, driven by a mature logistics infrastructure and a robust secondary sales ecosystem.
- Fastest Growing Region: Asia Pacific is anticipated to exhibit the highest CAGR due to rapid urbanization and the expansion of the e-commerce sector in emerging economies.
- Largest Segment by Class: Class 8 heavy-duty trucks account for the majority of the market share, necessitated by long-haul freight requirements.
- Leading Sales Channel: Independent dealers and specialized online marketplaces are the primary drivers of transaction volume.
Key Takeaways Used Semi Truck Market Size & Forecast
The used semi-truck market is characterized by its cyclical nature, often inversely related to the supply chain stability of new truck manufacturing. When lead times for new vehicles increase, the demand and pricing for late-model used trucks surge. Forecasts suggest that the market will stabilize as production capacity for new trucks normalizes, leading to a more consistent supply of high-quality trade-ins. Strategic insights indicate that the shift toward stricter emission standards, such as EPA 27 in the United States and Euro VII in Europe, will significantly impact the residual value of older diesel models while creating a niche for used alternative fuel vehicles.
- High Residual Value: Late-model trucks (3-5 years old) with low mileage are witnessing record-high resale values due to their balance of technology and cost.
- Digital Transformation: Online auction platforms and virtual showrooms have reduced geographical barriers, allowing for cross-border trade of used heavy assets.
- Fleet Modernization: Large logistics firms are shortening their replacement cycles, which is increasing the availability of well-maintained used inventory for secondary buyers.
- Infrastructure Impact: Investments in road networks in developing nations are directly correlating with the increased demand for used heavy-duty transport.
Used Semi Truck Market Drivers Analysis
The growth of the used semi-truck market is primarily fueled by the economic necessity for logistics providers to optimize their fleet costs amidst fluctuating fuel prices and rising labor costs. By acquiring used assets, companies can achieve a faster return on investment (ROI) and maintain liquidity for other operational expenses. The expansion of the global e-commerce industry, which demands a high volume of middle-mile and last-mile transport solutions, serves as a secondary but powerful catalyst for market expansion.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| E-commerce Growth | +1.8% | Global / China & USA | 2025 - 2034 |
| New Truck Price Inflation | +1.2% | North America & Europe | 2025 - 2030 |
| SME Fleet Expansion | +0.9% | India & Southeast Asia | 2026 - 2034 |
Used Semi Truck Market Restraints Analysis
One of the primary headwinds facing the used semi-truck market is the implementation of stringent environmental regulations. As cities and nations adopt zero-emission zones, older used trucks that do not meet modern standards face restricted access, thereby lowering their utility and resale value. Additionally, the rising cost of maintenance for aging fleets and the scarcity of specialized components for older models act as significant deterrents for potential buyers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Emission Norms | -1.4% | European Union / California (USA) | 2026 - 2034 |
| High Maintenance Costs | -0.8% | Developed Markets | 2025 - 2034 |
Used Semi Truck Market Opportunities Analysis
The market presents significant opportunities in the realm of refurbishment and technological retrofitting. There is a growing niche for companies that specialize in upgrading used trucks with modern telematics, safety sensors, and even fuel-efficient aerodynamic kits. Furthermore, the emerging market for used electric and hybrid trucks represents a frontier for early adopters as the first generation of green fleets begins to enter the secondary market towards the end of the decade.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Telematics Retrofitting | +1.5% | Global | 2026 - 2034 |
| Used EV Market Entry | +0.7% | Europe & North America | 2030 - 2034 |
Used Semi Truck Market Challenges Impact Analysis
The primary challenge for stakeholders is the volatility of the resale market, which is highly sensitive to macroeconomic shifts and interest rate changes. High interest rates make financing used equipment more expensive for small operators, potentially dampening demand. Furthermore, the lack of transparency in vehicle history and maintenance records in certain regions continues to be a barrier to the cross-border trade of used heavy vehicles.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Financing Constraints | -0.6% | Emerging Markets | 2025 - 2028 |
| Information Asymmetry | -0.4% | Global | 2025 - 2034 |
Used Semi Truck Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the pre-owned heavy and medium-duty truck market across five major geographic regions. It evaluates the impact of technological advancements, regulatory shifts, and economic indicators on market valuation. The study provides granular data on segmentation by vehicle class, propulsion type, and sales channel, offering a 360-degree view of the industry's trajectory through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 28.95 Billion |
| Market Forecast in 2034 | USD 48.12 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | PACCAR Financial, Penske Used Trucks, Ryder System, Inc., Volvo Trucks (Used Division), Daimler Truck AG (Selection), Scania AB (Used Vehicles), MAN TopUsed, Rush Enterprises, Ritchie Bros. Auctioneers, TruckPaper, Schneider National, Werner Enterprises, Arrow Truck Sales, SelecTrucks, European Truck Sales, TruckStore, Renault Trucks (Used), Iveco OK Trucks |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The used semi-truck market is segmented based on several critical factors that influence purchasing decisions and market value. The Class 8 segment continues to dominate the market due to its necessity in the global supply chain, while the propulsion segment is seeing a gradual diversification as alternative fuels gain traction in specific regional pockets.
- By Vehicle Class:
- Class 8: Heavy-duty trucks intended for long-haul freight; holds over 60% market share.
- Class 7: Medium-duty trucks for regional distribution.
- Class 6 & Below: Light to medium-duty vehicles for local delivery.
- By Fuel Type:
- Diesel: The traditional and most prevalent fuel source.
- Gasoline: Limited to lighter-duty semi-models.
- Alternative Fuels: Including LNG, CNG, and emerging Electric used inventory.
- By Sales Channel:
- Franchised Dealers: Offering manufacturer-backed warranties.
- Auctions: High-volume channels for fleet liquidations.
- Online Marketplaces: Rapidly growing due to ease of price comparison and global reach.
Regional Highlights
- North America: The largest market for used semi-trucks, characterized by high turnover rates among large carrier fleets and a robust demand for Class 8 trucks. The U.S. market is particularly influenced by freight rate volatility and environmental regulations in states like California.
- Asia Pacific: Expected to be the fastest-growing region. Rapid infrastructure development in India and South East Asia is driving the demand for used heavy machinery and transport vehicles. China is also seeing a surge in organized used truck platforms.
- Europe: A mature market focused on high-quality, low-emission used vehicles. The "TopUsed" and "Certified" programs are most successful here, with a strong emphasis on Euro VI compliant trucks.
- Latin America: Demand is primarily driven by the agricultural and mining sectors, with a preference for durable and easily maintainable older diesel models.
- Middle East & Africa: A growing market for imported used trucks from Europe and North America, supporting the logistics corridors in the GCC and developing African nations.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Used Semi Truck Market.- PACCAR Financial (Peterbilt/Kenworth)
- Penske Used Trucks
- Ryder System, Inc.
- Volvo Trucks (Used Division)
- Daimler Truck AG (Selection)
- Scania AB (Used Vehicles)
- MAN TopUsed
- Rush Enterprises
- Ritchie Bros. Auctioneers
- TruckPaper (Sandhills Global)
- Schneider National
- Werner Enterprises
- Arrow Truck Sales (Volvo Group)
- SelecTrucks (Daimler)
- European Truck Sales
- TruckStore
- Renault Trucks (Used)
- Iveco OK Trucks
- Mack Used Trucks
- Navistar (International Used Truck Centers)
Frequently Asked Questions
What is the current market valuation of the used semi truck market?
The market is estimated at approximately USD 28.95 Billion in 2025, with a projected growth trajectory reaching USD 48.12 Billion by 2034, driven by fleet expansion and e-commerce demands.
Which vehicle class dominates the used truck market?
Class 8 heavy-duty trucks are the dominant segment, accounting for over 60% of the market share, as they are essential for long-haul freight operations globally.
How are environmental regulations affecting the resale value of semi trucks?
Stricter emission standards are reducing the residual value of older diesel models (pre-2010), while increasing the demand for late-model units that comply with Euro VI or EPA standards.
Which region is expected to grow the fastest through 2034?
The Asia Pacific region is forecast to exhibit the fastest growth, fueled by rapid urbanization, infrastructure projects, and the maturation of the logistics sector in India and China.
What are the benefits of buying a Certified Pre-Owned (CPO) semi truck?
CPO trucks offer buyers reduced risk through rigorous multi-point inspections, manufacturer warranties, and often include detailed telematics and maintenance history records.
Author
S
Shamin Verma is a Senior Analyst Semiconductor and Electronics Research with over 7+ years of experience in the Semiconductor and Electronics Industry. She specializes in semiconductor market intelligence, electronics supply chain analysis, wafer fabrication trends, competitive benchmarking, demand forecasting, component pricing analysis, emerging technology assessment, integrated circuit market evaluation, and industry ecosystem research. Her expertise in translating complex market data into strategic insights enables organizations to make informed business decisions, identify high-growth opportunities, optimize operational planning, anticipate evolving technology trends, and strengthen their competitive positioning in the global semiconductor and electronics market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
