Tinea Pedis Treatment Market
Tinea Pedis Treatment Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711199 | Published On : October 16, 2026 |
Format : 


 | Author : Erika Grotto
Tinea Pedis Treatment Market Size
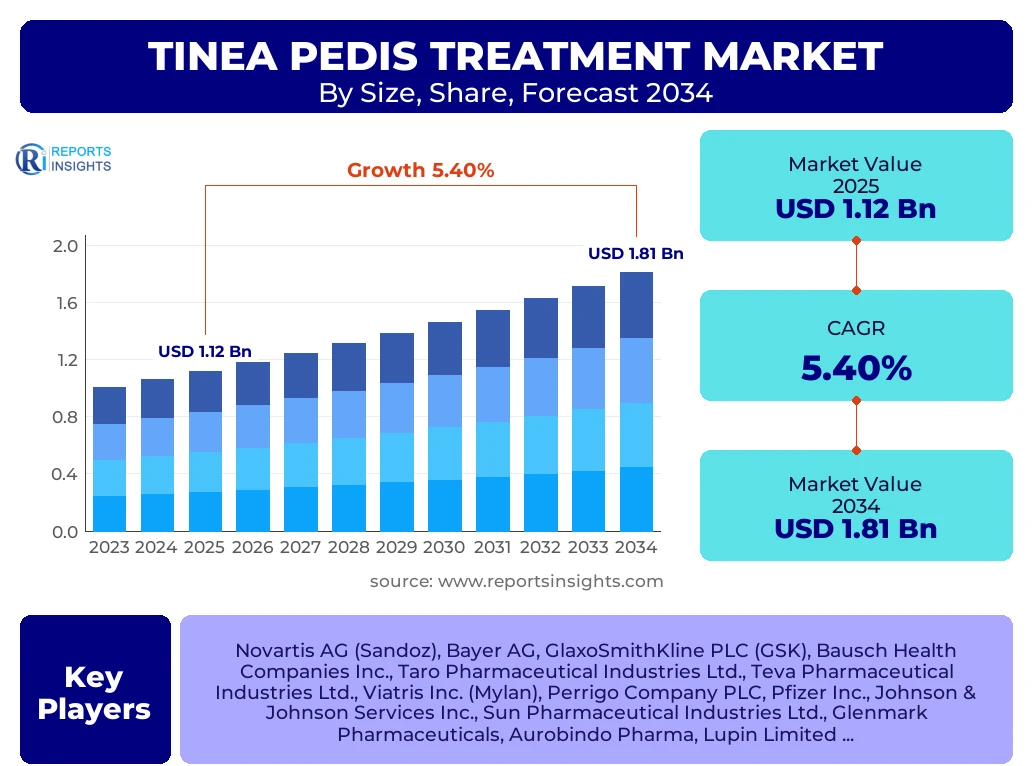
According to Reports Insights Consulting Pvt Ltd, The Tinea Pedis Treatment Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 1.12 Billion in 2025 and is projected to reach USD 1.81 Billion by the end of the forecast period in 2034.
Key Tinea Pedis Treatment Market Trends & Insights
The global landscape for Tinea Pedis treatment is undergoing a significant transformation driven by advancements in topical formulation technologies and a shifting consumer preference toward over-the-counter (OTC) solutions. Market intelligence indicates that the integration of novel drug delivery systems, such as hydrogels and film-forming sprays, is enhancing patient compliance by reducing the frequency of application and improving the penetration of active pharmaceutical ingredients (APIs). Furthermore, the rising awareness of foot hygiene in emerging economies, coupled with an increasing geriatric population susceptible to opportunistic fungal infections, is creating a sustained demand for both preventive and curative therapies. Competitive benchmarking reveals that leading pharmaceutical entities are increasingly focusing on fixed-dose combinations to address resistant fungal strains, which is a critical concern in clinical dermatology today.
- North America currently stands as the largest regional market, bolstered by high healthcare expenditure and a robust retail pharmacy network.
- The Asia-Pacific region is identified as the fastest-growing market due to rapid urbanization, increasing disposable income, and a high prevalence of fungal infections in tropical climates.
- The topical treatment segment remains the largest by value, accounting for over 65 percent of the total market share.
- Retail pharmacies and e-commerce platforms are emerging as the dominant distribution channels, driven by the convenience of OTC antifungal availability.
- The interdigital tinea pedis sub-segment holds the largest patient share among clinical presentations.
Key Takeaways Tinea Pedis Treatment Market Size & Forecast
The forecast period from 2025 to 2034 is expected to witness a steady trajectory in market valuation, supported by the continuous influx of generic alternatives that lower the barrier for treatment in low-to-middle-income countries. Strategic analysis suggests that while oral medications are reserved for severe or recalcitrant cases, the innovation pipeline is heavily skewed toward localized topical therapies that minimize systemic side effects. The market is also seeing a convergence of pharmaceutical and consumer goods strategies, where packaging innovation and brand positioning play a vital role in capturing market share in the highly competitive OTC aisle.
- The United States is the leading country contributor, driven by a high prevalence of athlete's foot among sports participants and fitness enthusiasts.
- Advancements in antifungal resistance research are expected to drive the development of next-generation allylamines and azoles.
- The moccasin-type tinea pedis segment is projected to show significant growth due to its chronic nature and the requirement for prolonged treatment cycles.
- Institutional healthcare procurement in Europe is focusing on cost-effective generic antifungals to manage public health expenditures.
- The digital health trend is facilitating market growth through online consultations and direct-to-consumer prescription deliveries.
Tinea Pedis Treatment Market Drivers Analysis
The primary catalysts for the Tinea Pedis Treatment Market involve a combination of demographic shifts and lifestyle changes. The proliferation of fitness culture, including the increased use of communal gym facilities, swimming pools, and locker rooms, has directly correlated with higher transmission rates of dermatophytes like Trichophyton rubrum. Additionally, the rising incidence of diabetes globally contributes to a larger pool of immunocompromised patients who are more susceptible to persistent tinea infections. Technological progress in formulation science, particularly the development of long-acting topical agents, is also a significant driver as it addresses the historical challenge of poor patient adherence to multi-week treatment regimens.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Fitness and Sports Culture | +1.5% | Global (High in North America/Europe) | 2025 - 2034 |
| Rising Geriatric and Diabetic Population | +1.2% | Japan, Germany, USA | 2026 - 2034 |
| Growth of OTC Antifungal Accessibility | +1.8% | China, India, Brazil | 2025 - 2030 |
| Novel Drug Delivery Systems (NDDS) | +0.9% | Western Europe, USA | 2027 - 2034 |
Tinea Pedis Treatment Market Restraints Analysis
Despite a positive growth outlook, the market faces constraints primarily related to the side effect profiles of systemic oral antifungals, which often include hepatotoxicity and gastrointestinal distress, leading to physician hesitation in prescribing them for mild cases. Furthermore, the high rate of self-diagnosis and subsequent use of inappropriate home remedies or sub-therapeutic OTC doses often leads to treatment failure and the development of resistant fungal strains. The market also contends with the saturation of generic terbinafine and clotrimazole products, which limits the profit margins for innovators and slows the pace of high-cost R&D investment.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Concerns Over Oral Antifungal Toxicity | -0.7% | Global | 2025 - 2034 |
| Rising Antifungal Resistance | -0.5% | India, Southeast Asia | 2026 - 2034 |
| Heavy Generic Competition | -1.1% | Global | 2025 - 2034 |
Tinea Pedis Treatment Market Opportunities Analysis
The market presents significant opportunities in the development of natural and bio-based antifungal agents, catering to the growing consumer segment that prefers "clean" or "green" pharmaceutical products. There is also a substantial untapped potential in emerging economies where healthcare infrastructure is improving, providing a pathway for branded generic manufacturers to establish market dominance. Moreover, the integration of teledermatology services allows for more accurate remote diagnosis, which can drive the sales of prescription-strength topical therapies that would otherwise go unpurchased due to the lack of clinical consultation.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Bio-based and Herbal Antifungal Formulations | +1.4% | Europe, North America | 2026 - 2034 |
| Expansion in Emerging E-commerce Markets | +2.1% | India, Indonesia, Mexico | 2025 - 2032 |
| Teledermatology Integration | +0.8% | Global | 2027 - 2034 |
Tinea Pedis Treatment Market Challenges Impact Analysis
Strategic challenges in the Tinea Pedis treatment landscape include the rigorous regulatory hurdles for new drug approvals, particularly for topical agents that must demonstrate superior efficacy over existing long-standing generics. Additionally, the lack of consumer education regarding the necessity of completing the full course of treatment remains a hurdle, as many patients stop application as soon as symptoms subside, leading to high recurrence rates. Supply chain volatility for active pharmaceutical ingredients (APIs) also poses a risk to consistent market availability in certain regions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Approval Pathways | -0.6% | USA (FDA), EU (EMA) | 2025 - 2034 |
| High Recurrence Rates and Patient Non-compliance | -1.2% | Global | 2025 - 2034 |
| API Supply Chain Disruptions | -0.4% | Global | Short-term (2025-2027) |
Tinea Pedis Treatment Market - Updated Report Scope
The scope of this market research report encompasses a comprehensive analysis of the global Tinea Pedis treatment landscape, providing detailed quantitative and qualitative insights across various segments. It covers the pharmacological spectrum from traditional azoles to modern allylamines and hydroxypyridones. The analysis includes a deep dive into the epidemiology of the condition across different demographics, the regulatory environment in key regions, and a competitive assessment of the leading market participants. This report is designed to serve as a strategic tool for stakeholders involved in product development, clinical research, and market expansion.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.12 Billion |
| Market Forecast in 2034 | USD 1.81 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Novartis AG (Sandoz), Bayer AG, GlaxoSmithKline PLC (GSK), Bausch Health Companies Inc., Taro Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Viatris Inc. (Mylan), Perrigo Company PLC, Pfizer Inc., Johnson & Johnson Services Inc., Sun Pharmaceutical Industries Ltd., Glenmark Pharmaceuticals, Aurobindo Pharma, Lupin Limited, Cipla Inc., Dr. Reddy’s Laboratories Ltd., Amneal Pharmaceuticals Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Tinea Pedis treatment market is segmented with precision to reflect the clinical and commercial diversity of the field. By type, the market distinguishes between the common interdigital presentation and the more stubborn moccasin and vesicular forms, each requiring different therapeutic durations. The drug class segmentation highlights the dominance of allylamines like terbinafine due to their fungicidal properties compared to the fungistatic nature of many azoles. Furthermore, the route of administration analysis shows a clear preference for topical treatments due to their localized action and safety profile, whereas oral systemic treatments are analyzed within the context of severe infections. The distribution channel analysis provides insights into how consumer behavior is shifting from traditional physical pharmacies to digital procurement platforms.
- By Type:
- Interdigital Tinea Pedis (Most common clinical form)
- Moccasin-type Tinea Pedis (Chronic and resistant form)
- Vesicular/Inflammatory Tinea Pedis (Less common but acute)
- By Drug Class:
- Allylamines (Terbinafine, Naftifine)
- Azoles (Clotrimazole, Miconazole, Ketoconazole, Econazole)
- Hydroxypyridones (Ciclopirox)
- Benzylamines (Butenafine)
- Others (Echinocandins, Griseofulvin)
- By Route of Administration:
- Topical (Creams, Ointments, Gels, Sprays, Solutions, Powders)
- Oral (Tablets, Capsules)
- By Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies (Leading segment for OTC)
- Online Pharmacies (Fastest growing channel)
- Supermarkets and Hypermarkets
Regional Highlights
Regional analysis indicates that North America holds the largest share of the global Tinea Pedis treatment market, largely due to high diagnostic rates and a mature retail landscape for antifungal products. In Europe, the market is characterized by a strong presence of pharmaceutical giants and a well-regulated healthcare system that emphasizes evidence-based treatment, particularly in Germany, France, and the UK. The Asia-Pacific region is poised for the highest growth rate, fueled by the tropical climate which favors fungal growth, a massive population base, and increasing urbanization in countries like India and China. Latin America and the MEA regions represent evolving markets where growth is linked to improving access to basic healthcare and the expansion of generic pharmaceutical manufacturing hubs.
- North America: Largest market share; driven by the US market and widespread availability of branded and generic OTC treatments.
- Europe: Focused on high-quality topical formulations and stringent regulatory standards for safety and efficacy.
- Asia-Pacific: Fastest-growing region; high incidence rates in humid climates and expanding middle-class healthcare spending.
- Latin America: Significant potential in Brazil and Mexico; growth supported by the expansion of local pharmacy chains.
- Middle East & Africa: Growing demand for essential antifungal medicines and improvement in pharmaceutical distribution networks.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Tinea Pedis Treatment Market.- Novartis AG (Sandoz)
- Bayer AG
- GlaxoSmithKline PLC (GSK)
- Bausch Health Companies Inc.
- Taro Pharmaceutical Industries Ltd.
- Teva Pharmaceutical Industries Ltd.
- Viatris Inc. (Mylan)
- Perrigo Company PLC
- Pfizer Inc.
- Johnson & Johnson Services Inc.
- Sun Pharmaceutical Industries Ltd.
- Glenmark Pharmaceuticals
- Aurobindo Pharma
- Lupin Limited
- Cipla Inc.
- Dr. Reddy’s Laboratories Ltd.
- Amneal Pharmaceuticals Inc.
- Hikma Pharmaceuticals PLC
- Almirall, S.A.
- Leo Pharma A/S
Frequently Asked Questions
What is the current market size of the Tinea Pedis treatment industry?
The Tinea Pedis treatment market is estimated to be valued at approximately USD 1.12 Billion in 2025, with projections indicating a rise to USD 1.81 Billion by 2034.
Which drug class is most effective for treating Tinea Pedis?
Allylamines, particularly Terbinafine, are often considered the most effective first-line treatment as they are fungicidal, meaning they kill the fungus, leading to shorter treatment durations compared to fungistatic azoles.
Why is the Asia-Pacific region expected to grow the fastest?
The region's growth is driven by a combination of high humidity and heat, which promotes fungal infections, alongside rapid improvements in healthcare infrastructure and rising consumer purchasing power for OTC medications.
What are the primary factors driving the shift toward topical treatments?
Topical treatments are preferred due to their direct application to the site of infection, lower risk of systemic side effects, and the availability of diverse formulations like sprays and gels that improve patient compliance.
How does antifungal resistance affect the market?
Antifungal resistance is a significant challenge that necessitates the development of new drug formulations and combination therapies, while also driving the demand for prescription-strength products when OTC options fail.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
