Thermal Conductive Additives Market
Thermal Conductive Additives Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711922 | Published On : November 21, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Thermal Conductive Additives Market Size
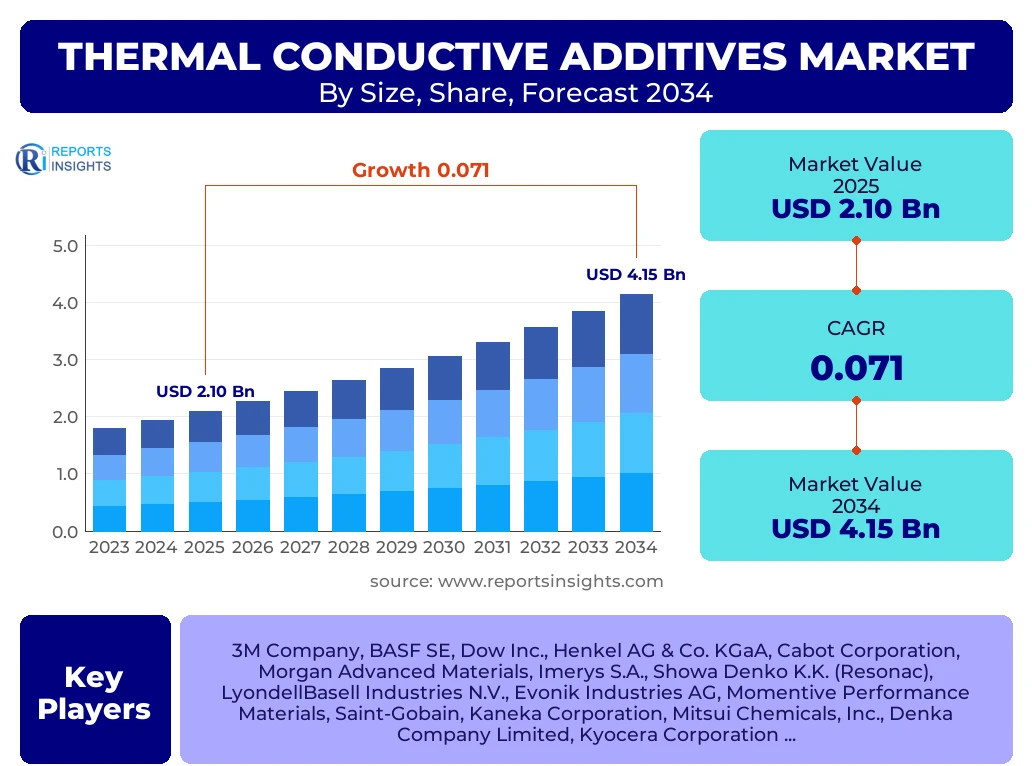
According to Reports Insights Consulting Pvt Ltd, The Thermal Conductive Additives Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.1% between 2025 and 2034. The market is estimated at USD 2.25 Billion in 2026 and is projected to reach USD 4.15 Billion by the end of the forecast period in 2034.
Key Thermal Conductive Additives Market Trends & Insights
The global landscape for thermal management materials is undergoing a paradigm shift, driven by the aggressive miniaturization of electronic components and the exponential rise of high-power density applications. Current market dynamics suggest a transition from traditional metallic fillers to advanced ceramic and carbon-based additives that offer superior dielectric properties alongside high thermal dissipation. Strategic focus is increasingly directed toward multi-modal filler systems, where combinations of different particle sizes and shapes are used to maximize packing density and minimize interfacial thermal resistance. Furthermore, the integration of graphene and carbon nanotubes is moving from laboratory research to commercial-scale pilot programs, particularly in high-frequency 5G infrastructure and aerospace applications where weight-to-performance ratios are critical.
Regional dynamics highlight a significant concentration of manufacturing and innovation in the Asia-Pacific corridor, particularly within China, Japan, and South Korea, which serve as the global hubs for semiconductor and consumer electronics production. In Western markets, the trend is heavily skewed toward the automotive sector, specifically the development of advanced battery thermal management systems (BTMS) for long-range electric vehicles. The demand for "electrically insulating but thermally conductive" additives is the most prominent trend, as manufacturers seek to protect sensitive circuits while ensuring efficient heat transfer to heat sinks or cooling plates.
- Largest Region: Asia-Pacific, holding approximately 45% of the total market share, driven by electronic manufacturing clusters.
- Fastest Growing Region: North America, projected to exhibit the highest CAGR due to rapid EV infrastructure expansion and data center investments.
- Largest Segment by Type: Ceramic additives (Alumina and Boron Nitride), dominating the share due to their balanced electrical insulation and thermal performance.
- Leading Application: Electronics and Telecommunications, accounting for the highest volume consumption.
Key Takeaways Thermal Conductive Additives Market Size & Forecast
The market trajectory is firmly anchored in the transition toward sustainable and efficient energy consumption. As thermal management becomes a bottleneck for the performance of next-generation devices, the value of specialized additives continues to appreciate. Stakeholders are shifting focus toward high-purity synthetic fillers that offer consistent performance across varying temperature ranges. The forecast period is expected to see a significant spike in demand for spherical alumina and boron nitride powders as they allow for higher filler loading levels without compromising the processability or rheology of the host polymer matrix.
- High-Purity Alumina (HPA) dominance: HPA remains the workhorse of the industry due to its cost-effectiveness and reliable performance in automotive electronics.
- Emergence of 5G and 6G: The rollout of high-frequency communication networks necessitates materials with low dielectric loss and high thermal conductivity, boosting niche additive markets.
- Sustainability in Additive Manufacturing: There is a growing push for bio-based or recycled thermal fillers to meet corporate ESG targets in the electronics and automotive sectors.
- China's Manufacturing Supremacy: China continues to lead in both production capacity and domestic consumption of basic thermal additives.
Thermal Conductive Additives Market Drivers Analysis
The primary catalysts for market expansion include the global electrification of the transport sector and the surging demand for high-performance computing. As electric vehicle batteries require sophisticated cooling to ensure safety and longevity, the demand for thermally conductive plastics and potting compounds has reached unprecedented levels. Additionally, the proliferation of Internet of Things (IoT) devices and AI-driven data centers necessitates advanced thermal interface materials to prevent hardware throttling and failure.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| EV Battery Thermal Management | +2.4% | Global (Strongest in Europe & China) | 2025–2034 |
| 5G Infrastructure Rollout | +1.8% | USA, South Korea, China | 2025–2030 |
| Miniaturization of Consumer Electronics | +1.5% | Japan, Taiwan, Vietnam | 2026–2034 |
Thermal Conductive Additives Market Restraints Analysis
Despite robust growth, the market faces significant hurdles related to the high cost of premium additives like spherical boron nitride and graphene. Furthermore, the technical challenge of maintaining mechanical properties while increasing filler loading limits the application scope. High loading levels often lead to increased viscosity and brittleness in the end product, complicating the injection molding and extrusion processes used in mass manufacturing.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Speciality Ceramics | -1.2% | Global | 2025–2034 |
| Processability Issues at High Loading | -0.9% | Germany, USA (Advanced Manufacturing) | 2026–2032 |
Thermal Conductive Additives Market Opportunities Analysis
The rise of Artificial Intelligence (AI) and Machine Learning (ML) hardware provides a lucrative frontier for thermal additive manufacturers. AI chips generate excessive heat that traditional cooling cannot manage alone, opening doors for liquid-cooled systems utilizing advanced thermally conductive fluids and pastes. Moreover, the transition to renewable energy storage systems (BESS) creates a massive secondary market for thermal management in large-scale lithium-ion and solid-state battery arrays.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI Data Center Cooling | +1.7% | North America, Northern Europe | 2025–2034 |
| Solid-State Battery Development | +1.1% | Japan, USA, Germany | 2028–2034 |
Thermal Conductive Additives Market Challenges Impact Analysis
The primary technical challenge remains the "Thermal-Electrical Trade-off." Many materials that are highly thermally conductive are also electrically conductive (like metals and carbon), which is detrimental for electronic insulation applications. Developing additives that break this correlation at a low price point is the industry's biggest hurdle. Additionally, supply chain volatility for raw materials like boron and high-purity graphite poses a risk to consistent production schedules.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Electrical Insulation Requirements | -0.7% | Global (Electronics Sector) | 2025–2034 |
| Raw Material Supply Volatility | -0.5% | Global (Specifically APAC-sourced) | 2025–2030 |
Thermal Conductive Additives Market - Updated Report Scope
This report provides a granular analysis of the thermal conductive additives industry, encompassing material science innovations, supply chain dynamics, and end-user demand shifts. It covers a wide array of additives including oxide ceramics, non-oxide ceramics, carbon allotropes, and metallic fillers across various polymer matrices. The scope extends to a comprehensive regional analysis and competitive benchmarking of key market participants.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.10 Billion |
| Market Forecast in 2034 | USD 4.15 Billion |
| Growth Rate | 7.1% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | 3M Company, BASF SE, Dow Inc., Henkel AG & Co. KGaA, Cabot Corporation, Morgan Advanced Materials, Imerys S.A., Showa Denko K.K. (Resonac), LyondellBasell Industries N.V., Evonik Industries AG, Momentive Performance Materials, Saint-Gobain, Kaneka Corporation, Mitsui Chemicals, Inc., Denka Company Limited, Kyocera Corporation, Huber Engineered Materials, PolyOne Corporation (Avient), Arkema S.A. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented primarily by material type and end-use application, with each segment exhibiting unique growth drivers. Ceramic additives currently dominate the market because they provide the necessary electrical insulation required for modern circuit boards and battery modules. Within the ceramic segment, Boron Nitride is the premium choice for high-end applications due to its lubrication properties and exceptional thermal conductivity, whereas Alumina remains the high-volume choice for cost-sensitive industries. Carbon-based additives are witnessing rapid growth in areas where electrical conductivity is either desired or can be mitigated through hybrid filler strategies.
- By Type:
- Oxide Ceramics: High-purity Alumina, Magnesium Oxide, Zinc Oxide.
- Non-Oxide Ceramics: Boron Nitride (Hexagonal), Aluminum Nitride, Silicon Nitride.
- Carbon-based: Expanded Graphite, Graphene, Carbon Nanotubes (MWCNT/SWCNT), Carbon Black.
- Metallic Fillers: Silver, Copper, Aluminum powders.
- By Application:
- Thermal Interface Materials (TIMs): Greases, pads, phase change materials.
- Thermally Conductive Plastics: Housing for LEDs, automotive components.
- Potting Compounds & Encapsulants: Protective resins for electronics.
- Adhesives & Sealants: Structural bonding with heat dissipation.
- By End-Use Industry:
- Electronics: Smartphones, laptops, 5G base stations, servers.
- Automotive: EV batteries, ADAS sensors, power electronics.
- Energy: LED lighting, Photovoltaic inverters, Energy storage.
- Aerospace: Satellite thermal control, avionics.
Regional Highlights
The regional landscape is characterized by the geographic concentration of specific industrial sectors. The Asia-Pacific region, spearheaded by China, remains the manufacturing powerhouse for consumer electronics, leading to massive consumption of alumina and graphite-based additives. China’s dominance is further bolstered by its control over significant portions of the raw material supply chain for graphite. In contrast, Japan and South Korea are leaders in high-purity synthetic additives, such as spherical boron nitride, exported globally for high-end semiconductor applications.
North America and Europe are experiencing a resurgence in demand driven by the "Green Transition." The European Union's stringent carbon emission regulations and the US Inflation Reduction Act (IRA) have stimulated massive investments in domestic EV battery manufacturing. This has created a localized demand for high-performance thermal conductive additives for battery modules and charging infrastructure. North America is also the primary hub for data center innovation, where the push for AI-capable hardware is driving the adoption of next-generation thermal management solutions.
- Asia-Pacific: Largest market share; leader in consumer electronics and LED manufacturing. China and Taiwan are the primary value contributors.
- North America: Fastest growing region for AI data center applications and advanced TIMs.
- Europe: Leading the market for EV battery thermal management and sustainable/bio-based additive solutions.
- Middle East & Africa: Growing interest in thermal management for solar energy systems and infrastructure cooling.
- Latin America: Emerging market with steady growth in automotive assembly and industrial electronics.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Thermal Conductive Additives Market.- 3M Company
- BASF SE
- Dow Inc.
- Henkel AG & Co. KGaA
- Cabot Corporation
- Morgan Advanced Materials
- Imerys S.A.
- Showa Denko K.K. (Resonac)
- LyondellBasell Industries N.V.
- Evonik Industries AG
- Momentive Performance Materials
- Saint-Gobain
- Kaneka Corporation
- Mitsui Chemicals, Inc.
- Denka Company Limited
- Kyocera Corporation
- Huber Engineered Materials
- PolyOne Corporation (Avient)
- Arkema S.A.
- Potters Industries LLC
Frequently Asked Questions
What are thermal conductive additives, and why are they used?
Thermal conductive additives are specialized fillers (such as ceramics, carbons, or metals) incorporated into polymers or resins to enhance their ability to dissipate heat. They are essential in modern electronics and automotive sectors to prevent overheating, ensure component longevity, and maintain performance in high-power density environments.
Which material is the most preferred for electrical insulation?
Ceramic additives, specifically Alumina and Boron Nitride, are the most preferred for applications requiring electrical insulation. While Alumina is the cost-effective standard, Boron Nitride is used for high-performance applications where superior thermal conductivity and low dielectric constant are required simultaneously.
How is the rise of electric vehicles affecting this market?
The EV boom is a primary driver for the market. Electric vehicle batteries and power conversion systems generate significant heat. Thermal conductive additives are used in gap fillers, potting compounds, and battery housings to transfer heat away from the cells to the cooling system, ensuring safety and fast-charging capabilities.
What are the main challenges in the thermal conductive additives industry?
The major challenges include the high cost of advanced materials like Graphene and Spherical Boron Nitride, the difficulty of maintaining polymer processability at high filler loadings, and the technical hurdle of achieving high thermal conductivity without making the material electrically conductive.
Which region offers the highest growth potential for investors?
While Asia-Pacific currently holds the largest share, North America offers the highest growth potential for high-tech additives due to the concentration of AI data centers and the rapid domestic expansion of the EV supply chain, creating demand for high-margin, specialized thermal management solutions.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
