Terracotta Cladding Market
Terracotta Cladding Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711866 | Published On : November 19, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Terracotta Cladding Market Size
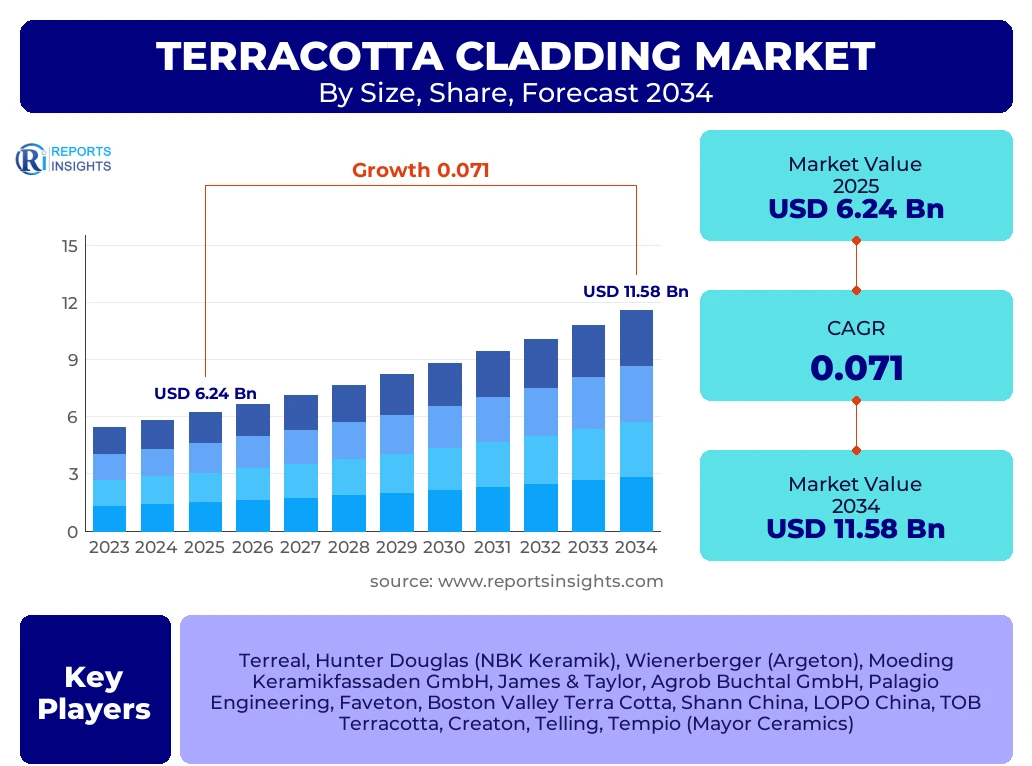
According to Reports Insights Consulting Pvt Ltd, The Terracotta Cladding Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.1% between 2025 and 2034. The market is estimated at USD 6.68 Billion in 2026 and is projected to reach USD 11.58 Billion by the end of the forecast period in 2034.
The valuation of the global terracotta cladding sector is fundamentally supported by the escalating demand for sustainable, high-performance building envelopes. In 2025, the market is expected to settle at a base valuation of USD 6.24 Billion, reflecting a steady recovery in the commercial construction sector and a pivot toward non-combustible facade materials. This growth trajectory is driven by institutional investments in green infrastructure and a rising preference for materials that offer both longevity and aesthetic versatility.
As urban density increases globally, the architectural community is increasingly prioritizing materials that contribute to thermal efficiency and reduced carbon footprints. Terracotta, being a natural clay-based product, aligns perfectly with circular economy principles. The forecast period from 2026 to 2034 will likely witness a surge in the adoption of ventilated rainscreen systems, which leverage terracotta's natural properties to manage moisture and thermal loads effectively, thereby securing the market's long-term expansion.
Key Terracotta Cladding Market Trends & Insights
The global terracotta cladding landscape is currently defined by a transition toward biophilic design and advanced manufacturing techniques. Architects are moving away from traditional flat panels in favor of complex 3D geometries, custom-extruded shapes, and bespoke glazing. This trend is particularly evident in the European and North American markets, where building facades are treated as high-performance skins rather than just aesthetic shells. Furthermore, the integration of terracotta with other materials like glass and aluminum in modular curtain wall systems is streamlining installation processes and reducing labor costs on-site.
From a regional perspective, the Asia-Pacific region continues to dominate in terms of volume, driven by massive infrastructure projects in China and India. However, the fastest growth is observed in regions implementing strict carbon neutrality mandates. Technological advancements, such as digital inkjet printing on ceramic surfaces, are also allowing manufacturers to replicate natural stone or wood textures while maintaining the durability and fire resistance of terracotta. These insights suggest a market that is becoming increasingly specialized, with a heavy emphasis on customization and technical performance over generic mass production.
- Largest Region: Asia-Pacific remains the dominant market shareholder, accounting for over 40% of the global demand due to rapid urbanization and large-scale commercial developments.
- Fastest Growing Region: North America is projected to experience the highest CAGR during the forecast period, fueled by stringent fire safety regulations and the "Green Building" movement.
- Leading Segment by Type: Terracotta Panels currently hold the largest market share, valued for their ease of installation and structural reliability.
- Leading Segment by Application: The Commercial sector remains the primary end-user, specifically in high-rise office buildings and educational institutions.
- Technological Shift: Significant movement toward ventilated rainscreen systems (VRS) to improve building breathability and energy efficiency.
Key Takeaways Terracotta Cladding Market Size & Forecast
The market for terracotta cladding is entering a phase of sustained growth characterized by a shift from niche aesthetic applications to mainstream functional requirements. Investors and stakeholders are focusing on the material's lifecycle value, noting that while initial costs may be higher than synthetic alternatives, the minimal maintenance and extreme durability (often exceeding 50-100 years) provide a superior return on investment. The forecast indicates that by 2034, the market will have nearly doubled in size, supported by the global push for net-zero energy buildings and the rising cost of traditional energy-intensive facade materials.
- Durability Advantage: Terracotta’s resistance to UV radiation and chemical pollutants ensures color permanence, making it a preferred choice for long-term municipal projects.
- Regulatory Drivers: International building codes are increasingly mandating A1 fire-rated materials, a category where terracotta naturally excels.
- Sustainable Positioning: As life-cycle assessments (LCA) become standard in construction procurement, terracotta’s recyclability and low-impact extraction provide a competitive edge.
- Key Growth Country: China is expected to maintain its position as the largest single-country market, though India is emerging as a high-potential frontier.
- Innovation Focus: R&D is heavily concentrated on reducing the weight of panels and developing faster-attachment clips to lower total project costs.
Terracotta Cladding Market Drivers Analysis
The primary drivers of the terracotta cladding market are rooted in the global transition toward sustainable urbanization and the tightening of building safety standards. As energy costs rise, the thermal mass properties of terracotta are becoming a critical factor in reducing HVAC loads in large commercial structures. Additionally, the psychological move toward natural materials in urban environments—often referred to as biophilic design—is encouraging developers to choose clay-based facades over cold, industrial metals or plastics.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Fire Safety Regulations (Non-combustibility) | +2.3% | UK, Australia, USA, UAE | 2025-2034 |
| Growth in Green Building Certifications (LEED/BREEAM) | +1.8% | Europe and North America | 2026-2030 |
| Urbanization and Smart City Initiatives | +1.5% | China, India, SE Asia | 2025-2034 |
| Demand for Low-Maintenance Facade Solutions | +0.9% | Global | 2027-2034 |
Terracotta Cladding Market Restraints Analysis
Despite its benefits, the market faces significant hurdles related to initial capital expenditure and logistical complexities. Terracotta is a heavy material compared to modern composites, requiring robust structural support systems and specialized handling during transport to prevent breakage. Furthermore, the specialized nature of the installation process means that a shortage of skilled labor can lead to project delays and increased overall costs in mature markets.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Product and Installation Costs | -1.2% | Developing Economies | 2025-2030 |
| Weight-Related Structural Requirements | -0.8% | Global (High-rise projects) | 2025-2034 |
| Fragility During Transit and Logistics | -0.5% | Landlocked Regions | 2025-2028 |
Terracotta Cladding Market Opportunities Analysis
The most significant opportunities lie in the renovation and adaptive reuse sector. In many developed cities, older buildings are being retrofitted with modern facade skins to meet current insulation and safety codes. Terracotta is uniquely suited for this as it can be designed to mimic historical styles while providing 21st-century performance. Furthermore, the development of solar-integrated terracotta tiles and air-purifying glazes represents a frontier for high-tech architectural innovation.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Facade Retrofitting and Building Renovation Wave | +2.1% | European Union (EU) | 2026-2034 |
| 3D Printing and Custom Geometric Extrusion | +1.4% | Global Architectural Firms | 2028-2034 |
| Integration with Photovoltaic (PV) Technologies | +1.1% | Japan, Germany, USA | 2029-2034 |
Terracotta Cladding Market Challenges Impact Analysis
The market must navigate challenges related to supply chain volatility and competition from low-cost alternative materials. Fiber cement and high-pressure laminates (HPL) often compete for the same project budgets by offering lower price points, despite having shorter lifespans. Additionally, the energy-intensive nature of the kiln-firing process remains a challenge as manufacturers face pressure to reduce their industrial carbon emissions to maintain their "green" credentials.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Low-Cost Synthetic Cladding | -1.5% | Global Residential Market | 2025-2034 |
| Decarbonization of Ceramic Kiln Processes | -0.7% | Europe, North America | 2025-2030 |
| Shortage of Certified Installation Specialists | -0.6% | North America, ANZ | 2026-2032 |
Terracotta Cladding Market - Updated Report Scope
This report provides a granular analysis of the global terracotta cladding industry, covering technological shifts, material innovations, and geopolitical factors affecting supply chains. It encompasses a comprehensive evaluation of various product forms, including panels, baguettes, and louvers, across both new construction and renovation sectors. The scope extends to a detailed competitive landscape analysis, identifying the strategic maneuvers of top-tier manufacturers as they expand into emerging markets.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 6.24 Billion |
| Market Forecast in 2034 | USD 11.58 Billion |
| Growth Rate | 7.1% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Terreal, Hunter Douglas (NBK Keramik), Wienerberger (Argeton), Moeding Keramikfassaden GmbH, James & Taylor, Agrob Buchtal GmbH, Palagio Engineering, Faveton, Boston Valley Terra Cotta, Shann China, LOPO China, TOB Terracotta, Creaton, Telling, Tempio (Mayor Ceramics) |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The terracotta cladding market is segmented based on product configuration, installation system, surface finish, and end-user application. Panels represent the most significant segment by volume, utilized extensively in large-scale commercial facades due to their durability and modular nature. Baguettes and louvers are growing in popularity as sun-shading devices, contributing to building energy efficiency by managing solar gain while allowing natural light penetration. The market is also seeing a distinct split between natural finishes, favored for their organic look, and glazed finishes, which provide vibrant colors and self-cleaning properties in urban environments.
- By Type:
- Terracotta Panels (Solid and Hollow core)
- Terracotta Baguettes (Square, Circular, Custom profiles)
- Terracotta Louvers (Sunshades)
- Specialized Shapes and Accents
- By System:
- Ventilated Rainscreen Systems (Standard and Pressure-equalized)
- Direct-applied Systems
- By Surface Texture:
- Natural/Earth Tone
- Glazed (Glossy and Matte)
- Polished/Sanded
- Striped/Grooved
- By Application:
- Commercial Office Buildings
- Educational Institutions and Museums
- Healthcare Facilities
- High-end Residential Complexes
- Public Infrastructure (Airports, Railway Stations)
Regional Highlights
Regionally, the market is characterized by varying levels of maturity and adoption drivers. Europe remains a key center for innovation, with Germany and France leading in high-end ceramic engineering and sustainable architecture. The European market is highly focused on the "Renovation Wave," where terracotta is used to upgrade the thermal performance of post-war housing and institutional buildings. In North America, the market is expanding beyond the high-end niche as developers recognize the material's longevity and fire-resistant properties in the wake of updated safety codes.
- Asia-Pacific: The largest market globally, with China accounting for a massive share of production and consumption. Growth is driven by rapid urbanization and a shift toward premium building materials in Tier-1 cities.
- Europe: The most mature market with a focus on high-performance ventilated facades. Germany is the regional hub for technical terracotta manufacturing.
- North America: Fastest-growing region due to a strong rebound in commercial construction and a massive shift toward sustainable, non-combustible cladding materials in the US and Canada.
- Middle East: A significant growth pocket where terracotta is used for its high thermal mass, providing natural cooling in desert climates, particularly in the UAE and Saudi Arabia (Giga-projects like NEOM).
- Latin America & MEA: Emerging markets where terracotta is increasingly specified for government buildings and luxury hospitality projects.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Terracotta Cladding Market.- Terreal (France)
- NBK Keramik (Hunter Douglas) (Germany)
- Wienerberger (Argeton) (Austria)
- Moeding Keramikfassaden GmbH (Germany)
- James & Taylor (UK)
- Agrob Buchtal GmbH (Germany)
- Palagio Engineering (Italy)
- Faveton (Spain)
- Boston Valley Terra Cotta (USA)
- Shann China (China)
- LOPO China (China)
- TOB Terracotta (China)
- Creaton (Germany)
- Telling (UK)
- Tempio (Mayor Ceramics) (Spain)
- Sannini (Italy)
- Koramic (Wienerberger Group) (Belgium)
- Acme Brick Company (USA)
Frequently Asked Questions
What is the primary reason for the high cost of terracotta cladding compared to other materials?
The cost is primarily driven by the energy-intensive kiln-firing process and the specialized engineering required for the extrusion of large-format panels. Additionally, the high-quality clay used and the complex aluminum support systems needed for installation add to the initial capital expenditure, though this is offset by long-term durability and low maintenance.
How does terracotta cladding contribute to building energy efficiency?
Terracotta cladding, especially when used in ventilated rainscreen systems, acts as a thermal shield. Its natural thermal mass helps regulate internal temperatures by absorbing heat during the day and releasing it slowly. The ventilated cavity also allows for natural air circulation, reducing moisture buildup and lowering HVAC energy consumption.
Is terracotta cladding fireproof?
Yes, terracotta is a non-combustible material made from natural clay fired at extremely high temperatures. Most terracotta cladding systems achieve an A1 fire rating (the highest possible), making them an ideal choice for high-rise buildings and public structures where fire safety is a top priority.
Can terracotta cladding be customized for specific architectural designs?
Absolutely. Modern manufacturing allows for extreme customization in terms of color, texture, and shape. Manufacturers can create custom-extruded profiles, 3D geometric shapes, and bespoke glazes that can match historical styles or create futuristic designs, providing architects with significant creative freedom.
Which region is expected to lead the terracotta cladding market by 2034?
While Asia-Pacific will likely remain the largest market in terms of total volume and production, North America is expected to show the most rapid growth due to increasing institutional investment in green buildings and strict adherence to non-combustible material mandates in urban development.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
