Telecom Services Market
Telecom Services Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711012 | Published On : September 28, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Telecom Services Market Size
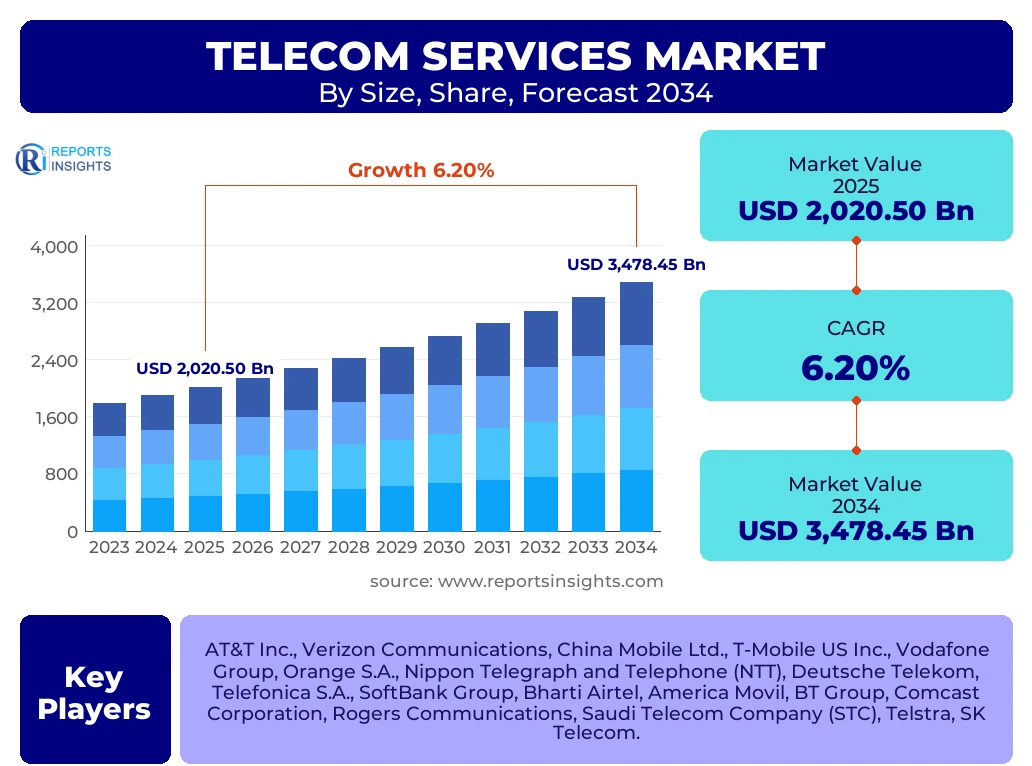
According to Reports Insights Consulting Pvt Ltd, The Telecom Services Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2026 and 2034. The market is estimated at USD 2,145.80 Billion in 2026 and is projected to reach USD 3,478.45 Billion by the end of the forecast period in 2034.
Key Telecom Services Market Trends & Insights
The global telecom services market is undergoing a profound transformation driven by the rapid deployment of 5G infrastructure, the integration of Artificial Intelligence (AI) in network management, and the rising demand for high-speed data connectivity across residential and enterprise sectors. Analysts observe that regional insights highlight a massive shift toward digital-first economies, where telecom operators are transitioning from traditional connectivity providers to holistic digital service enablers. In North America and Europe, the focus is on consolidating 5G standalone (SA) networks to support low-latency applications like autonomous driving and remote surgery. Conversely, in the Asia-Pacific region, the market is characterized by a surge in mobile data consumption and massive government investments in smart city projects. Competitive benchmarking reveals that leading players are increasingly leveraging Edge Computing and Network Function Virtualization (NFV) to optimize operational efficiency and reduce energy consumption. Furthermore, the convergence of satellite communication and terrestrial networks is emerging as a critical trend to bridge the digital divide in rural and underserved areas.
- Largest Region: Asia-Pacific holds the largest market share, driven by extensive subscriber bases in China and India and aggressive 5G expansion.
- Fastest Growing Region: Middle East and Africa (MEA) is expected to exhibit the highest CAGR due to rapid urbanization and digital infrastructure upgrades.
- Largest Segment by Share: Mobile Data Services currently dominate the market share as consumers shift away from traditional voice services toward high-bandwidth applications.
- Emerging Trend: The adoption of Open Radio Access Network (Open RAN) architectures is gaining momentum, allowing operators to mix and match hardware and software from different vendors.
- Sustainability Focus: Telecommunication companies are increasingly committing to Net Zero targets, implementing green energy solutions at base stations and data centers.
Key Takeaways Telecom Services Market Size & Forecast
The market size and forecast for telecom services reflect a resilient industry that acts as the backbone of global digital transformation. Research into common user questions suggests that stakeholders are primarily concerned with the sustainability of growth in a saturated mobile market and the potential of B2B services to offset declining voice revenues. Insights indicate that the enterprise segment, particularly small and medium enterprises (SMEs) adopting cloud-based communication tools, will be a significant growth engine. The forecast period 2025-2034 highlights a move toward hyper-connectivity, where the Internet of Things (IoT) will contribute a larger percentage of total network traffic. Leading countries like the United States, China, South Korea, and Germany are setting the pace for technological standards, while developing nations are focusing on 4G to 5G migration. The integration of 6G research toward the end of the decade is also expected to begin influencing long-term strategic investments by 2030.
- Leading Country: China remains the leading market in terms of 5G base station deployment and total mobile subscribers.
- Revenue Diversification: Operators are moving toward Value-Added Services (VAS), including fintech, digital content, and cybersecurity, to improve Average Revenue Per User (ARPU).
- Infrastructure Investment: Fiber-to-the-Home (FTTH) expansion continues to be a priority for fixed broadband growth in Europe and North America.
- Regulatory Impact: Spectrum auction pricing and net neutrality regulations remain critical factors influencing market profitability in various jurisdictions.
- Consumer Behavior: The rise of remote work and hybrid education has solidified the demand for high-reliability, low-latency residential broadband.
Telecom Services Market Drivers Analysis
The growth of the telecom services market is propelled by a combination of technological advancements and changing consumer expectations. The primary driver is the global transition to 5G technology, which offers unprecedented speeds and lower latency, enabling a new ecosystem of services. Additionally, the proliferation of connected devices under the IoT umbrella necessitates robust and scalable telecom infrastructure. Governments worldwide are also playing a crucial role by providing subsidies and favorable policies for broadband expansion, viewing connectivity as an essential utility similar to electricity or water. The shift toward cloud-native architectures in the enterprise sector further fuels the demand for dedicated high-speed leased lines and software-defined wide area networks (SD-WAN).
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| 5G Network Expansion | +2.4% | Global / North America & APAC | 2025 - 2034 |
| IoT and Connected Devices | +1.8% | Developed Markets | 2025 - 2030 |
| Enterprise Digital Transformation | +1.5% | Europe / India / USA | 2026 - 2034 |
| Rising Demand for High-Speed Broadband | +1.2% | Latin America / MEA | 2025 - 2028 |
Telecom Services Market Restraints Analysis
Despite the positive growth trajectory, the market faces significant hurdles. High Capital Expenditure (CAPEX) required for 5G deployment and fiber optic installation places a heavy financial burden on operators, especially in regions with low ARPU. Additionally, the saturation of the mobile subscriber market in developed nations limits the scope for organic growth. Regulatory constraints, including stringent data privacy laws and complex spectrum licensing processes, can delay network rollouts and increase operational costs. Furthermore, the decline in traditional voice and SMS revenues due to the rise of Over-The-Top (OTT) communication platforms continues to squeeze profit margins.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High CAPEX for Infrastructure | -1.5% | Global | 2025 - 2029 |
| Market Saturation in Developed Regions | -0.8% | Europe / North America | 2025 - 2034 |
| Stringent Regulatory Requirements | -0.6% | European Union / India | 2026 - 2030 |
Telecom Services Market Opportunities Analysis
The telecom sector is ripe with opportunities for innovation and revenue growth. One of the most significant opportunities lies in Private 5G networks for industrial sectors such as manufacturing, mining, and logistics, providing secure and dedicated connectivity for automation. The integration of AI for predictive maintenance and personalized customer service offers a path toward operational excellence. Furthermore, the expansion of satellite-based broadband services presents a massive opportunity to reach the billions of people who currently lack reliable internet access. Collaborations with content providers and the development of in-house fintech services also allow operators to capture a larger share of the digital wallet.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Private 5G for Industry 4.0 | +2.1% | USA / Germany / Japan | 2026 - 2034 |
| Satellite Internet Integration | +1.3% | MEA / Latin America / Rural Regions | 2027 - 2034 |
| AI-Driven Network Automation | +0.9% | Global | 2025 - 2034 |
Telecom Services Market Challenges Impact Analysis
The market must navigate several complex challenges to maintain its momentum. Cybersecurity is a paramount concern, as the increase in connected devices expands the attack surface for hackers, requiring massive investments in security protocols. Additionally, the environmental impact of energy-intensive data centers and base stations is coming under intense scrutiny from regulators and ESG-conscious investors. The technical challenge of achieving seamless interoperability between legacy 4G systems and new 5G/6G architectures also complicates network upgrades. Lastly, the geopolitical tensions affecting the global supply chain for critical telecom hardware components remain a persistent risk.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Vulnerabilities | -1.1% | Global | Ongoing |
| Supply Chain Disruptions | -0.7% | Global / Semiconductors | 2025 - 2027 |
| Environmental & ESG Pressure | -0.5% | Europe / North America | 2026 - 2034 |
Telecom Services Market - Updated Report Scope
The updated report scope provides a comprehensive analysis of the global telecom services landscape, covering fixed-line, mobile, and satellite-based communication services. It offers a detailed breakdown of the market by service type, end-user, and transmission technology, ensuring stakeholders have a 360-degree view of current and future trends. The report utilizes advanced statistical modeling to project growth across various regions, factoring in economic indicators, technological adoption rates, and regulatory shifts. It serves as a strategic roadmap for telecom operators, equipment manufacturers, and investors to navigate the complexities of the next decade of connectivity.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2,020.50 Billion |
| Market Forecast in 2034 | USD 3,478.45 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | AT&T Inc., Verizon Communications, China Mobile Ltd., T-Mobile US Inc., Vodafone Group, Orange S.A., Nippon Telegraph and Telephone (NTT), Deutsche Telekom, Telefonica S.A., SoftBank Group, Bharti Airtel, America Movil, BT Group, Comcast Corporation, Rogers Communications, Saudi Telecom Company (STC), Telstra, SK Telecom. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the telecom services market reveals a dynamic shift in revenue streams. While mobile data services represent the largest and fastest-growing segment, fixed broadband remains a critical anchor for residential services, particularly with the growth of fiber-to-the-home (FTTH). The commercial segment is evolving rapidly, with enterprises demanding high-capacity, low-latency connections to support cloud computing and remote workforce environments. Pay-TV services are facing pressure from OTT streaming but are being bundled into multi-play offerings to maintain subscriber loyalty.
- By Service Type:
- Mobile Data Services (Streaming, browsing, social media)
- Mobile Voice Services (Traditional cellular calling)
- Fixed Data Services (Broadband, Fiber, DSL)
- Fixed Voice Services (PSTN, VoIP)
- Pay-TV and Bundled Services
- By Transmission Technology:
- Wireless (5G, 4G LTE, 3G/2G)
- Wireline (Fiber Optic, Coaxial Cable, Copper)
- Satellite (LEO, GEO)
- By End-User:
- Residential (Consumer household applications)
- Enterprise (BFSI, Healthcare, Retail, Manufacturing, IT & Telecom)
- Government and Public Sector (Public safety, smart cities)
Regional Highlights
Regional analysis indicates that Asia-Pacific leads the market in terms of volume, accounting for over 35% of the global share. This is attributed to the presence of massive consumer bases in China and India, coupled with rapid industrialization. North America remains the leader in technology innovation and ARPU, with the US market seeing significant investment in 5G mid-band spectrum and fixed-wireless access (FWA). Europe is focusing on the Digital Decade 2030 goals, aiming for full fiber coverage across the continent. In contrast, the MEA and Latin American regions are identified as high-growth pockets where the transition from 3G to 4G/5G and the deployment of undersea cables are primary market catalysts.
- North America: High ARPU and early 5G adoption; leader in enterprise telecom solutions.
- Europe: Focused on fiber infrastructure and strict data privacy regulations (GDPR).
- Asia-Pacific: Largest subscriber base; dominant in 5G infrastructure manufacturing and deployment.
- Latin America: Rapid growth in mobile internet penetration and digital banking services.
- Middle East & Africa: Fastest-growing region due to infrastructure modernization and youth-driven data consumption.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Telecom Services Market.- AT&T Inc.
- Verizon Communications Inc.
- China Mobile Limited
- T-Mobile US, Inc.
- Vodafone Group Plc
- Orange S.A.
- Nippon Telegraph and Telephone Corporation (NTT)
- Deutsche Telekom AG
- Telefonica S.A.
- SoftBank Group Corp.
- Bharti Airtel Limited
- America Movil
- BT Group plc
- Comcast Corporation
- Rogers Communications
- Saudi Telecom Company (STC)
- Telstra Corporation Limited
- SK Telecom Co., Ltd.
- KT Corporation
- Reliance Jio Infocomm Limited
Frequently Asked Questions
What is the current global market size of Telecom Services?
The global Telecom Services market is estimated to be valued at approximately USD 2,020.50 Billion in 2025, with a projected growth path to reach over USD 3,478.45 Billion by 2034.
What is the projected CAGR for the Telecom Services market through 2034?
The market is expected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% during the forecast period from 2025 to 2034.
Which region is expected to lead the Telecom Services market?
Asia-Pacific currently holds the largest market share and is expected to remain the leading region due to high mobile penetration and aggressive 5G rollout in China and India.
How is 5G technology impacting the market growth?
5G technology is a primary driver, enabling higher data speeds, lower latency, and the support of millions of IoT devices, which creates new revenue streams for operators in both B2C and B2B segments.
What are the major challenges facing telecom operators today?
Key challenges include the high capital expenditure for network upgrades, intense competition from OTT service providers, and increasing cybersecurity threats to network infrastructure.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted