Sternal Closure Systems Market
Sternal Closure Systems Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711093 | Published On : October 06, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Sternal Closure Systems Market Size
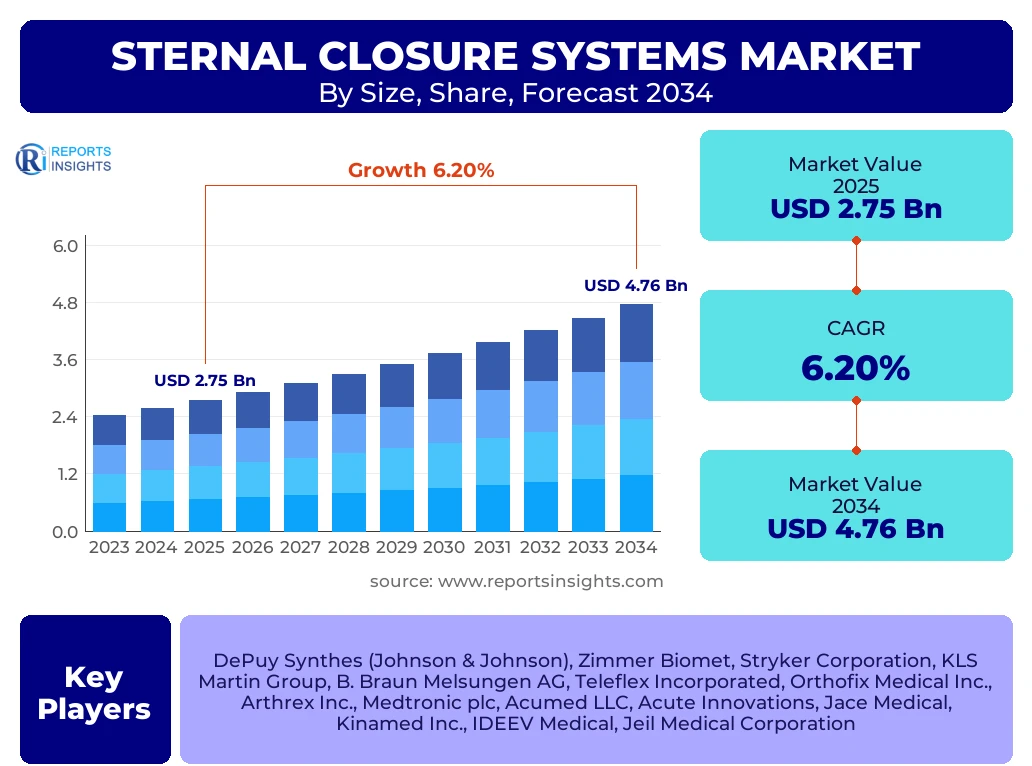
According to Reports Insights Consulting Pvt Ltd, The Sternal Closure Systems Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 2.92 Billion in 2026 and is projected to reach USD 4.76 Billion by the end of the forecast period in 2034.
Key Sternal Closure Systems Market Trends & Insights
The global sternal closure systems market is undergoing a significant transition from traditional monofilament wiring techniques to advanced rigid fixation systems. This shift is primarily motivated by the clinical necessity to reduce post-operative complications such as sternal dehiscence and mediastinitis. Market intelligence suggests that clinicians are increasingly prioritizing systems that offer superior biomechanical stability, which facilitates earlier patient mobilization and shorter intensive care unit stays. Furthermore, the integration of bioresorbable materials and the development of specialized closure systems for high-risk cohorts—including patients with obesity, diabetes, or osteoporosis—are emerging as pivotal trends that are redefining the competitive landscape across major healthcare economies.
- Largest Region: North America currently holds the largest market share, driven by a high volume of cardiovascular surgeries and well-established reimbursement frameworks for advanced medical devices.
- Fastest Growing Region: Asia Pacific is anticipated to exhibit the highest CAGR due to expanding healthcare infrastructure, rising medical tourism, and an increasing prevalence of cardiovascular diseases in populous nations like China and India.
- Leading Segment by Product: The Closure Devices segment, particularly rigid plate fixation systems, dominates the market in terms of value, as healthcare providers move away from lower-cost stainless steel wires toward high-value titanium implants.
- Leading Segment by Procedure: Median Sternotomy remains the primary procedure type, accounting for the vast majority of surgical interventions requiring sternal closure systems globally.
- Material Innovation: Titanium and its alloys are the most widely utilized materials owing to their excellent biocompatibility, high strength-to-weight ratio, and MRI compatibility.
Key Takeaways Sternal Closure Systems Market Size & Forecast
The long-term outlook for the sternal closure systems market remains robust, underpinned by the unavoidable demographic shift toward an aging global population. As the incidence of coronary artery disease and valvular heart conditions increases, the demand for open-heart surgeries—and consequently, reliable sternal closure solutions—is expected to maintain a steady upward trajectory. Strategic focus is shifting toward value-based care, where the higher initial cost of rigid fixation systems is offset by the reduction in expensive readmissions and secondary corrective surgeries. Stakeholders are also observing a surge in personalized surgical approaches, including the use of 3D-printed templates to optimize the fit of sternal plates for individual patient anatomy.
- Market Valuation: The industry is set to nearly double its valuation by 2034, reflecting a consistent 6.2% CAGR as technology adoption reaches emerging markets.
- Strategic Focus: Minimizing the risk of Deep Sternal Wound Infection (DSWI) is the primary driver for technological upgrades in hospital procurement cycles.
- Dominant Country: The United States represents the single largest national market, characterized by early adoption of innovative plating systems and high healthcare expenditure per capita.
- Key Growth Catalyst: The rise in diabetic and obese patient populations, who are at higher risk for sternal instability, is accelerating the adoption of rigid fixation over traditional wiring.
- Supply Chain Dynamics: Increased localized manufacturing in the APAC region is expected to lower costs and increase the accessibility of advanced closure systems in developing economies.
Sternal Closure Systems Market Drivers Analysis
The primary growth engine for the sternal closure systems market is the rising global burden of cardiovascular diseases (CVDs). As coronary artery bypass grafting (CABG) remains a gold-standard treatment for complex heart disease, the necessity for secure sternal re-approximation is absolute. Additionally, the technological leap from flexible wiring to rigid plating has drastically improved patient outcomes, serving as a significant driver for market expansion in developed healthcare systems.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Cardiovascular Diseases | +2.1% | Global (High in APAC and MEA) | 2025 - 2034 |
| Shift Toward Rigid Fixation Over Traditional Wiring | +1.8% | North America and Europe | 2025 - 2030 |
| Growing Aging Population and Comorbidities | +1.5% | Japan, Germany, USA | 2025 - 2034 |
| Technological Advancements in Material Science (Titanium/PEEK) | +0.8% | Global | 2027 - 2034 |
Sternal Closure Systems Market Restraints Analysis
Despite the clinical benefits, the high cost associated with rigid sternal fixation systems compared to traditional stainless steel wires remains a substantial barrier to widespread adoption, particularly in cost-sensitive emerging markets. Furthermore, the increasing preference for minimally invasive cardiac surgeries (MICS), which avoid a full sternotomy altogether, poses a long-term threat to the total addressable market for sternal closure devices.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Advanced Rigid Fixation Systems | -1.2% | Latin America and Africa | 2025 - 2034 |
| Rise in Minimally Invasive Cardiac Procedures | -0.9% | Western Europe and USA | 2026 - 2034 |
| Limited Reimbursement in Developing Nations | -0.7% | Southeast Asia | 2025 - 2030 |
Sternal Closure Systems Market Opportunities Analysis
There is a significant opportunity for market players to develop cost-effective rigid fixation solutions tailored for mid-tier hospitals in emerging economies. Moreover, the integration of antibacterial coatings on closure hardware to proactively combat surgical site infections represents a high-growth niche. The expansion of ambulatory surgical centers performing cardiac procedures also opens a new channel for specialized, easy-to-apply closure kits.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Antibacterial Coated Implants | +1.4% | Global | 2027 - 2034 |
| Expansion into Emerging Markets (China, India, Brazil) | +2.3% | BRICS Nations | 2025 - 2034 |
| Customized 3D Printed Sternal Plates | +0.6% | USA and Germany | 2028 - 2034 |
Sternal Closure Systems Market Challenges Impact Analysis
The market faces challenges related to stringent and evolving regulatory requirements for Class II and Class III medical devices, which can delay product launches. Additionally, the learning curve associated with new rigid fixation techniques requires extensive surgeon training, which can slow down the implementation of newer systems in busy clinical environments.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Approval Processes | -0.5% | European Union (MDR), USA (FDA) | 2025 - 2028 |
| Surgeon Resistance to New Closure Techniques | -0.4% | Global | 2025 - 2030 |
| Complications Related to Sternal Dehiscence | -0.3% | Global | 2025 - 2034 |
Sternal Closure Systems Market - Updated Report Scope
The updated report provides a comprehensive examination of the sternal closure systems landscape, encompassing detailed quantitative and qualitative analyses across various product types, materials, and surgical procedures. It evaluates the impact of macroeconomic factors and healthcare policies on market dynamics from 2020 through the forecast end-point of 2034. The scope includes an in-depth assessment of the competitive environment, identifying key technological innovations and strategic maneuvers by leading industry participants.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.75 Billion |
| Market Forecast in 2034 | USD 4.76 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | DePuy Synthes (Johnson & Johnson), Zimmer Biomet, Stryker Corporation, KLS Martin Group, B. Braun Melsungen AG, Teleflex Incorporated, Orthofix Medical Inc., Arthrex Inc., Medtronic plc, Acumed LLC, Acute Innovations, Jace Medical, Kinamed Inc., IDEEV Medical, Jeil Medical Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The sternal closure systems market is segmented based on product type, material, procedure, and end-user. The closure devices segment is the primary contributor to market value, particularly as surgeons increasingly adopt rigid fixation systems consisting of plates and screws for patients with high-risk profiles. While stainless steel wires remain the most used product by volume due to their low cost and simplicity, the value-driven shift toward titanium plates is the most prominent trend in the segment. Material-wise, titanium is preferred for its biocompatibility and lower interference with diagnostic imaging. Hospitals remain the dominant end-user, accounting for the vast majority of sternotomy procedures performed worldwide.
- By Product Type: Closure Devices (Sternal Wires, Rigid Plate Fixation Systems, Cables, Clips), Bone Cement (Kryptonite, Glass Ionomer, etc.).
- By Material: Stainless Steel (Cost-effective), Titanium (Biocompatible, high strength), PEEK (Radiolucent, flexible).
- By Procedure: Median Sternotomy (Standard approach), Hemisternotomy (Partial approach), Bilateral Thoracosternotomy (Clamshell approach).
- By End-User: General and Specialty Hospitals, Cardiac Centers, Ambulatory Surgical Centers.
Regional Highlights
- North America: Dominates the market with over 35% share. The United States leads due to a high rate of obesity-related cardiac issues, premium pricing of medical devices, and rapid adoption of the latest rigid fixation technologies.
- Europe: Represents a significant market focused on clinical outcomes and cost-efficiency. Germany, France, and the UK are key contributors, with increasing regulatory focus via the Medical Device Regulation (MDR).
- Asia Pacific: The fastest-growing region with an expected CAGR exceeding 7.5%. Growth is fueled by China and India’s massive patient pools, increasing healthcare spending, and the expansion of private cardiac specialty hospitals.
- Latin America: Showing steady growth driven by healthcare modernization in Brazil and Mexico, though economic volatility remains a challenge for premium device penetration.
- Middle East & Africa: Emerging market with high growth potential in the Gulf Cooperation Council (GCC) countries due to increasing investments in specialized surgical infrastructure.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Sternal Closure Systems Market.- DePuy Synthes (Johnson & Johnson)
- Zimmer Biomet
- Stryker Corporation
- KLS Martin Group
- B. Braun Melsungen AG
- Teleflex Incorporated
- Orthofix Medical Inc.
- Arthrex Inc.
- Medtronic plc
- Acumed LLC
- Acute Innovations
- Jace Medical
- Kinamed Inc.
- IDEEV Medical
- Jeil Medical Corporation
- A&E Medical Corporation (Acquired by Zimmer Biomet)
- Abbott Laboratories
- Praesidia Srl
- Neos Surgery S.L.
Frequently Asked Questions
What is the projected market size of the Sternal Closure Systems Market by 2034?
The global sternal closure systems market is projected to reach approximately USD 4.76 Billion by 2034, growing at a steady CAGR of 6.2% from 2025.
Which product segment holds the largest share in the Sternal Closure Systems Market?
The Closure Devices segment, specifically rigid fixation systems including plates and screws, holds the largest share by value due to its superior clinical benefits over traditional wiring.
What are the primary factors driving the adoption of rigid sternal fixation?
Key drivers include the reduction in sternal dehiscence, lower rates of mediastinitis, faster patient recovery times, and better outcomes in high-risk patients such as those with diabetes or obesity.
Which region is expected to grow the fastest during the forecast period?
The Asia Pacific region is expected to be the fastest-growing market due to rising cardiovascular disease prevalence, improving healthcare access, and the expansion of medical tourism in the region.
Who are the leading players in the Sternal Closure Systems Market?
Leading companies include DePuy Synthes (J&J), Zimmer Biomet, Stryker, KLS Martin Group, and B. Braun Melsungen, who collectively dominate through continuous product innovation and global distribution networks.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
