Specialty Pulp Paper Chemicals Market
Specialty Pulp Paper Chemicals Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711147 | Published On : October 12, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Specialty Pulp Paper Chemicals Market Size
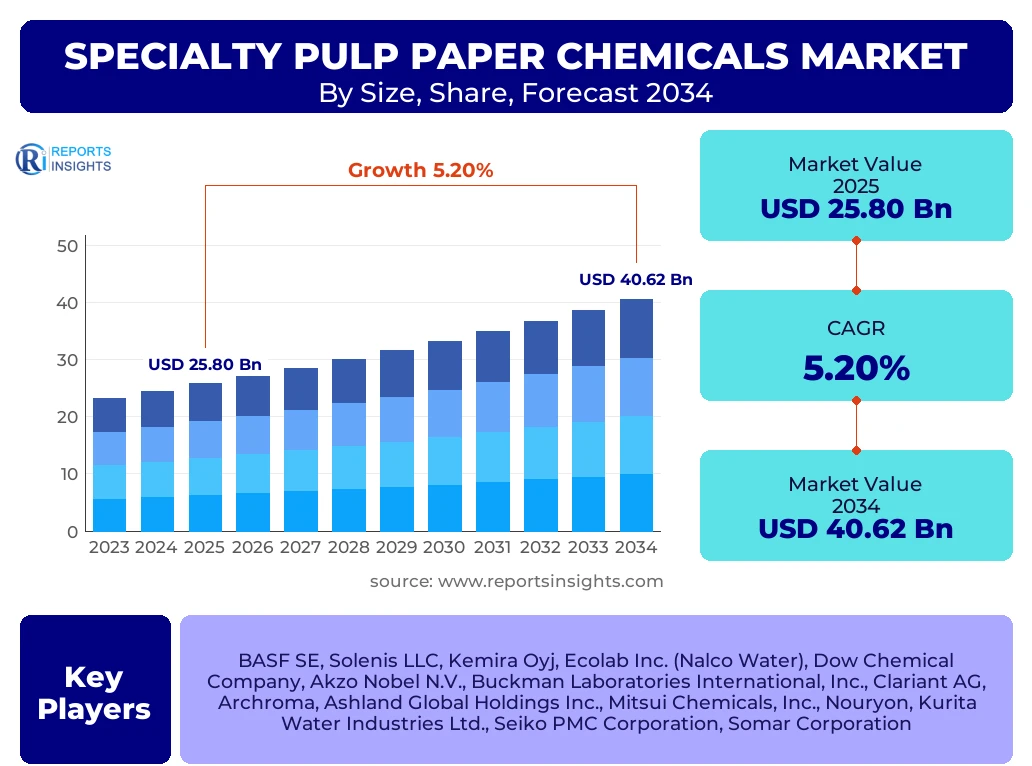
According to Reports Insights Consulting Pvt Ltd, The Specialty Pulp Paper Chemicals Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2025 and 2034. The market is estimated at USD 27.14 Billion in 2026 and is projected to reach USD 40.62 Billion by the end of the forecast period in 2034.
Key Specialty Pulp Paper Chemicals Market Trends & Insights
The global specialty pulp and paper chemicals industry is undergoing a significant transformation driven by the transition toward a circular economy and the replacement of single-use plastics with fiber-based alternatives. User queries regarding the market often center on the efficacy of bio-based barrier coatings and the regional shift of production hubs toward Southeast Asia. Current market trends indicate a robust pivot toward sustainability, where manufacturers are increasingly prioritizing chemicals that enhance recyclability and reduce the carbon footprint of paper production. Furthermore, the integration of digital monitoring systems within the chemical dosing process is gaining traction, allowing for real-time optimization of chemical consumption and waste reduction. Competitive benchmarking reveals that leading players are heavily investing in research and development to create PFAS-free grease-resistant agents and advanced retention aids that allow for higher fillers in paper, thereby reducing fiber costs.
- Asia-Pacific is the largest and fastest-growing region, driven by rapid industrialization and the expansion of the e-commerce packaging sector in China and India.
- The Functional Chemicals segment, particularly sizing and coating agents, holds the largest market share due to the rising demand for high-quality packaging and printing papers.
- Sustainable and bio-based chemical formulations are witnessing the highest CAGR as global environmental regulations become more stringent.
- The packaging and industrial paper segment remains the dominant end-user application, fueled by the global surge in logistics and delivery services.
Key Takeaways Specialty Pulp Paper Chemicals Market Size & Forecast
The market forecast for specialty pulp and paper chemicals remains optimistic, primarily supported by the resilient growth of the packaging and tissue paper sectors. Strategic analysis of user concerns suggests that stakeholders are highly focused on the regulatory landscape concerning chemical additives in food-contact materials. The market size expansion is underpinned by the increasing utilization of recycled fiber, which necessitates specialized process chemicals to manage contaminants and maintain paper strength. Consequently, the forecast period is expected to see a heightened demand for de-inking agents and biocides. Geographically, while North America and Europe are focusing on high-value specialty papers, the emerging economies are scaling up massive production capacities for containerboards and hygiene products, ensuring a balanced global demand profile.
- The global market is anticipated to surpass USD 40 Billion by 2034, reflecting steady demand in the hygiene and packaging sectors.
- China remains the leading country in both production and consumption of pulp and paper chemicals, followed closely by the United States.
- Process chemicals, including defoamers and biocides, are essential for operational efficiency in modern high-speed paper machines.
- Innovative barrier coatings that offer water and oil resistance without the use of plastics are the most significant growth opportunity in the functional chemicals category.
- The shift from traditional print media to digital has decreased the demand for newsprint chemicals but has been more than offset by the growth in corrugated packaging.
Specialty Pulp Paper Chemicals Market Drivers Analysis
The primary catalyst for the specialty pulp and paper chemicals market is the exponential growth of the e-commerce industry, which has maximized the demand for corrugated boxes and protective packaging. As consumers and corporations alike move away from plastic packaging, the reliance on high-performance paper products that require specialized strength and moisture-resistant chemicals has intensified. Additionally, the increasing standards for hygiene in developing nations have led to a surge in the production of tissue and towel products, which utilize significant amounts of softeners, debonders, and wet-strength resins. The industrial push for more efficient recycling processes also acts as a driver, as specialty chemicals are required to treat recycled pulp and ensure the quality of the final product meets commercial standards.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| E-commerce Expansion and Packaging Demand | +1.8% | Global (High in China/India) | 2025-2034 |
| Substitution of Single-use Plastics | +1.5% | European Union, North America | 2025-2030 |
| Rise in Hygiene Awareness and Tissue Production | +1.2% | Asia-Pacific, Latin America | 2025-2034 |
| Advancements in Recycled Fiber Processing | +0.7% | North America, Europe | 2026-2034 |
Specialty Pulp Paper Chemicals Market Restraints Analysis
Despite the positive growth trajectory, the market faces significant restraints, most notably the high volatility of raw material prices. Many specialty chemicals are derived from petrochemical feedstocks, making their cost structures sensitive to global oil price fluctuations. Furthermore, the pulp and paper industry is under intense scrutiny regarding its environmental impact, specifically concerning effluent discharge. Stringent regulations in regions like the European Union and North America regarding the chemical oxygen demand (COD) and biochemical oxygen demand (BOD) in wastewater necessitate expensive treatment solutions, which can limit the profit margins of chemical suppliers and paper mills. The ongoing decline in the global newsprint and graphic paper market also continues to act as a drag on the overall volume growth of certain chemical segments.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Petrochemical Feedstock Prices | -0.9% | Global | 2025-2034 |
| Stringent Effluent Disposal Regulations | -0.6% | Europe, North America | 2025-2034 |
| Decline in Graphic and Newsprint Paper | -0.5% | North America, Japan | 2025-2030 |
Specialty Pulp Paper Chemicals Market Opportunities Analysis
The most lucrative opportunities in the market lie in the development of "Green Chemistry" and high-performance barrier coatings. As brands seek to eliminate PFAS and other persistent chemicals from food packaging, the demand for innovative, biodegradable, and recyclable barrier solutions is skyrocketing. There is also a substantial opportunity in the field of nanocellulose, where chemical additives are used to enhance the properties of this next-generation material. Furthermore, the digitalization of the "Smart Mill" provides chemical companies with the chance to offer "Chemicals-as-a-Service," where they manage the entire chemical lifecycle for a mill using AI-driven dosing and monitoring systems, thereby creating more stable and long-term revenue streams through value-added services.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of PFAS-Free Barrier Coatings | +2.1% | Global (Food Packaging focus) | 2025-2034 |
| Bio-based and Renewable Chemical Agents | +1.4% | Europe, North America | 2026-2034 |
| Smart Chemical Dosing and AI Integration | +0.8% | Developed Economies | 2025-2034 |
Specialty Pulp Paper Chemicals Market Challenges Impact Analysis
One of the critical challenges for the specialty pulp and paper chemicals market is the increasing complexity of the recycling stream. As more diverse materials are added to the recycling bin, "stickies" and other contaminants become harder to manage, requiring more sophisticated and expensive chemical treatments. Additionally, the energy-intensive nature of both chemical production and paper manufacturing poses a challenge in a world increasingly focused on decarbonization. Ensuring that chemical solutions do not hinder the biodegradability of the final paper product is a persistent technical hurdle. Moreover, logistical challenges and disruptions in global supply chains can lead to localized shortages of critical chemicals, such as bleaching agents or specialized resins, affecting mill operations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Increasing Contaminants in Recycled Pulp | -0.7% | Global | 2025-2034 |
| Decarbonization Pressure in Chemical Manufacturing | -0.4% | Europe | 2027-2034 |
| Supply Chain Disruptions for Raw Materials | -0.3% | Global | 2025-2028 |
Specialty Pulp Paper Chemicals Market - Updated Report Scope
This report provides an exhaustive analysis of the global specialty pulp and paper chemicals market, covering the technical performance, market dynamics, and competitive landscape. The scope includes a detailed breakdown of chemical types ranging from functional additives to process aids, with a focus on their application in various paper grades. The analysis incorporates the impact of macroeconomic factors, regulatory changes, and technological shifts on the market's growth trajectory from 2025 to 2034. By examining the value chain from raw material suppliers to end-use industries like packaging, tissue, and printing, this report offers a holistic view of the market's future.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 25.80 Billion |
| Market Forecast in 2034 | USD 40.62 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Solenis LLC, Kemira Oyj, Ecolab Inc. (Nalco Water), Dow Chemical Company, Akzo Nobel N.V., Buckman Laboratories International, Inc., Clariant AG, Archroma, Ashland Global Holdings Inc., Mitsui Chemicals, Inc., Nouryon, Kurita Water Industries Ltd., Seiko PMC Corporation, Somar Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the specialty pulp and paper chemicals market reflects the diverse requirements of modern papermaking, where chemicals are categorized based on their primary role in either enhancing the final product's properties or facilitating the manufacturing process. Functional chemicals represent the larger segment by value, as they directly influence characteristics such as water resistance, brightness, and strength, which are critical for high-end packaging and specialty papers. Process chemicals, while used in smaller volumes, are indispensable for maintaining machine speed, preventing biological growth, and ensuring the cleanliness of the production system, particularly in mills using closed-loop water systems or high percentages of recycled fiber.
- Functional Chemicals:
- Sizing Agents (Internal and Surface Sizing)
- Coating Binders and Additives
- Wet-Strength and Dry-Strength Resins
- Dyes and Optical Brighteners
- Fillers and Pigments
- Process Chemicals:
- Defoamers and Antifoams
- Biocides and Slimicides
- Retention and Drainage Aids
- De-inking Agents for Recycled Pulp
- Scale Inhibitors and Chelating Agents
- By Application:
- Packaging & Industrial (Corrugated boxes, Cartons, Flexible packaging)
- Printing & Writing (Office paper, Magazines, Books)
- Tissue & Towel (Toilet tissue, Paper towels, Napkins)
- Specialty Paper (Label paper, Filter paper, Release liners)
Regional Highlights
- Asia-Pacific: The region stands as the dominant market leader both in terms of value and volume. China, India, and Southeast Asian nations are witnessing massive investments in new paper machines. The region is the fastest-growing due to the explosive growth of the domestic e-commerce market and the relocation of manufacturing bases from the West.
- North America: A mature market focused on innovation in specialty papers and high-performance packaging. The region is a leader in the development of bio-based chemicals and holds a significant share in the tissue and towel segment.
- Europe: Driven by the world's most stringent environmental regulations, Europe is the pioneer in "Green Chemistry" for papermaking. There is a high demand for chemicals that facilitate 100% recyclability and plastic-free barrier solutions.
- Latin America: Brazil is a major hub for pulp production, which drives the demand for bleaching and pulping chemicals. The domestic tissue market is also expanding rapidly across the region.
- Middle East & Africa: A developing market where growth is tied to the increasing demand for hygiene products and the establishment of local packaging production to reduce import reliance.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Specialty Pulp Paper Chemicals Market.- BASF SE
- Solenis LLC
- Kemira Oyj
- Ecolab Inc. (Nalco Water)
- Dow Chemical Company
- Akzo Nobel N.V.
- Buckman Laboratories International, Inc.
- Clariant AG
- Archroma
- Ashland Global Holdings Inc.
- Mitsui Chemicals, Inc.
- Nouryon
- Kurita Water Industries Ltd.
- Seiko PMC Corporation
- Somar Corporation
- Evonik Industries AG
- Snf Floerger
- Chevron Phillips Chemical Company
Frequently Asked Questions
What are specialty pulp and paper chemicals?
Specialty pulp and paper chemicals are a group of specialized chemical additives used in the papermaking process to enhance the physical and aesthetic properties of paper or to improve the efficiency of the manufacturing process. These include functional chemicals like sizing agents and coatings, as well as process chemicals like defoamers and biocides.
What is the projected growth rate of the market from 2025 to 2034?
The market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% during the forecast period, reaching an estimated value of USD 40.62 Billion by 2034.
Which segment holds the largest share in the specialty pulp and paper chemicals market?
The Functional Chemicals segment holds the largest market share, as these chemicals are essential for providing the specific characteristics required for packaging, printing, and specialty paper grades.
How is the shift away from plastic impacting this market?
The shift away from single-use plastics is a major growth driver. It has created a massive demand for paper-based packaging that requires specialty barrier chemicals to provide water, grease, and moisture resistance that paper does not naturally possess.
Which region is expected to lead the market growth?
Asia-Pacific is expected to lead the market growth due to its massive production capacity, increasing industrialization, and the rapid expansion of the e-commerce and hygiene product sectors in countries like China and India.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
