Specialty Insurance Market
Specialty Insurance Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711886 | Published On : November 20, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Specialty Insurance Market Size
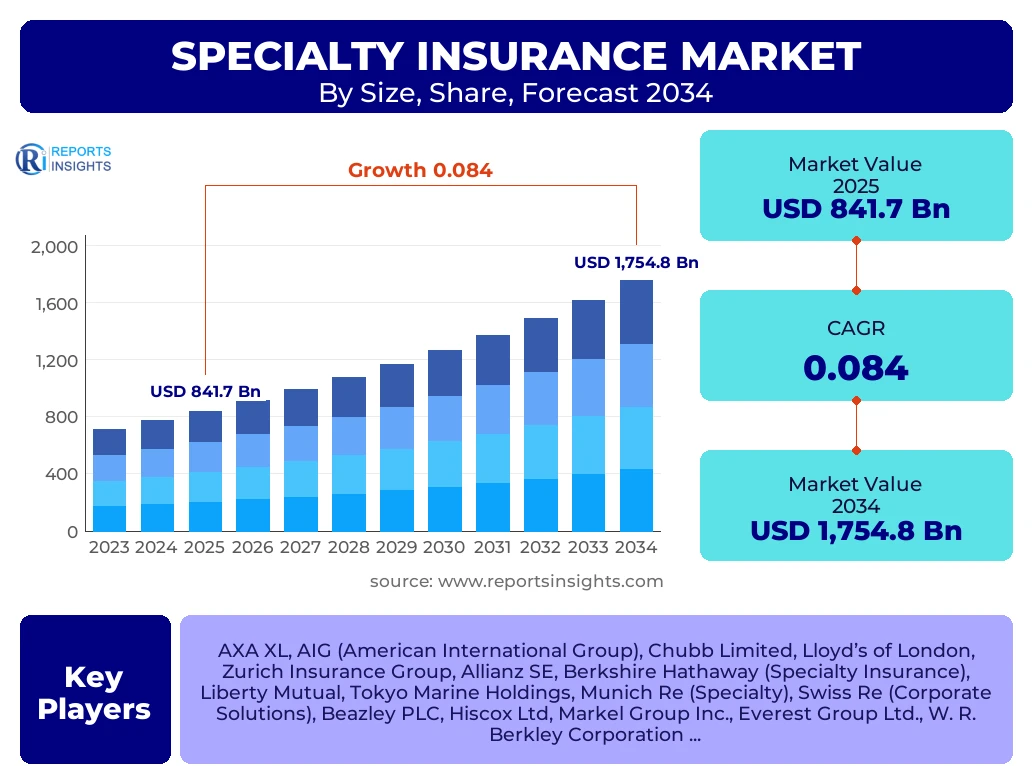
According to Reports Insights Consulting Pvt Ltd, The Specialty Insurance Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.4% between 2025 and 2034. The market is estimated at USD 912.4 Billion in 2026 and is projected to reach USD 1,754.8 Billion by the end of the forecast period in 2034.
Key Specialty Insurance Market Trends & Insights
The specialty insurance landscape is currently undergoing a structural transformation driven by the escalating complexity of global risks that fall outside the parameters of standard multi-peril policies. Market participants are increasingly focusing on niche underwriting capabilities to address high-volatility risks such as cyber warfare, climate-induced catastrophic events, and supply chain disruptions. In the current fiscal climate, regional insights indicate that North America maintains its position as the primary revenue generator due to a highly sophisticated corporate risk environment and a robust legal landscape that necessitates comprehensive professional liability and D&O coverage. Concurrently, the Asia-Pacific region is emerging as the fastest-growing geographical segment, fueled by rapid industrialization, infrastructure development, and an increasing awareness of environmental and marine liability risks among emerging economies.
Technological integration remains a pivotal trend, with the adoption of predictive analytics and real-time data monitoring allowing insurers to refine risk pricing models. The shift toward parametric insurance—where payouts are triggered by specific predefined parameters rather than traditional loss adjustment—is gaining significant traction in the catastrophe and weather-related specialty segments. Furthermore, competitive benchmarking reveals that leading insurers are diversifying their portfolios into specialized renewable energy and green technology insurance to capitalize on the global energy transition. This evolution reflects a broader trend of moving away from standardized products toward bespoke, high-value coverage solutions that offer greater resilience against non-traditional threats.
- Largest Region: North America continues to lead the global market, accounting for a substantial share of total premiums due to the maturity of its financial and legal sectors.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR through 2034, driven by increasing insurance penetration in China, India, and Southeast Asia.
- Largest Segment by Share: Commercial Specialty lines, particularly Marine, Aviation, and Transport (MAT), currently dominate the market volume.
- Digital Transformation: The integration of InsurTech solutions is significantly reducing underwriting cycle times and improving loss ratio accuracy across niche segments.
- ESG Integration: Environmental, Social, and Governance factors are becoming central to underwriting guidelines, particularly in energy and construction specialty lines.
Key Takeaways Specialty Insurance Market Size & Forecast
The specialty insurance market is poised for a decade of sustained growth as corporate and industrial entities seek protection against increasingly idiosyncratic and systemic risks. The forecast period between 2025 and 2034 reflects a transition from traditional capacity-driven markets to insight-driven markets. Key takeaways suggest that the market’s expansion will be heavily influenced by the professional lines segment, including Directors and Officers (D&O) and Cyber liability, which are responding to heightened regulatory scrutiny and the digitization of global commerce. Additionally, the increasing frequency of secondary peril events—such as wildfires and floods—is driving demand for specialized property coverage that standard carriers are often reluctant to underwrite, thereby shifting volume toward specialty and excess and surplus (E&S) markets.
Strategic positioning within the market is favoring firms that possess deep technical expertise in specific industries, such as offshore energy, aerospace, and clinical trials. The convergence of reinsurance capital with specialty primary insurance is also stabilizing the market's capacity, though pricing remains sensitive to macroeconomic shifts and inflationary pressures on claims costs. For stakeholders, the focus is shifting toward long-term risk partnership models rather than transactional policy issuance, ensuring that coverage remains relevant even as the underlying risk profile of the insured evolves. This period of the forecast highlights a significant capital inflow into the specialty sector, as traditional lines face commoditization and lower margins.
- Leading Country: The United States remains the most significant individual market, characterized by a deep E&S market and complex litigation risks.
- Market Driver: The escalation of cyber-attacks and the necessity for comprehensive data breach coverage are primary catalysts for market expansion.
- Forecast Milestone: The market is expected to cross the USD 1 Trillion threshold by 2028, signaling a major shift in the global insurance product mix.
- Segment Growth: Cyber insurance is anticipated to be the fastest-growing sub-segment within the specialty category over the forecast horizon.
- Capital Concentration: Lloyd’s of London and major global carriers are consolidating their specialty divisions to enhance underwriting discipline and capital efficiency.
Specialty Insurance Market Drivers Analysis
The primary growth engine for the specialty insurance sector is the fundamental shift in the global risk landscape, where traditional policies can no longer cover the intricacies of modern commerce. Drivers such as the digital transformation of industries, the transition to sustainable energy sources, and the heightening of international regulatory requirements are compelling businesses to seek specialized risk transfer mechanisms. This demand is further amplified by the increasing frequency of "gray swan" events that require non-standard policy wordings and flexible underwriting approaches.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Global Cyber Threats | +2.8% | Global / North America | 2025-2034 |
| Energy Transition & Renewable Projects | +1.9% | Europe / Asia-Pacific | 2026-2034 |
| Infrastructure & Mega-Project Spending | +1.5% | United States / China / MEA | 2025-2030 |
| Increased Litigation & Social Inflation | +1.2% | United States / UK | 2025-2034 |
Specialty Insurance Market Restraints Analysis
Despite the positive growth outlook, the specialty insurance market faces significant restraints, primarily stemming from high capital requirements and the extreme volatility of niche risks. Regulatory complexities across different jurisdictions often limit the speed at which new specialty products can be brought to market. Furthermore, the rising cost of reinsurance—which specialty carriers rely on heavily—can squeeze profit margins and force insurers to limit their capacity in high-risk zones, potentially slowing overall market momentum during periods of financial instability.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Compliance | -1.1% | European Union / India | 2025-2034 |
| High Reinsurance Premium Costs | -0.8% | Global | 2025-2028 |
| Underwriting Talent Shortage | -0.5% | UK / USA | 2026-2032 |
Specialty Insurance Market Opportunities Analysis
The emergence of new economic sectors and the evolution of technology present substantial opportunities for specialty insurers to capture untapped premiums. Parametric insurance solutions represent a frontier for growth, particularly in developing regions where traditional claims adjustment infrastructure is lacking. Additionally, the focus on Small and Medium Enterprises (SMEs) that now face enterprise-level risks (like cyber or international liability) offers a vast, underserved market segment that requires simplified, yet specialized, insurance solutions tailored to their specific operational scale.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Parametric Insurance Models | +2.1% | Latin America / SE Asia | 2026-2034 |
| SME Specialized Cyber Policies | +1.7% | Germany / Japan / USA | 2025-2034 |
| AI-Driven Niche Underwriting | +1.4% | Global | 2027-2034 |
Specialty Insurance Market Challenges Impact Analysis
Specialty insurers are increasingly challenged by the unpredictability of climate-related risks and the phenomenon of social inflation, where court awards for damages far exceed economic losses. These factors create "long-tail" liabilities that are difficult to price accurately, often leading to sudden reserve adjustments. Additionally, the global geopolitical climate, characterized by trade tensions and localized conflicts, complicates the risk assessment for marine, aviation, and political risk segments, requiring constant vigilance and real-time policy adjustments.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Climate Volatility & Catastrophe Modeling | -1.5% | Coastal Regions / Global | 2025-2034 |
| Social Inflation & Litigation Costs | -1.2% | United States | 2025-2034 |
| Geopolitical Instability | -0.9% | Middle East / Eastern Europe | 2025-2030 |
Specialty Insurance Market - Updated Report Scope
This comprehensive market report provides a granular analysis of the global specialty insurance landscape, covering both established lines and emerging risk categories. The scope encompasses detailed revenue projections, competitive positioning, and a thorough assessment of the macroeconomic factors influencing premium pricing and underwriting capacity. By analyzing various segments such as Marine, Aviation, Construction, and Cyber, the report offers stakeholders a clear roadmap for strategic investment and portfolio diversification over the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 841.7 Billion |
| Market Forecast in 2034 | USD 1,754.8 Billion |
| Growth Rate | 8.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | AXA XL, AIG (American International Group), Chubb Limited, Lloyd’s of London, Zurich Insurance Group, Allianz SE, Berkshire Hathaway (Specialty Insurance), Liberty Mutual, Tokyo Marine Holdings, Munich Re (Specialty), Swiss Re (Corporate Solutions), Beazley PLC, Hiscox Ltd, Markel Group Inc., Everest Group Ltd., W. R. Berkley Corporation, Arch Capital Group, Travelers Companies, Inc., Sompo Holdings, Fairfax Financial (Crum & Forster). |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The specialty insurance market is segmented based on the specific nature of the risk and the unique underwriting requirements of the insured entity. This segmentation allows for a deeper understanding of premium flows and risk concentration across various industries. The primary division exists between Commercial Specialty, which covers industrial and corporate risks, and Professional Specialty, which focuses on liability and management exposures. The emergence of Cyber and Environmental lines as standalone segments highlights the market's responsiveness to evolving modern threats.
- By Type:
- Marine, Aviation, and Transport (MAT): Covers cargo, hull, and liability for international logistics and aerospace sectors.
- Cyber Insurance: Addresses data breaches, ransomware, and business interruption resulting from cyber-attacks.
- Directors and Officers (D&O): Provides protection for management teams against legal actions related to corporate governance.
- Energy and Power: Focuses on both traditional fossil fuel infrastructure and new renewable energy projects (wind, solar).
- Construction and Engineering: Specialized coverage for large-scale infrastructure projects and technical delays.
- By Distribution Channel:
- Brokers: The dominant channel for specialty lines, utilizing high-level expertise to navigate complex global markets.
- Direct/Digital: An emerging channel focusing on standardized specialty products for the SME sector.
- By End-User:
- Commercial: Focuses on industrial giants and mid-market firms requiring high-limit coverage.
- SME: A high-growth segment looking for affordable, modular specialty protection.
Regional Highlights
North America currently serves as the largest market for specialty insurance, driven by the sheer scale of its corporate sector and a legal environment that generates high demand for professional and liability coverage. The United States market is particularly noted for its Excess and Surplus (E&S) lines, which provide the flexibility required to underwrite high-risk or unique business activities that standard insurers avoid. Regulatory clarity and a concentration of global underwriting hubs in cities like New York further solidify its leadership position.
The Asia-Pacific region is recognized as the fastest-growing market, with a projected CAGR that outpaces both Europe and North America. This growth is underpinned by massive investments in infrastructure across China and India, alongside an expanding middle class that is driving demand for specialized personal and commercial insurance. Furthermore, as Asian companies expand their global footprints, their exposure to international liabilities is creating a surge in demand for sophisticated specialty products. Europe remains a key center for the market, particularly the UK, home to Lloyd’s of London, which remains the global epicenter for specialty underwriting expertise and capacity.
- North America: Leading market share; driven by professional liability, cyber, and the robust E&S market structure.
- Europe: Hub of technical expertise; dominated by London and Bermuda-based insurers with a focus on global reinsurance and MAT lines.
- Asia-Pacific: Fastest growth; fueled by renewable energy projects, maritime trade in the Singapore-Hong Kong corridor, and increasing regulatory standards.
- Middle East & Africa: Increasing relevance in the energy and construction sectors, particularly with the rise of mega-projects in the GCC countries.
- Latin America: Growing interest in agricultural and catastrophe-related specialty lines as a response to climate variability.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Specialty Insurance Market.- AXA XL
- AIG (American International Group)
- Chubb Limited
- Lloyd’s of London
- Zurich Insurance Group
- Allianz SE
- Berkshire Hathaway Specialty Insurance
- Liberty Mutual Insurance
- Tokio Marine Holdings
- Munich Re
- Swiss Re Corporate Solutions
- Beazley PLC
- Hiscox Ltd
- Markel Group Inc.
- Everest Group Ltd.
- W. R. Berkley Corporation
- Arch Capital Group
- The Travelers Companies, Inc.
- Sompo Holdings
- Fairfax Financial
Frequently Asked Questions
Comprehensive analysis of user queries regarding the Specialty Insurance market and summarized answers reflecting current industry dynamics.
What defines the Specialty Insurance market compared to standard insurance?
Specialty insurance covers unique, complex, or high-hazard risks that standard insurance providers typically do not cover. It requires bespoke underwriting, higher technical expertise, and often higher premiums to account for the volatility and specialized nature of the risk, such as marine liability or professional indemnity for niche industries.
Why is the Cyber Insurance segment growing so rapidly?
The growth is driven by the increasing frequency and severity of cyber-attacks, including ransomware and data breaches, coupled with strict global data protection regulations (like GDPR). Businesses now view cyber risk as a core operational threat, necessitating specialized coverage that includes forensic assistance and legal defense costs.
How does North America maintain its dominance in this market?
North America benefits from a highly litigious environment and a sophisticated corporate risk management culture. The presence of a well-defined Excess and Surplus (E&S) market allows for the rapid deployment of capital into non-standard risks, making it the global leader in professional and commercial liability premiums.
What is the role of brokers in the Specialty Insurance sector?
Brokers are essential intermediaries because specialty risks are not easily commoditized. They provide the necessary technical consulting to help clients understand their exposures and negotiate customized policy wordings with underwriters who have the specific expertise and capital to cover those risks.
How is climate change affecting specialty insurance underwriting?
Climate change is increasing the frequency of natural catastrophes, which forces specialty insurers to refine their catastrophe modeling. This has led to the rise of parametric insurance, where payouts are based on weather triggers rather than manual loss assessments, and has significantly increased the demand for environmental liability coverage.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
