Seeds Market
Seeds Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711485 | Published On : November 03, 2026 |
Format : 


 | Author : Shawn Patel
Seeds Market Size
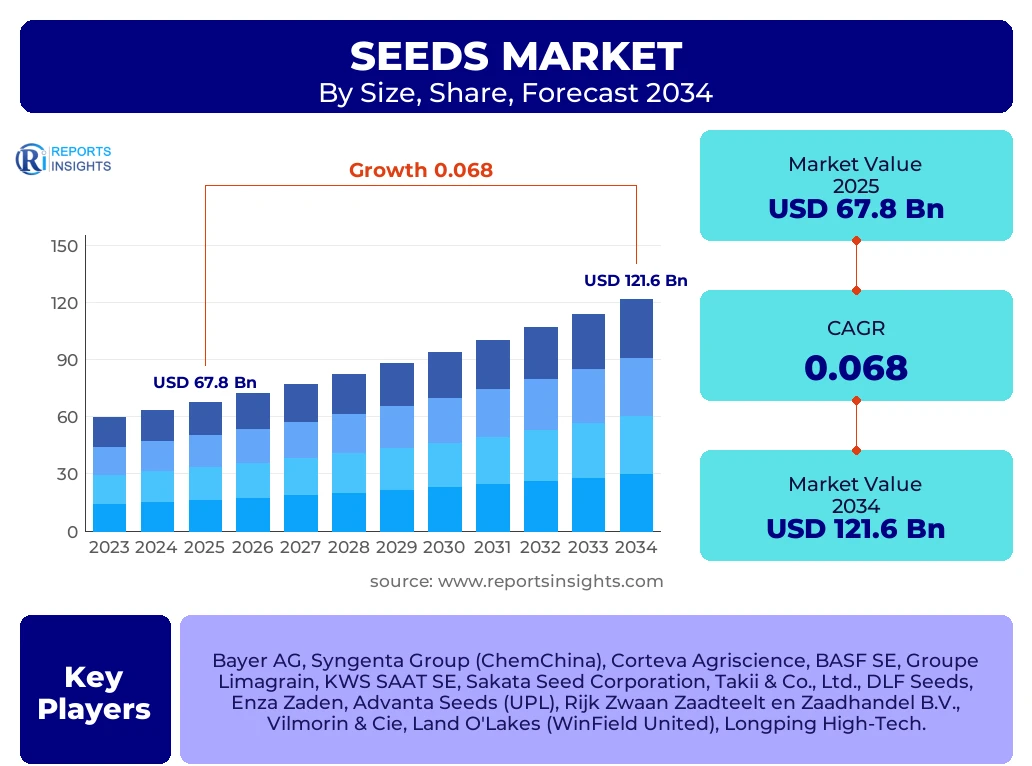
According to Reports Insights Consulting Pvt Ltd, The Seeds Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2025 and 2034. The market is estimated at USD 72.4 Billion in 2026 and is projected to reach USD 121.6 Billion by the end of the forecast period in 2034.
Key Seeds Market Trends & Insights
The global agricultural landscape is undergoing a radical transformation driven by the necessity for higher yields amidst shrinking arable land and volatile climatic conditions. Modern seed technology has transitioned from basic selective breeding to advanced genomic editing and biotechnology. Current market intelligence indicates a significant pivot toward biological seed treatments and the integration of digital farming tools that optimize planting density and trait selection. Stakeholders are increasingly focusing on specialized vegetable seeds and hybrid varieties that offer resilience against biotic and abiotic stressors, ensuring food security for an expanding global population.
- Largest Region: North America remains the dominant market shareholder due to the widespread adoption of genetically modified (GM) crops and high levels of mechanization.
- Fastest Growing Region: Asia-Pacific is witnessing the highest CAGR, propelled by rapid urbanization in India and China, alongside government initiatives to modernize traditional farming practices.
- Leading Segment by Type: Oilseeds and pulses represent the largest segment in terms of market value, driven by the global demand for plant-based proteins and vegetable oils.
- Dominant Segment by Trait: Herbicide-tolerant seeds continue to hold the majority share as they simplify weed management and reduce labor costs for large-scale operations.
Key Takeaways Seeds Market Size & Forecast
The trajectory of the seeds market is defined by a consistent upward momentum, reflecting the critical role of high-quality germplasm in the global food value chain. Market analysts highlight that the transition from farm-saved seeds to commercialized, high-yielding varieties is a primary catalyst for growth in developing economies. Furthermore, the forecast period suggests a narrowing gap between conventional and biotech seed segments as regulatory frameworks in various regions become more receptive to gene-editing technologies like CRISPR-Cas9, which offer precise modifications without the complexities of traditional transgenic methods.
- The global demand for corn (maize) and soybean seeds is expected to account for over 50% of the total seed market revenue through 2034.
- Brazil and Argentina are emerging as critical hubs for GM seed expansion, particularly in the soybean and cotton verticals.
- Sustainability mandates are driving the development of drought-resistant and nitrogen-efficient seed varieties to combat the effects of climate change.
- Small-to-medium enterprises (SMEs) are finding niche opportunities in organic and heirloom seed segments as consumer preferences shift toward non-GMO and specialty produce.
- The integration of "Seed-as-a-Service" models by major players is fostering long-term loyalty through bundled offerings of seeds, chemicals, and digital insights.
Seeds Market Drivers Analysis
The primary engines of growth in the seed industry are multifaceted, ranging from technological breakthroughs in plant breeding to macroeconomic shifts in dietary habits. As the global population nears 9 billion by the mid-century, the pressure to produce more calories per hectare has never been greater. This urgency is manifesting in increased R&D investments by private firms and public institutions alike, focusing on trait development that maximizes photosynthetic efficiency and nutrient uptake. Additionally, the industrial application of crops—such as corn for biofuels and soybeans for livestock feed—creates a robust, non-seasonal demand floor for high-performance seeds.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Biotech & GM Traits | +2.1% | United States, Brazil, Argentina | 2025 - 2034 |
| Rising Demand for Plant-Based Proteins | +1.5% | Global (High in Europe & APAC) | 2026 - 2030 |
| Government Subsidies for Certified Seeds | +1.2% | India, China, Sub-Saharan Africa | 2025 - 2034 |
| Climate Adaptation Requirements | +0.9% | Australia, Middle East, Africa | 2027 - 2034 |
Seeds Market Restraints Analysis
Despite robust growth prospects, the market faces significant headwinds, primarily from stringent regulatory hurdles and intellectual property (IP) challenges. The development of a new biotech seed trait can cost upwards of USD 100 million and take over a decade to reach commercialization, making the industry highly capital-intensive. Furthermore, localized resistance to genetically modified organisms (GMOs) in parts of the European Union and certain African nations limits market penetration. Counterfeit seeds and the persistence of informal seed systems in developing regions also undermine the revenue potential of organized players.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent GMO Regulations | -1.4% | European Union, Russia | 2025 - 2034 |
| High R&D and Compliance Costs | -0.8% | Global (Impacts Mid-sized firms) | 2025 - 2029 |
| Counterfeit Seed Proliferation | -0.5% | India, Southeast Asia, Africa | 2025 - 2034 |
Seeds Market Opportunities Analysis
The evolution of the "Smart Farm" presents a significant opportunity for seed companies to diversify their revenue streams. By embedding digital identifiers or biological coatings that interact with precision agriculture sensors, seed manufacturers can provide real-time performance data to farmers. Moreover, the surging interest in regenerative agriculture opens doors for cover crop seeds and varieties specifically bred for no-till farming systems. The expansion of indoor vertical farming also necessitates the development of specialized "dwarf" or fast-maturing vegetable varieties tailored for controlled environment agriculture (CEA).
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion in Controlled Environment Agriculture (CEA) | +1.8% | Japan, Singapore, Netherlands, USA | 2026 - 2034 |
| Development of Gene-Edited (Non-GMO) Crops | +1.4% | Global (Especially Europe) | 2027 - 2034 |
| Biological Seed Treatment Integration | +1.1% | Brazil, USA, Germany | 2025 - 2032 |
Seeds Market Challenges Impact Analysis
Maintaining genetic diversity while maximizing yield remains a paradoxical challenge for the industry. The reliance on a narrow range of high-performing hybrids increases the vulnerability of global food systems to unforeseen pathogens or pests, such as the spread of Fall Armyworm or Wheat Rust. Additionally, logistics and supply chain disruptions, exacerbated by geopolitical tensions, pose risks to the timely distribution of seasonal seeds. Intellectual property disputes between global giants and domestic firms in emerging markets also create a litigious environment that can stall innovation.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Loss of Genetic Biodiversity | -0.7% | Global | Long-term |
| Geopolitical Trade Disruptions | -0.9% | Ukraine, Russia, China-USA Trade | 2025 - 2028 |
| Climate-Induced Planting Window Shifts | -0.6% | Australia, North America | 2025 - 2034 |
Seeds Market - Updated Report Scope
This report provides an exhaustive analysis of the global seeds industry, covering both conventional and biotechnological advancements. It evaluates the impact of macro-economic factors, technological disruptions, and evolving regulatory landscapes on the market's trajectory through 2034. The scope includes a granular breakdown of crop types, trait segments, and treatment modalities across all major geographical regions, providing stakeholders with actionable intelligence to navigate the competitive environment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 67.8 Billion |
| Market Forecast in 2034 | USD 121.6 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Bayer AG, Syngenta Group (ChemChina), Corteva Agriscience, BASF SE, Groupe Limagrain, KWS SAAT SE, Sakata Seed Corporation, Takii & Co., Ltd., DLF Seeds, Enza Zaden, Advanta Seeds (UPL), Rijk Zwaan Zaadteelt en Zaadhandel B.V., Vilmorin & Cie, Land O'Lakes (WinField United), Longping High-Tech. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The seeds market is characterized by complex segmentation, reflecting the diverse requirements of different agro-climatic zones and industrial needs. The cereals and grains segment, dominated by corn, wheat, and rice, remains the backbone of the industry due to its role in basic human nutrition. However, the fruit and vegetable segment is experiencing rapid value growth as consumer health consciousness drives demand for year-round fresh produce. From a trait perspective, the "Stacked Traits" segment—which combines herbicide tolerance and insect resistance—is becoming the industry standard in the Americas to provide comprehensive crop protection with fewer chemical applications.
- By Type:
- Cereals & Grains (Corn, Rice, Wheat, Sorghum, Barley)
- Oilseeds & Pulses (Soybean, Sunflower, Canola, Cotton, Pea, Lentil)
- Fruits & Vegetables (Tomato, Onion, Cabbage, Pepper, Melon, Leafy Greens)
- Other Crops (Forage, Alfalfa, Turf and Ornamental)
- By Trait:
- Herbicide-Tolerant (HT)
- Insect-Resistant (IR)
- Stacked Traits (Combining HT and IR)
- Abiotic Stress Tolerance (Drought/Salinity Resistance)
- Conventional/Non-Biotech
- By Seed Treatment:
- Chemical Treatments (Fungicides, Insecticides)
- Biological Treatments (Microbials, Biostimulants)
- Physical Treatments (Priming, Pelleting, Coating)
- By Sales Channel:
- Direct Sales (B2B/Enterprise Farming)
- Retail Outlets & Distributors
- E-commerce & Digital Platforms
Regional Highlights
The regional distribution of the seeds market reveals a clear divide between high-tech biotech adopters and regions focusing on hybrid conventional seeds. North America leads the market, underpinned by a highly sophisticated R&D ecosystem and the presence of industry titans. Latin America, particularly Brazil, has emerged as a global powerhouse for soybean and corn production, utilizing advanced biotech traits to enable double-cropping (Safrinha). In contrast, the European market is characterized by a strong emphasis on non-GMO and organic seed production, with countries like France and Germany leading in seed export value. The Asia-Pacific region represents the most significant growth opportunity, with China and India implementing structural reforms to professionalize their seed sectors and reduce reliance on imports.
- North America: The largest market share holder, with the United States leading in corn and cotton seed innovation. High adoption of precision planting technologies.
- Asia-Pacific: The fastest-growing region. Driven by large-scale government investments in "Seed Silos" and modernized breeding techniques in China and India.
- Latin America: High penetration of GM seeds. Brazil is the primary driver, followed by Argentina, focusing on export-oriented crop cycles.
- Europe: Leading the world in vegetable seed innovation and non-GMO trait development. Focus on sustainability and biodiversity.
- Middle East & Africa: Growing focus on drought-resistant cereal varieties and the expansion of commercial vegetable farming in North Africa.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Seeds Market.- Bayer AG (Crop Science Division)
- Syngenta Group (A subsidiary of ChemChina)
- Corteva Agriscience
- BASF SE (Agricultural Solutions)
- Groupe Limagrain
- KWS SAAT SE & Co. KGaA
- Sakata Seed Corporation
- Takii & Co., Ltd.
- DLF Seeds A/S
- Enza Zaden
- Advanta Seeds (UPL Group)
- Rijk Zwaan Zaadteelt en Zaadhandel B.V.
- Vilmorin & Cie
- Land O'Lakes (WinField United)
- Yuan Longping High-Tech Agriculture Co., Ltd.
- Bejo Zaden B.V.
- Canterra Seeds
- Mahyco Private Limited
- Stine Seed Company
- Innoseeds
Frequently Asked Questions
What is the current and projected size of the global Seeds Market?
The global seeds market is estimated to be valued at USD 72.4 Billion in 2026 and is anticipated to reach approximately USD 121.6 Billion by 2034, growing at a CAGR of 6.8%.
Which region is expected to show the highest growth rate during the forecast period?
The Asia-Pacific region is projected to exhibit the highest CAGR due to increasing agricultural industrialization, government support for high-yielding varieties, and the adoption of modern farming practices in India and China.
What are the primary factors driving the demand for genetically modified (GM) seeds?
The primary drivers include the need for enhanced crop protection against pests and weeds, the demand for higher yields to ensure food security, and the ability of GM seeds to withstand extreme climate conditions like drought.
Who are the dominant players in the global Seeds Market?
The market is led by major biotechnology and agricultural firms including Bayer AG, Syngenta (ChemChina), Corteva Agriscience, and BASF SE, which collectively control a significant portion of the global germplasm and trait IP.
How is CRISPR technology impacting the seeds industry?
CRISPR-Cas9 allows for precise gene editing without introducing foreign DNA, potentially allowing these seeds to bypass the heavy regulations associated with traditional GMOs, thereby speeding up the time-to-market for new traits.
Author
S
Shawn Patel is a Manger Agriculture Research Industry with 6+ years of experience in the Agriculture Industry. He specializes in agricultural market intelligence, crop production analysis, agribusiness trend assessment, demand forecasting, competitive benchmarking, supply chain evaluation, precision agriculture technologies, commodity pricing analysis, and market sizing across farming and agricultural input sectors. His research combines industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, understand evolving market trends, and strengthen their competitive positioning in the global agriculture industry.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
