Seasonings Market
Seasonings Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711407 | Published On : October 31, 2026 |
Format : 


 | Author : Hameer Thakur
Seasonings Market Size
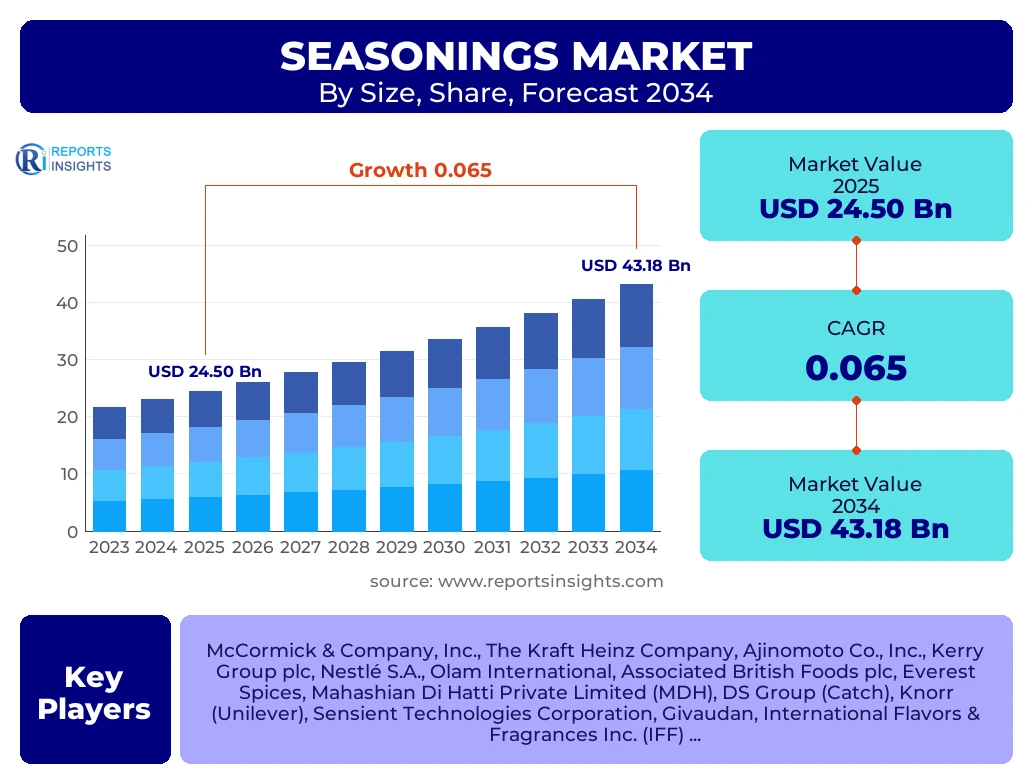
According to Reports Insights Consulting Pvt Ltd, The Seasonings Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.5% between 2025 and 2034. The market is estimated at USD 25.92 Billion in 2026 and is projected to reach USD 43.18 Billion by the end of the forecast period in 2034.
Key Seasonings Market Trends & Insights
The global seasonings landscape is undergoing a radical transformation driven by the intersection of health-conscious consumption and the democratization of global culinary traditions. Modern consumers are increasingly moving away from synthetic flavor enhancers in favor of clean-label, organic, and non-GMO spice profiles. This shift is particularly evident in the rapid rise of "functional seasonings," where ingredients like turmeric, ginger, and garlic are marketed not just for their flavor but for their perceived anti-inflammatory and immunity-boosting properties. Furthermore, the industry is witnessing a "premiumization" trend, where artisanal salts and single-origin spices are capturing significant market share among high-income demographics seeking authenticity and transparency in the supply chain.
Digitalization and the explosion of direct-to-consumer (DTC) brands have decentralized the market, allowing smaller players to challenge established giants by catering to niche flavor profiles such as African Peri-Peri or Middle Eastern Za'atar. Large-scale manufacturers are responding by acquiring these boutique brands or launching their own globally inspired product lines to remain relevant. From a regional perspective, the shift toward convenient, ready-to-use seasoning blends is accelerating in urbanized environments where time-constrained consumers still desire a high-quality, "restaurant-style" home dining experience. This trend is a primary catalyst for the growth of the liquid seasoning and paste segments, which offer intense flavor profiles with minimal preparation time.
- Largest Region: Asia-Pacific remains the dominant market shareholder due to its deep-rooted culinary heritage and massive domestic consumption in China and India.
- Fastest Growing Region: The LAMEA (Latin America, Middle East, and Africa) region is expected to exhibit the highest CAGR as urbanization and organized retail expansion introduce a wider variety of processed and packaged seasonings.
- Leading Segment by Type: The Spices and Herbs segment continues to hold the largest value share, driven by their foundational role in global cuisines and increasing demand in the food processing industry.
- Leading Segment by Application: The Meat and Poultry Products segment represents the highest utilization of seasonings, followed closely by the Bakery and Convenience Food sectors.
- Market Maturity: North America and Europe are considered mature markets, focusing on innovation in organic and low-sodium categories to sustain growth.
Key Takeaways Seasonings Market Size & Forecast
The forecast period for the seasonings market reflects a resilient growth trajectory despite global economic fluctuations. The steady increase in market valuation is fundamentally supported by the expansion of the global food processing industry and the rising popularity of ethnic cuisines in Western markets. Stakeholders are pivoting toward sustainable sourcing and ethical trade practices as consumers demand more information regarding the geographical origin of spices. The market size expansion is also intrinsically linked to the rising middle-class population in emerging economies, which is shifting from unbranded, loose spices to packaged, branded seasonings that offer better hygiene and standardized quality.
- Market Growth: A projected CAGR of 6.5% indicates a robust recovery and expansion phase, with the market value nearly doubling over the next decade.
- Dominant Countries: The United States, China, and India are the primary engines of value, while Brazil and Vietnam are emerging as critical supply-side hubs.
- Health Focus: Low-sodium and sugar-free seasoning blends are no longer niche products but are becoming standard requirements for mainstream retail shelves.
- Supply Chain Resilience: Companies are investing heavily in blockchain and AI-driven supply chain management to mitigate the risks of crop failure and price volatility in spice-producing regions.
- Distribution Channels: While supermarkets remain the primary volume drivers, the E-commerce segment is the fastest-growing channel for specialty and gourmet seasonings.
Seasonings Market Drivers Analysis
The primary driver of the seasonings market is the global "Home Chef" phenomenon, which gained significant momentum during the pandemic and has persisted as a permanent lifestyle shift. Consumers are increasingly experimenting with complex, authentic recipes that require specialized spice blends once reserved for professional kitchens. This behavior is supported by the rapid growth of the food service industry, where quick-service restaurants (QSRs) and casual dining establishments use proprietary seasonings to differentiate their menu offerings. Additionally, the increasing demand for convenience foods, which require high-intensity seasonings to maintain flavor profiles through processing and shelf-life, acts as a consistent growth catalyst.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Ethnic Cuisines | +1.8% | Global / North America & Europe | 2025 - 2034 |
| Demand for Clean-Label Ingredients | +1.5% | Europe / USA / Australia | 2025 - 2030 |
| Rise in Processed Food Consumption | +2.1% | Asia-Pacific / Latin America | 2025 - 2034 |
| Innovation in Low-Sodium Alternatives | +0.9% | Global / Developed Markets | 2026 - 2034 |
Seasonings Market Restraints Analysis
Market growth is significantly hampered by the inherent volatility in raw material prices. Spices like vanilla, black pepper, and cardamom are highly sensitive to climatic conditions, and a single bad harvest in a key producing region can lead to exponential price increases. Furthermore, the market faces stringent regulatory hurdles regarding food safety and pesticide residues. Adulteration remains a persistent challenge, particularly in fragmented markets where loose spices are common. These factors not only affect profit margins for manufacturers but also threaten consumer trust, necessitating expensive testing and certification processes that can deter smaller market entrants.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility | -1.2% | India / Vietnam / Madagascar | Short to Long Term |
| Strict Regulatory Compliance | -0.8% | European Union / USA (FDA) | Ongoing |
| Counterfeit and Adulterated Products | -0.5% | Developing Asia / Africa | Medium Term |
Seasonings Market Opportunities Analysis
The burgeoning plant-based meat and dairy alternative sector represents one of the most lucrative opportunities for seasoning manufacturers. Since plant-based proteins often lack the natural depth of flavor found in animal products, they require sophisticated, multilayered seasoning profiles to achieve consumer acceptance. Additionally, the development of "fortified seasonings" containing probiotics, vitamins, or minerals offers a new frontier for value-added products. The digitalization of the spice trade, where consumers can customize their own spice blends online, is another high-growth area that aligns with the trend of hyper-personalization in the food and beverage industry.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Plant-Based Sector Integration | +1.4% | Global / Developed Markets | 2026 - 2034 |
| Functional and Fortified Blends | +1.1% | North America / East Asia | 2027 - 2034 |
| E-commerce and Direct-to-Consumer | +1.3% | Global | 2025 - 2034 |
Seasonings Market Challenges Impact Analysis
Logistical complexities and the environmental impact of long-distance shipping remain significant challenges for the global seasonings trade. Most spices are grown in tropical regions but consumed globally, leading to a high carbon footprint and susceptibility to shipping disruptions. Moreover, the industry must navigate the "de-globalization" trend, where some regions are implementing protectionist trade policies or stricter import duties on agricultural products. Maintaining consistent flavor profiles across different batches while adhering to the diverse food safety standards of multiple countries adds another layer of operational complexity for multinational seasoning enterprises.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Climate Change Impact on Crops | -1.0% | Global / Tropical Regions | Long Term |
| Supply Chain Disruptions | -0.7% | Global / Logistics Hubs | Short Term |
| Sustainability Pressure | -0.4% | Global / Corporate CSR | Medium Term |
Seasonings Market - Updated Report Scope
The scope of this report encompasses a granular analysis of the global seasonings industry, covering raw spice commodities, blended herbs, salts, and liquid seasonings. It evaluates the impact of macroeconomic factors such as inflation and shifting trade agreements on the supply-demand equilibrium. The report provides a deep dive into consumer behavior patterns across diverse demographics, highlighting the transition from traditional to modern retail channels. By analyzing competitive benchmarking and market share concentration, this report serves as a strategic roadmap for investors, manufacturers, and retailers navigating the complexities of the 2025–2034 forecast period.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 24.50 Billion |
| Market Forecast in 2034 | USD 43.18 Billion |
| Growth Rate | 6.5% CAGR |
| Number of Pages | 248 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | McCormick & Company, Inc., The Kraft Heinz Company, Ajinomoto Co., Inc., Kerry Group plc, Nestlé S.A., Olam International, Associated British Foods plc, Everest Spices, Mahashian Di Hatti Private Limited (MDH), DS Group (Catch), Knorr (Unilever), Sensient Technologies Corporation, Givaudan, International Flavors & Fragrances Inc. (IFF), Fuchs North America, Inc., Badia Spices, Inc., Bart Ingredients, and Worlée Gruppe. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The seasonings market is segmented based on product type, physical form, application, and distribution network to provide a holistic view of the industry dynamics. The Spices and Herbs segment remains the foundational pillar of the market, but the Blends and Rubs category is experiencing faster growth due to the convenience they offer to home cooks and the industrial food sector. Within the form segment, Ground/Powder seasonings dominate volume due to their ease of storage and application, while Liquid seasonings are gaining traction in high-end culinary and industrial flavoring applications. Regional variations play a significant role in segment dominance; for instance, salt substitutes are seeing higher growth in aging populations within Europe and Japan compared to other regions.
- By Type:
- Herbs (Thyme, Basil, Oregano, Rosemary, others)
- Spices (Pepper, Chili, Ginger, Turmeric, Cumin, others)
- Salts and Salt Substitutes
- Specialized Blends and Dry Rubs
- By Form:
- Whole (Dried berries, seeds, and barks)
- Ground/Powder (The primary retail and industrial form)
- Liquid (Concentrates and infused oils)
- Paste (Ready-to-use culinary bases)
- By Application:
- Meat & Poultry Products (Largest industrial consumer)
- Snacks & Convenience Food (Fastest growing in urban regions)
- Bakery & Confectionery (Spices like cinnamon and nutmeg)
- Beverages (Spiced teas and functional drinks)
- By Distribution Channel:
- Offline (Supermarkets, Hypermarkets, Retail Stores)
- Online (DTC websites, Amazon, Specialized grocery apps)
- Industrial/B2B (Supplying to food manufacturers and QSR chains)
Regional Highlights
The regional distribution of the seasonings market is heavily influenced by local dietary habits and the presence of major food processing hubs. Asia-Pacific is not only the largest consumer but also the primary producer of many critical spices, giving it a strategic advantage in terms of pricing and availability. North America, led by the U.S., shows a high demand for innovative flavor profiles and ethnic blends, driven by a diverse multicultural population. In Europe, the market is characterized by a strong preference for organic and sustainably sourced products, with Germany and the UK being key growth drivers. Latin America and the Middle East are witnessing a transition from traditional spice markets to organized retail, which is boosting the sales of packaged and branded seasonings.
- Asia-Pacific: Dominates the market value with over 35% share; India and China are the key contributors.
- North America: Significant growth in the "Hot and Spicy" category and premium sea salts.
- Europe: Leading the world in clean-label and non-GMO seasoning standards.
- LAMEA: Highest growth potential due to expanding middle-class disposable income and urbanization in countries like Brazil, Saudi Arabia, and South Africa.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Seasonings Market.- McCormick & Company, Inc.
- The Kraft Heinz Company
- Ajinomoto Co., Inc.
- Kerry Group plc
- Nestlé S.A.
- Olam International
- Associated British Foods plc
- Everest Spices
- Mahashian Di Hatti Private Limited (MDH)
- DS Group (Catch)
- Unilever (Knorr)
- Sensient Technologies Corporation
- Givaudan
- International Flavors & Fragrances Inc. (IFF)
- Fuchs North America, Inc.
- Badia Spices, Inc.
- Bart Ingredients
- Worlée Gruppe
- Mizkan Holdings
- Takasago International Corporation
Frequently Asked Questions
What is the current and projected size of the global Seasonings Market?
The seasonings market is valued at approximately USD 24.50 Billion in 2025 and is projected to reach USD 43.18 Billion by 2034, growing at a steady CAGR of 6.5%.
Which region is expected to grow the fastest during the forecast period?
The LAMEA region (Latin America, Middle East, and Africa) is expected to be the fastest-growing region due to rapid urbanization and the expansion of the organized food retail sector.
What are the primary factors driving the growth of the seasonings industry?
Key drivers include the rising popularity of ethnic cuisines, the expansion of the processed and convenience food industry, and a significant shift toward home-based cooking and culinary experimentation.
How is the demand for clean-label products affecting the market?
Consumers are increasingly seeking seasonings free from MSG, artificial preservatives, and GMOs, forcing manufacturers to innovate with organic and natural spice profiles to maintain market share.
What role does the plant-based food trend play in the seasonings market?
The plant-based meat sector is a major opportunity, as these products require high-quality seasoning blends to mimic the flavor and texture of animal proteins, driving demand for specialized seasoning solutions.
Author
H
Hameer Thakur is a Manger Food and Beverages Research with over 8+ years of experience in the Food and Beverages Industry. He possesses extensive expertise in food and beverage market intelligence, consumer behavior analysis, demand forecasting, competitive benchmarking, product innovation assessment, pricing strategy, supply chain evaluation, regulatory compliance analysis, and market trend forecasting across packaged foods and beverage segments. His comprehensive research and data-driven insights enable organizations to make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, respond to evolving consumer preferences, and strengthen their competitive positioning in the global food and beverages market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
