Satellite Clinics Market
Satellite Clinics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711073 | Published On : October 03, 2026 |
Format : 


 | Author : Erika Grotto
Satellite Clinics Market Size
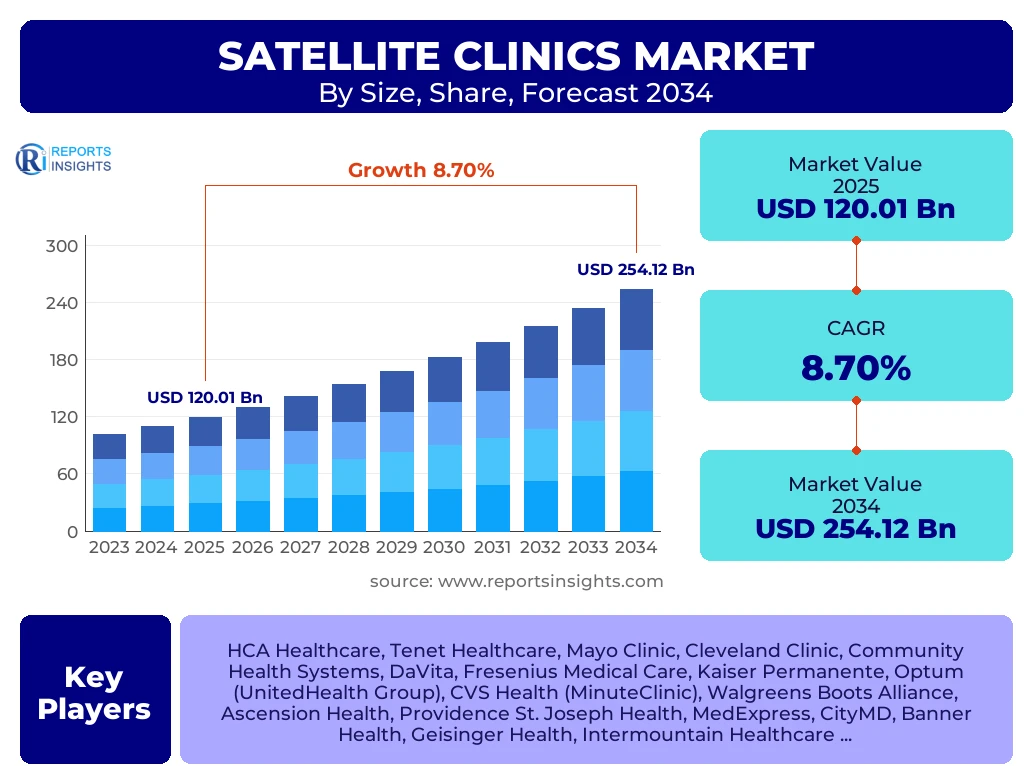
According to Reports Insights Consulting Pvt Ltd, The Satellite Clinics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.7% between 2026 and 2034. The market is estimated at USD 130.45 Billion in 2026 and is projected to reach USD 254.12 Billion by the end of the forecast period in 2034.
Key Satellite Clinics Market Trends & Insights
The global satellite clinics market is undergoing a significant transformation driven by the decentralization of healthcare services and the adoption of the hub-and-spoke delivery model. Large hospital systems are increasingly establishing satellite facilities in suburban and rural areas to improve patient accessibility and alleviate the burden on central tertiary care centers. Current trends indicate a heavy integration of digital health technologies, including advanced diagnostic imaging and real-time electronic health record (EHR) synchronization, which allow these off-site locations to provide a level of care once reserved for main campuses. Furthermore, the rise of specialized satellite centers focusing on oncology, orthopedics, and cardiovascular health reflects a shift toward localized, high-acuity outpatient services. Consumer preference for convenience and shorter wait times is fueling the expansion of these clinics into retail spaces and residential communities, effectively bringing expert medical consultation closer to the patient’s doorstep.
- North America currently stands as the largest region by market share, driven by a mature healthcare infrastructure and the aggressive expansion of major private healthcare networks.
- The Asia Pacific region is identified as the fastest-growing market, spurred by rapid urbanization, increasing healthcare expenditure in China and India, and government initiatives to improve rural healthcare access.
- Specialty-specific satellite clinics represent the largest segment in terms of revenue share, particularly those focusing on oncology and ambulatory surgery.
- The integration of telemedicine within satellite clinic frameworks is emerging as a critical trend, allowing local staff to consult with specialists at central hubs via high-definition video conferencing.
- Strategic partnerships between real estate developers and healthcare providers are facilitating the rapid rollout of clinics in high-traffic mixed-use developments.
Key Takeaways Satellite Clinics Market Size & Forecast
The satellite clinics market is poised for robust growth through 2034, supported by a fundamental shift in patient demographics and a global emphasis on value-based care. As healthcare providers seek to reduce operational overhead while maximizing patient volume, satellite clinics offer a scalable solution that balances cost-efficiency with high-quality clinical outcomes. The forecast period is expected to see a proliferation of physician-led satellite groups and hospital-owned networks that utilize data analytics to identify optimal geographic locations for new facility openings. Enhanced reimbursement policies for outpatient procedures in developed economies are also providing a financial tailwind for market expansion. Investors and stakeholders are increasingly focusing on the operational agility of these clinics, which can adapt more quickly to local community health needs than large-scale hospital infrastructures.
- The United States is the leading country in the satellite clinics market due to the high prevalence of chronic diseases and the consolidation of independent practices into larger clinical networks.
- The transition from inpatient to outpatient care is a primary catalyst, with satellite clinics capturing a significant portion of elective surgical procedures.
- Technological advancements in point-of-care testing (POCT) are enabling satellite clinics to provide immediate diagnostic results, enhancing patient satisfaction and clinical throughput.
- Sustainability and green building certifications are becoming important factors in the construction of new satellite facilities to meet corporate ESG goals.
- Workforce optimization through the use of nurse practitioners and physician assistants in satellite settings is helping to address the global shortage of specialized physicians.
Satellite Clinics Market Drivers Analysis
The expansion of the satellite clinics market is primarily driven by the increasing need for cost-effective healthcare delivery and the rising demand for localized patient care. Major healthcare systems are adopting a distributed model to reduce the strain on centralized hospital emergency departments and specialized units. Additionally, the aging global population requires more frequent monitoring and chronic disease management, which is more efficiently handled in a community-based satellite setting. Technological improvements in portable medical equipment and high-speed data connectivity have made it possible to replicate high-quality diagnostic and therapeutic services outside the traditional hospital environment, further incentivizing providers to expand their geographic footprint.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift Toward Outpatient and Ambulatory Care | +2.4% | Global (High in North America & Europe) | 2025 - 2034 |
| Increasing Prevalence of Chronic Diseases | +1.9% | Global | 2025 - 2034 |
| Advancements in Digital Health & Telemetry | +1.6% | Asia Pacific and North America | 2026 - 2032 |
| Government Initiatives for Rural Healthcare | +1.3% | India, Brazil, and Sub-Saharan Africa | 2025 - 2030 |
| Rising Demand for Personalized Medicine | +1.5% | Europe and North America | 2027 - 2034 |
Satellite Clinics Market Restraints Analysis
Despite the positive growth trajectory, the satellite clinics market faces several significant restraints, including high initial capital expenditure for specialized medical equipment and the complexities of regulatory compliance across different jurisdictions. Maintaining consistent quality of care and administrative oversight across a geographically dispersed network of clinics presents operational challenges. Furthermore, the shortage of qualified healthcare professionals, particularly specialized nurses and technicians, can limit the speed at which new satellite locations can be effectively commissioned and operated.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory and Licensing Requirements | -1.2% | European Union and North America | 2025 - 2034 |
| Shortage of Skilled Healthcare Personnel | -1.5% | Global | 2025 - 2034 |
| High Initial Setup and Infrastructure Costs | -1.0% | Developing Economies | 2025 - 2028 |
Satellite Clinics Market Opportunities Analysis
The emergence of AI-driven diagnostic tools and the integration of IoT-enabled medical devices present immense opportunities for the satellite clinics market to enhance diagnostic accuracy and operational efficiency. There is a growing opportunity for providers to specialize in niche markets, such as pediatric urgent care, geriatric wellness centers, and specialized rehabilitation clinics within the satellite model. Moreover, the expansion into emerging markets where traditional hospital infrastructure is lacking offers a first-mover advantage for large healthcare conglomerates looking to establish long-term brand presence and patient loyalty.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Underserved Rural Markets | +2.1% | Asia Pacific and Latin America | 2026 - 2034 |
| Integration of AI for Predictive Diagnostics | +1.8% | North America and Europe | 2027 - 2034 |
| Partnerships with Retail Chains for Co-location | +1.4% | United States and United Kingdom | 2025 - 2030 |
Satellite Clinics Market Challenges Impact Analysis
Key challenges in the satellite clinics market include ensuring data security and interoperability between satellite branches and the main medical hub. Data breaches and fragmented EHR systems can lead to clinical errors and loss of patient trust. Additionally, competition from established local independent practices and the rapid rise of purely virtual telehealth platforms challenge the traditional physical satellite clinic model. Navigating the varying reimbursement landscapes and ensuring financial viability in low-volume rural areas also remain persistent hurdles for market participants.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity and Patient Data Privacy | -0.8% | Global | 2025 - 2034 |
| Interoperability of Medical Records | -0.7% | Global | 2025 - 2034 |
| Competition from Virtual Telehealth Providers | -1.1% | Global (High in Urban Areas) | 2026 - 2034 |
Satellite Clinics Market - Updated Report Scope
This report provides a comprehensive analysis of the global satellite clinics market, covering historical data from 2020 to 2024 and providing detailed projections through 2034. The scope includes an in-depth evaluation of market drivers, restraints, opportunities, and challenges across various geographic regions and clinical specialties. It examines the strategic positioning of key players, technological advancements, and shifting patient preferences that are shaping the future of decentralized healthcare delivery.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 120.01 Billion |
| Market Forecast in 2034 | USD 254.12 Billion |
| Growth Rate | 8.7% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | HCA Healthcare, Tenet Healthcare, Mayo Clinic, Cleveland Clinic, Community Health Systems, DaVita, Fresenius Medical Care, Kaiser Permanente, Optum (UnitedHealth Group), CVS Health (MinuteClinic), Walgreens Boots Alliance, Ascension Health, Providence St. Joseph Health, MedExpress, CityMD, Banner Health, Geisinger Health, Intermountain Healthcare, Johns Hopkins Medicine, NYU Langone Health |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The satellite clinics market is segmented based on facility type, application, ownership, and geography to provide a detailed view of the competitive landscape. Hospital-affiliated clinics dominate the market as they leverage the brand equity and resource pool of established medical institutions. However, the retail clinic segment is witnessing the fastest growth due to strategic placements in pharmacies and shopping centers, catering to the demand for minor acute care and vaccinations. Specialty clinics, particularly those focusing on oncology and dialysis, represent high-value segments due to the recurring nature of treatments and the need for specialized equipment that can be efficiently housed in satellite locations.
- By Facility Type: Hospital-Affiliated Clinics, Private Clinics, Community Health Centers, Retail Clinics, Urgent Care Centers.
- By Application: Primary Care, Emergency/Urgent Care, Specialty Care (Oncology, Cardiology, Orthopedics, Pediatrics, Dermatology), Diagnostic Imaging and Lab Services.
- By Ownership: Public/Government-Owned, Private/Corporate-Led, Physician-Owned, Not-for-Profit Organizations.
- By End-User: Urban Populations, Rural and Underserved Communities, Occupational Health Services for Corporations.
- By Technology Integration: Standard Clinics, Smart Clinics (AI and IoT enabled), Telehealth-Integrated Centers.
Regional Highlights
- North America: The largest market share holder, characterized by advanced healthcare systems and a significant shift toward outpatient services. The United States leads this region due to the presence of major healthcare conglomerates like HCA Healthcare and Optum.
- Asia Pacific: The fastest-growing region, driven by massive investments in healthcare infrastructure in China, India, and Southeast Asia. The focus here is on improving accessibility in rural areas through mobile and modular satellite units.
- Europe: A mature market with a strong emphasis on public-private partnerships. Countries like the United Kingdom, Germany, and France are integrating satellite clinics into national health frameworks to reduce hospital wait times.
- Latin America: Growing steadily as private healthcare providers expand their footprints in major cities such as Sao Paulo and Mexico City to cater to the rising middle-class demand for high-quality medical services.
- Middle East and Africa: Increasing investment in medical tourism and the modernization of healthcare facilities in GCC countries are driving the adoption of specialized satellite clinics.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Satellite Clinics Market.- HCA Healthcare
- Tenet Healthcare Corporation
- Mayo Clinic
- Cleveland Clinic
- Community Health Systems, Inc.
- DaVita Inc.
- Fresenius Medical Care AG & Co. KGaA
- Kaiser Permanente
- Optum (UnitedHealth Group)
- CVS Health (MinuteClinic)
- Walgreens Boots Alliance
- Ascension Health
- Providence St. Joseph Health
- MedExpress
- CityMD
- Banner Health
- Geisinger Health
- Intermountain Healthcare
- Johns Hopkins Medicine
- NYU Langone Health
Frequently Asked Questions
What are the primary benefits of satellite clinics for patients?
Satellite clinics offer improved accessibility, reduced travel time, and shorter wait periods for patients. They provide high-quality care within the community, making it easier for patients to manage chronic conditions and receive routine screenings without visiting a major hospital campus.
How is technology impacting the satellite clinics market?
Technology is a major catalyst, with AI diagnostics, IoT-connected medical devices, and high-speed EHR systems enabling satellite clinics to provide specialized care. Telemedicine allows local clinicians to collaborate with remote specialists, effectively bridging the gap between local and tertiary care.
Which region is expected to see the fastest growth in the satellite clinics market?
The Asia Pacific region is expected to experience the highest CAGR due to rapid urbanization, increasing healthcare spending, and government initiatives aimed at expanding medical services to underserved rural populations in countries like China and India.
What is the difference between a retail clinic and an urgent care satellite clinic?
Retail clinics are typically located in pharmacies or supermarkets and focus on minor illnesses and preventative care like vaccines. Urgent care satellite clinics are equipped to handle more acute, non-life-threatening conditions that require immediate attention but do not necessitate an emergency room visit.
What are the main challenges in managing a network of satellite clinics?
Key challenges include maintaining clinical quality standards across different sites, ensuring cybersecurity for shared patient data, navigating diverse local regulations, and recruiting and retaining skilled healthcare staff in various geographic locations.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted