Robot Charging Station Market
Robot Charging Station Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711320 | Published On : October 26, 2026 |
Format : 


 | Author : Ashraf Shehata
Robot Charging Station Market Size
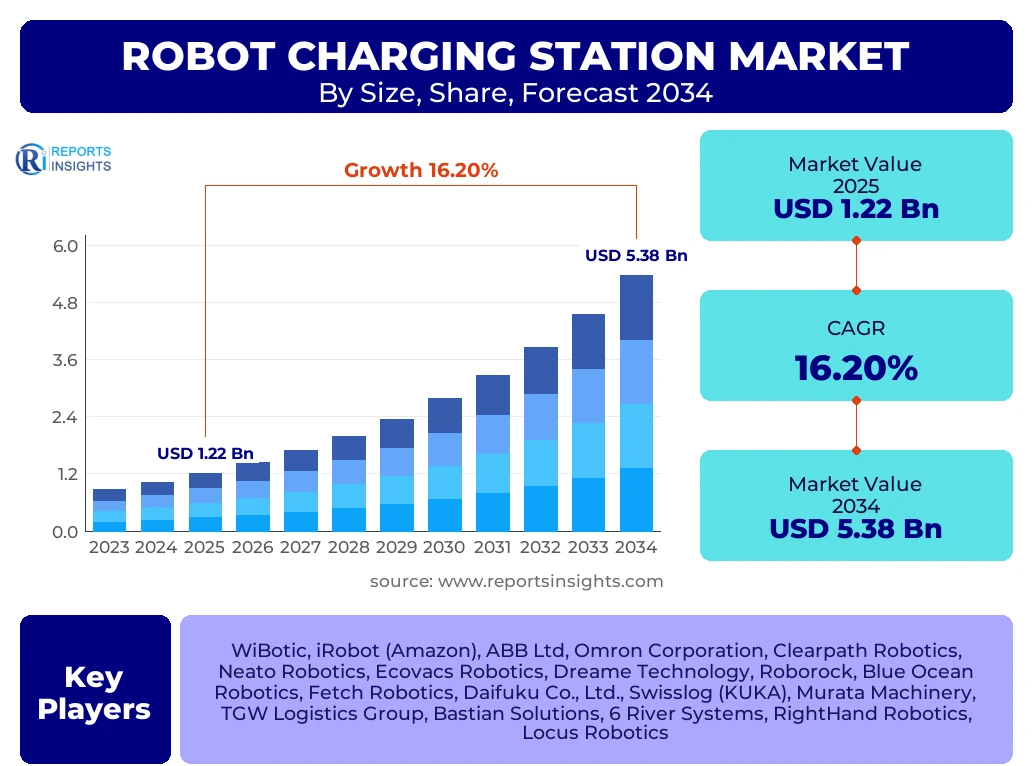
According to Reports Insights Consulting Pvt Ltd, The Robot Charging Station Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 16.2% between 2025 and 2034. The market is estimated at USD 1.42 Billion in 2026 and is projected to reach USD 5.38 Billion by the end of the forecast period in 2034.
Key Robot Charging Station Market Trends & Insights
The global Robot Charging Station market is currently experiencing a transformative phase characterized by the rapid adoption of autonomous mobile robots (AMRs) and automated guided vehicles (AGVs) across diverse industry verticals. Stakeholders are increasingly focusing on the integration of wireless power transfer (WPT) technologies to eliminate the physical wear and tear associated with traditional contact-based charging. Regional insights suggest that the Asia-Pacific region remains the dominant force due to its massive manufacturing base and the early adoption of service robots in hospitality and healthcare. Furthermore, the convergence of Internet of Things (IoT) and artificial intelligence (AI) is enabling smart charging infrastructure that can optimize power consumption and predict maintenance needs, thereby reducing total cost of ownership for robot fleet operators.
- Largest Region: Asia-Pacific, driven by extensive industrial automation in China, Japan, and South Korea.
- Fastest Growing Region: North America, attributed to the surging demand for delivery robots and advanced warehouse logistics.
- Largest Segment by Share: Industrial Robot Charging Stations, currently holding the majority share due to heavy-duty application requirements.
- Technological Shift: Significant migration from traditional plug-in docks to inductive and resonance-based wireless charging systems.
- Strategic Benchmarking: Key players are prioritizing modular charging solutions that can support multi-robot fleets with varying battery chemistries.
Key Takeaways Robot Charging Station Market Size & Forecast
The market trajectory for robot charging stations is inextricably linked to the broader robotics ecosystem, where the drive for 24/7 operational uptime is paramount. Analysis of user inquiries and market data indicates that modularity and scalability are the primary concerns for enterprise-level buyers. The forecast period highlights a shift toward decentralized energy management where charging stations serve as data nodes within a smart factory or smart home environment. The expansion of e-commerce logistics is identified as a critical catalyst, necessitating densified charging networks in micro-fulfillment centers. Government subsidies for automation and green energy initiatives are also expected to play a secondary but vital role in market acceleration across the European Union.
- Market Maturity: The market is transitioning from early-stage adoption to a growth phase, particularly in the logistics and domestic service sectors.
- Leading Country: China is the individual country leader, accounting for a substantial percentage of the global manufacturing robots and their charging infrastructure.
- Infrastructure Evolution: Increasing focus on universal charging standards to allow interoperability between different robot brands.
- Economic Impact: Automation of charging processes reduces labor costs and enhances robot utilization rates by up to 30 percent.
- Energy Efficiency: Development of fast-charging protocols that minimize downtime while maintaining battery health and longevity.
Robot Charging Station Market Drivers Analysis
The primary driver for the Robot Charging Station market is the escalating labor shortage in developed economies, which has forced a massive pivot toward automation. As industries integrate more robots, the need for autonomous energy replenishment becomes a non-negotiable requirement to maintain continuous workflows. Additionally, the proliferation of consumer robotics, such as vacuum cleaners and lawnmowers, has normalized the presence of docking stations in residential settings, creating a high-volume market segment.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Adoption of Autonomous Mobile Robots (AMRs) in Logistics | +4.8% | Global (High in North America & Europe) | 2025 - 2034 |
| Technological Advancements in Wireless Charging & Inductive Power | +3.5% | Japan, South Korea, Germany | 2026 - 2030 |
| Expansion of E-commerce and Automated Warehousing | +4.2% | China, USA, India | 2025 - 2034 |
| Growing Demand for Domestic Service Robots | +2.7% | Global (High in APAC) | 2025 - 2034 |
Robot Charging Station Market Restraints Analysis
Despite the optimistic growth outlook, the market faces significant restraints, primarily revolving around the high initial capital expenditure required for sophisticated charging infrastructure. Technical limitations such as energy loss during wireless transmission and the lack of standardized interfaces between disparate robot manufacturers also act as a bottleneck, complicating the deployment of cross-brand robot fleets in large-scale facilities.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Installation and Maintenance Costs for Advanced Stations | -2.1% | Developing Economies (MEA, Latin America) | 2025 - 2028 |
| Lack of Standardization in Charging Protocols and Connectors | -1.8% | European Union, North America | 2025 - 2030 |
| Power Grid Limitations in Industrial Zones | -1.2% | India, Southeast Asia | 2027 - 2034 |
Robot Charging Station Market Opportunities Analysis
Opportunities abound in the development of multi-modal charging hubs that can cater to both terrestrial robots and unmanned aerial vehicles (UAVs). The integration of renewable energy sources, such as solar-powered charging kiosks for outdoor security or agricultural robots, represents a significant greenfield opportunity. Furthermore, the Software-as-a-Service (SaaS) model for charging management is emerging as a lucrative secondary market for infrastructure providers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of AI for Predictive Energy Management | +3.2% | Global | 2026 - 2034 |
| Development of Universal Wireless Charging Mats | +2.9% | USA, Germany, Japan | 2027 - 2034 |
| Government Incentives for Green Automation Infrastructure | +1.5% | EU Countries | 2025 - 2030 |
Robot Charging Station Market Challenges Impact Analysis
The primary challenge remains the thermal management and efficiency loss in high-power rapid charging units, which can impact battery longevity. Ensuring cybersecurity in networked charging stations is another critical challenge, as these stations represent potential entry points for malicious actors into industrial control systems. Additionally, navigating the complex regulatory landscape regarding electrical safety for autonomous systems across different jurisdictions remains a hurdle for global expansion.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Thermal Dissipation in High-Speed Charging Systems | -1.4% | Global | Continuous |
| Cybersecurity Vulnerabilities in IoT-Enabled Stations | -1.1% | North America, Europe | 2025 - 2034 |
| Stringent Regulatory Compliance for Public-Space Robots | -0.9% | Japan, EU | 2025 - 2030 |
Robot Charging Station Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the global Robot Charging Station market, covering technological advancements, competitive landscapes, and regulatory frameworks. The scope extends from residential docking units for vacuum robots to heavy-duty industrial charging bays used in automotive manufacturing. It provides granular data on market sizing, volume consumption, and pricing trends across six major geographical regions, ensuring that stakeholders have the necessary intelligence to make informed strategic investments.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.22 Billion |
| Market Forecast in 2034 | USD 5.38 Billion |
| Growth Rate | 16.2% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | WiBotic, iRobot (Amazon), ABB Ltd, Omron Corporation, Clearpath Robotics, Neato Robotics, Ecovacs Robotics, Dreame Technology, Roborock, Blue Ocean Robotics, Fetch Robotics, Daifuku Co., Ltd., Swisslog (KUKA), Murata Machinery, TGW Logistics Group, Bastian Solutions, 6 River Systems, RightHand Robotics, Locus Robotics |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Robot Charging Station market reflects the diverse operational environments where robots are deployed. The industrial segment is characterized by high-power requirements and high durability, often utilizing automated contact charging or high-efficiency wireless pads. In contrast, the service robot segment, which includes robots in hotels and hospitals, prioritizes aesthetics and safety, often leaning toward discreet, low-profile docks. Residential segments are driven by consumer electronics trends, where compact size and low cost are the primary purchase drivers. Understanding these nuances is critical for manufacturers to tailor their product portfolios to specific market needs.
- By Type:
- Wired Charging: Traditional contact-based systems, highly efficient and cost-effective.
- Wireless Charging: Growing segment utilizing electromagnetic induction and resonance, offering high durability and autonomous alignment.
- By Robot Type:
- Service Robots: Includes domestic vacuum robots, lawnmowers, and professional medical or hospitality robots.
- Industrial Robots: Covers heavy-duty AGVs, AMRs used in manufacturing plants and distribution centers.
- By End-User:
- Logistics & Warehousing: The largest adopter of AMR charging solutions.
- Healthcare: Increasing use of disinfection and delivery robots in hospitals.
- Retail: Use of shelf-scanning and customer-service robots requiring frequent charging.
- Manufacturing: Deep integration with Smart Factory initiatives.
Regional Highlights
The regional distribution of the Robot Charging Station market is heavily influenced by the density of industrial activity and the maturity of the robotics ecosystem. Asia-Pacific is both the largest and one of the fastest-growing markets, fueled by China's aggressive "Robot + Action Plan" and Japan's long-standing leadership in robotics innovation. North America follows closely, with the United States seeing massive investment in automated fulfillment centers by major retail giants. Europe presents a steady growth profile, with Germany leading the way in Industry 4.0 applications. Meanwhile, emerging regions like the Middle East are beginning to invest in service robots for their smart city projects, such as NEOM, creating a new frontier for charging infrastructure providers.
- Asia-Pacific: Dominates with over 45% market share due to high concentration of electronics and automotive manufacturing.
- North America: Second largest market, characterized by rapid adoption of AMRs in third-party logistics (3PL) and delivery services.
- Europe: Focuses on high-quality engineering and safety standards, with a strong emphasis on professional service robots in healthcare.
- Middle East & Africa: Emerging market with high potential in the hospitality and infrastructure maintenance sectors.
- Latin America: Gradual growth driven by the modernization of agricultural and mining operations.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Robot Charging Station Market.- WiBotic
- iRobot (Amazon)
- ABB Ltd
- Omron Corporation
- Clearpath Robotics
- Neato Robotics
- Ecovacs Robotics
- Dreame Technology
- Roborock
- Blue Ocean Robotics
- Fetch Robotics
- Daifuku Co., Ltd.
- Swisslog (KUKA)
- Murata Machinery
- TGW Logistics Group
- Bastian Solutions
- 6 River Systems
- RightHand Robotics
- Locus Robotics
- Milvus Robotics
Frequently Asked Questions
What is the difference between wired and wireless robot charging stations?
Wired charging stations require a physical connection or contact between the robot and the station, offering high power transfer efficiency but being susceptible to mechanical wear. Wireless charging stations use electromagnetic induction or resonance to transfer energy through the air or a non-metallic surface, reducing maintenance and allowing for more flexible docking.
Which industry is the largest adopter of robot charging stations?
The logistics and warehousing industry is currently the largest adopter. This is due to the widespread deployment of large fleets of Autonomous Mobile Robots (AMRs) and Automated Guided Vehicles (AGVs) that require reliable, autonomous energy management systems to operate 24/7 in fulfillment centers.
How does the integration of AI benefit robot charging infrastructure?
AI enables predictive battery management, where the system can analyze the robot's usage patterns to determine the optimal time to charge. It also allows for fleet-wide energy balancing, ensuring that not all robots try to charge at the same time, which prevents power surges in industrial facilities.
Are there international standards for robot charging stations?
While industry-wide standardization is still evolving, several bodies like the IEC and ISO are developing protocols. Currently, many manufacturers use proprietary systems, but there is a significant push toward universal wireless charging standards to allow interoperability across different robot brands.
What is the projected market size by 2034?
The global Robot Charging Station market is projected to reach USD 5.38 Billion by 2034, growing at a CAGR of 16.2% from the base period. This growth is driven by the scaling of AMR fleets and the transition toward wireless power technologies.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
