Reverse Logistic Market
Reverse Logistic Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_703470 | Published On : September 15, 2026 |
Format : 


 | Author : Ashraf Shehata
Reverse Logistic Market Size
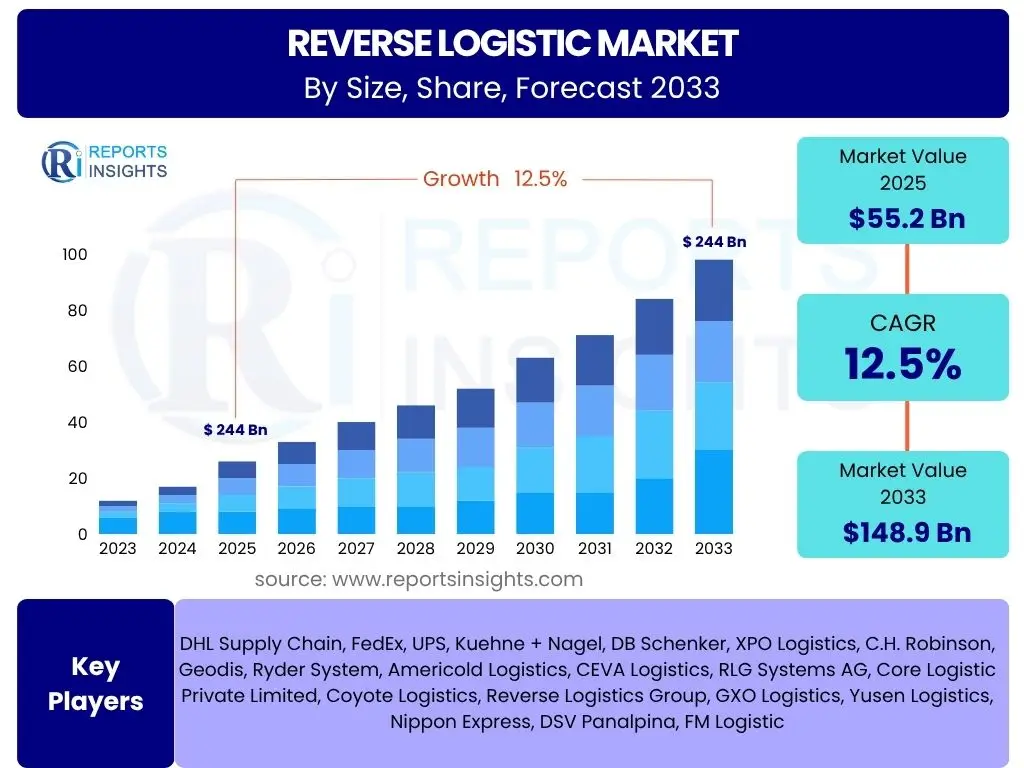
According to Reports Insights Consulting Pvt Ltd, The Reverse Logistic Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2026 and 2034. The market is estimated at USD 734.16 Billion in 2026 and is projected to reach USD 1,203.45 Billion by the end of the forecast period in 2034.
Key Reverse Logistic Market Trends & Insights
The global Reverse Logistic market is undergoing a fundamental transformation as industries shift from traditional linear supply chain models toward circular economy principles. Enterprise-level stakeholders are increasingly viewing return management not merely as a cost center but as a strategic lever for customer retention and sustainability compliance. The integration of advanced technologies such as Artificial Intelligence (AI) for predictive analytics, Internet of Things (IoT) for real-time asset tracking, and Blockchain for transparent documentation is revolutionizing how products are processed, refurbished, and resold. High return rates in the e-commerce sector, which often exceed thirty percent in categories such as apparel and electronics, have necessitated more robust, automated sorting and dispositioning systems. Regional shifts indicate that while North America remains a highly mature market, the Asia-Pacific region is experiencing the fastest growth due to the explosive expansion of digital retail platforms and evolving consumer protection laws regarding product returns.
- Asia-Pacific: Identified as the fastest-growing region due to rapid urbanization, increasing internet penetration, and the emergence of massive e-commerce domestic markets in China and India.
- North America: Currently the largest market by value, driven by sophisticated 3PL (Third-Party Logistics) infrastructure and high consumer expectations for seamless return policies.
- E-commerce Segment: Remains the largest and most influential end-user segment, dictating market standards for speed and efficiency in return processing.
- Circular Economy Integration: Companies are prioritizing remanufacturing and refurbishment over traditional landfill disposal to meet Environmental, Social, and Governance (ESG) targets.
Key Takeaways Reverse Logistic Market Size & Forecast
The market trajectory for Reverse Logistic is heavily influenced by the globalization of retail and the increasing complexity of international trade regulations. Forecasts indicate that as consumer awareness regarding sustainability grows, the demand for efficient repair and recycling services will outpace basic return handling. Enterprises that invest in end-to-end visibility software are expected to achieve significantly higher recovery values from returned assets compared to those using manual processes. The market is also seeing a consolidation trend, where major logistics providers are acquiring niche Reverse Logistic specialists to enhance their service portfolios in reverse trucking, warehousing, and technical testing. This strategic positioning allows providers to offer comprehensive solutions that address the entire lifecycle of a product, thereby reducing operational friction and lowering the total cost of ownership for manufacturers and retailers alike.
- CAGR Strength: A steady growth rate of 6.4% reflects the indispensable nature of Reverse Logistic in modern omnichannel retail environments.
- Asset Recovery: Maximizing the value of returned goods through refurbishment is becoming a primary revenue driver for electronics and automotive companies.
- Sustainability Mandates: Regulatory frameworks in Europe, such as the Right to Repair legislation, are forcing companies to establish more localized and efficient repair networks.
- Technological Adoption: Predictive analytics is being used to anticipate return volumes, allowing warehouses to optimize labor and space allocation dynamically.
Reverse Logistic Market Drivers Analysis
The primary drivers of the Reverse Logistic market are rooted in the surge of online shopping and the subsequent increase in return volumes, alongside a global push for sustainable industrial practices. As consumers demand more flexible return options, such as "Buy Online, Return In-Store" (BORIS), the logistical requirements become more complex, driving the need for sophisticated management systems. Furthermore, strict environmental regulations regarding the disposal of hazardous waste, particularly in the electronics and automotive sectors, compel companies to adopt formalized Reverse Logistic protocols to ensure compliance and avoid heavy penalties.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Exponential Growth of E-commerce | +2.1% | Global / Asia-Pacific | Short to Long Term |
| Stricter Environmental & Waste Regulations | +1.4% | European Union / North America | Medium Term |
| Adoption of Circular Economy Models | +1.2% | Global | Long Term |
| Focus on Customer Loyalty and Retention | +0.9% | Global / Developed Markets | Short Term |
Reverse Logistic Market Restraints Analysis
Despite the growth drivers, the Reverse Logistic market faces significant restraints, primarily the high operational costs associated with transporting and processing returned goods. Unlike forward logistics, which benefits from economies of scale and standardized packaging, Reverse Logistic is often fragmented, with products arriving in various states of condition and packaging. This variability complicates automated sorting and increases the labor intensity of the process. Additionally, the lack of standardized global protocols for cross-border returns creates logistical bottlenecks and increases the administrative burden on international retailers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Operational and Transportation Costs | -1.1% | Global | Persistent |
| Complexities in Cross-border Returns | -0.7% | Global / Cross-border E-commerce | Short to Medium Term |
| Product Value Depreciation over Time | -0.5% | Consumer Electronics | Short Term |
Reverse Logistic Market Opportunities Analysis
The evolving landscape presents significant opportunities, particularly in the integration of AI-driven sorting and blockchain-enabled tracking. These technologies can drastically reduce the time it takes to process a return and improve the transparency of the secondary market. Furthermore, the expansion of third-party logistics (3PL) providers into specialized Reverse Logistic services allows small and medium-sized enterprises (SMEs) to access advanced return management capabilities without the need for massive capital investment. The rise of the "re-commerce" market, where refurbished goods are sold at a discount, also provides a new revenue stream for retailers who can efficiently process and certify returned items.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Re-commerce and Refurbished Goods | +1.8% | Global / Emerging Markets | Medium to Long Term |
| AI and Robotics in Return Sorting | +1.3% | North America / Europe | Medium Term |
| Strategic 3PL Outsourcing for SMEs | +1.1% | Global | Short to Medium Term |
Reverse Logistic Market Challenges Impact Analysis
Significant challenges remain in the Reverse Logistic sector, notably the difficulty in maintaining a profitable return-to-resale cycle. The speed at which products, particularly electronics and fashion, lose their market value means that any delay in the reverse supply chain results in direct financial loss. Moreover, the lack of consumer education regarding proper return packaging and the inclusion of all necessary components often leads to damaged goods and incomplete returns, further complicating the refurbishment and restocking process.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Inconsistent Product Condition Grading | -0.8% | Global | Short to Medium Term |
| Data Security in Returned Electronics | -0.6% | Global / Corporate Sector | Medium Term |
| Labor Shortages in Warehouse Facilities | -0.4% | North America / Europe | Short Term |
Reverse Logistic Market - Updated Report Scope
This report provides a comprehensive examination of the Reverse Logistic landscape, covering the strategic movement of goods from the end-user back to the manufacturer or to a designated point for disposal, refurbishment, or resale. The scope encompasses various service types including transportation, warehousing, and value-added services such as technical testing and repair. It analyzes market dynamics across five major geographical regions and provides detailed segmentation by return type and end-user industry to offer a granular view of growth pockets and investment opportunities through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 690.00 Billion |
| Market Forecast in 2034 | USD 1,203.45 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | DHL Group, FedEx Corporation, United Parcel Service (UPS), GXO Logistics, DB Schenker, C.H. Robinson, KUEHNE + NAGEL, XPO Logistics, GENCO (FedEx Subsidiary), Optoro, ReverseLogix, CoreCentric Solutions, Yusen Logistics, CEVA Logistics, Bollore Logistics, Agility, Toll Group, Safeway Logistics, BlueYonder |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Reverse Logistic market is segmented to reflect the diverse operational requirements across different industries and product lifecycles. Service-based segmentation highlights the dominance of transportation and warehousing, while end-user segmentation reveals how specific industry needs, such as the stringent hygiene requirements in healthcare or the rapid turnover in electronics, dictate specialized logistical strategies. Understanding these segments allows stakeholders to target specific niches where efficiency gains and cost savings are most achievable.
- By Service:
- Transportation: Focusing on the physical movement and return trucking routes.
- Warehousing: Including sorting, staging, and storage of returned inventory.
- Refurbishment & Repair: Value-added services to restore products to resale condition.
- Management Software: Platforms for tracking and processing return authorizations.
- By Return Type:
- Commercial Returns: Customer returns due to dissatisfaction or errors.
- Product Recalls: High-priority logistics triggered by safety or quality issues.
- End-of-Life (EoL): Recovery of components and recycling for sustainable disposal.
- By End-User:
- E-commerce: The largest driver of volume and technological innovation.
- Consumer Electronics: High-value recovery focusing on refurbishment and parts harvesting.
- Automotive: Complex logistics for core exchanges and heavy parts management.
- Pharmaceutical/Healthcare: Specialized handling for temperature-sensitive or regulated waste.
Regional Highlights
- North America: Currently leads in terms of market valuation due to the early adoption of omnichannel retail and a well-established infrastructure of 3PL providers specializing in return management. The United States is the primary contributor, driven by high consumer return rates and advanced logistics technology.
- Asia-Pacific: Forecasted to be the fastest-growing region. Rapid digital transformation in China, India, and Southeast Asia has led to an explosion in e-commerce, requiring localized Reverse Logistic networks to handle massive return volumes during peak shopping seasons like Single’s Day and Diwali.
- Europe: Growth is significantly influenced by sustainability regulations. The European Green Deal and various waste electrical and electronic equipment (WEEE) directives are forcing manufacturers to take greater responsibility for the entire product lifecycle, boosting the refurbishment and recycling sectors.
- Middle East & Africa: Emerging as a key area for development as logistics hubs in Dubai and Riyadh expand their capabilities to support growing regional e-commerce and industrial trade.
- Latin America: Seeing steady growth driven by the expansion of multinational retailers into Brazil and Mexico, necessitating more structured Reverse Logistic to manage cross-border complexities.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Reverse Logistic Market.- DHL Group
- FedEx Corporation
- United Parcel Service (UPS)
- GXO Logistics
- DB Schenker
- C.H. Robinson
- KUEHNE + NAGEL
- XPO Logistics
- GENCO (A FedEx Company)
- Optoro
- ReverseLogix
- CoreCentric Solutions
- Yusen Logistics
- CEVA Logistics
- Bollore Logistics
- Agility
- Toll Group
- Safeway Logistics
- BlueYonder
- Liquidity Services
Frequently Asked Questions
What is the current size and projected growth of the Reverse Logistic Market?
The Reverse Logistic Market is estimated at USD 734.16 Billion in 2026 and is projected to reach USD 1,203.45 Billion by 2034, growing at a CAGR of 6.4% during the forecast period.
Which end-user industry dominates the Reverse Logistic space?
The E-commerce industry is the dominant end-user, accounting for the highest volume of returns and driving significant investments in automated sorting and return management software.
How is the circular economy impacting Reverse Logistic?
The circular economy is shifting the focus of Reverse Logistic from simple disposal to value recovery, encouraging practices like refurbishment, remanufacturing, and recycling to extend product lifecycles and reduce environmental impact.
What are the primary challenges in the Reverse Logistic market?
Key challenges include high operational and transportation costs, the rapid depreciation of returned goods (especially in electronics), and the lack of standardized global protocols for processing cross-border returns.
Which region is expected to show the fastest growth through 2034?
The Asia-Pacific region is expected to be the fastest-growing market due to the rapid expansion of e-commerce, increasing middle-class consumption, and evolving digital retail infrastructure in countries like China and India.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
