Reverse Factoring Market
Reverse Factoring Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711455 | Published On : November 02, 2026 |
Format : 


 | Author : Ram Krishnan
Reverse Factoring Market Size
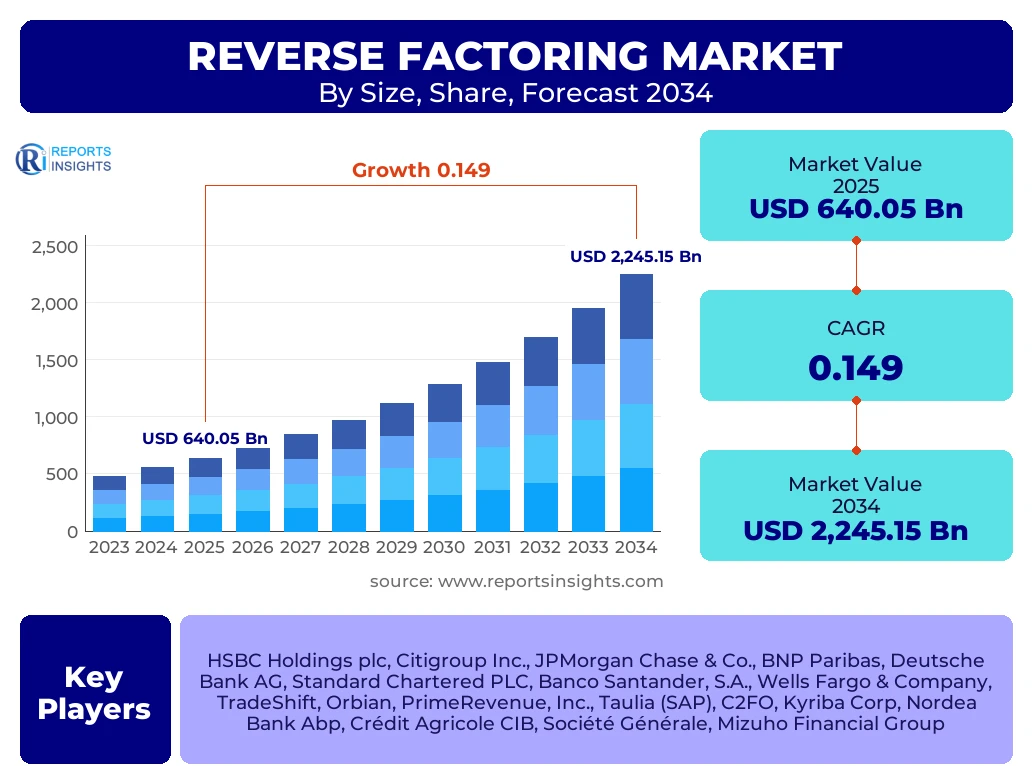
According to Reports Insights Consulting Pvt Ltd, The Reverse Factoring Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 14.9% between 2025 and 2034. The market is estimated at USD 735.40 Billion in 2026 and is projected to reach USD 2,245.15 Billion by the end of the forecast period in 2034.
Key Reverse Factoring Market Trends & Insights
The global landscape of supply chain finance is undergoing a significant transformation as corporate entities prioritize liquidity and operational resilience. Reverse factoring, often referred to as supply chain finance (SCF), has transitioned from a niche financial tool used by large multinationals to a mainstream working capital solution. The integration of Artificial Intelligence (AI) and Machine Learning (ML) is currently the most impactful trend, enabling real-time risk assessment and automated invoice processing. Furthermore, there is a visible shift toward Sustainability-Linked Reverse Factoring, where buyers provide preferential discount rates to suppliers that meet specific Environmental, Social, and Governance (ESG) criteria. This evolution is driven by the dual need for financial stability and corporate social responsibility across global value chains.
- Largest Region: Europe remains the dominant market, accounting for over 40% of the global share, driven by mature financial ecosystems and high adoption rates among French, Spanish, and German corporations.
- Fastest Growing Region: Asia-Pacific is expected to witness the highest CAGR during the forecast period, fueled by rapid industrialization in India, Vietnam, and Indonesia, alongside a digital push in China.
- Largest Segment by Category: Domestic reverse factoring continues to hold the largest market share due to simpler regulatory frameworks and lower cross-border complexities.
- Leading Service Provider Segment: Traditional Banks maintain the largest share, although Fintech platforms are capturing market territory through superior user interfaces and faster onboarding processes.
Key Takeaways Reverse Factoring Market Size & Forecast
The trajectory of the reverse factoring market reflects a broader corporate movement toward the optimization of Days Payable Outstanding (DPO) without compromising supplier relationships. Analysts observe that the market is moving away from purely transactional relationships toward strategic partnership models. The forecast period suggests that the convergence of blockchain technology and cloud-based SCF platforms will eliminate traditional bottlenecks, such as manual documentation and slow verification. As interest rates remain volatile globally, the credit arbitrage offered by reverse factoring—where suppliers leverage the buyer’s superior credit rating—becomes increasingly attractive for maintaining SME liquidity in emerging economies.
- The global market value is expected to triple by 2034, highlighting the essential nature of liquidity management in modern trade.
- France and Spain are identified as the leading European markets with established legal frameworks specifically supporting SCF initiatives.
- The Manufacturing sector represents the most significant end-user vertical, contributing nearly 30% of the total market volume.
- Small and Medium Enterprises (SMEs) are becoming the primary beneficiaries of reverse factoring programs as buyers seek to de-risk their upstream supply chains.
- Digital transformation is no longer optional; over 85% of new reverse factoring programs are expected to be hosted on cloud-native platforms by 2028.
Reverse Factoring Market Drivers Analysis
The expansion of the reverse factoring market is primarily catalyzed by the increasing complexity of global supply chains and the subsequent need for predictable cash flows. As enterprises strive to optimize their balance sheets, the ability to extend payment terms while ensuring suppliers receive early payment has become a competitive necessity. Additionally, the rapid digitization of financial services has lowered the entry barrier for smaller organizations, allowing for broader participation in SCF programs that were once reserved for the Fortune 500.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Accelerated Digitization of Trade Finance | +4.2% | Global (Strongest in APAC) | 2025 - 2030 |
| Focus on SME Liquidity and Financial Inclusion | +3.5% | India, Brazil, and Southeast Asia | 2026 - 2034 |
| Growth in Sustainable Supply Chain Finance (ESG) | +2.8% | European Union and North America | 2027 - 2034 |
| Corporate Drive for Working Capital Optimization | +4.4% | North America and Western Europe | 2025 - 2034 |
Reverse Factoring Market Restraints Analysis
Despite robust growth, the market faces significant headwinds from varying international regulatory standards and the risk of accounting reclassification. Regulators in certain jurisdictions are scrutinizing how reverse factoring is reported on balance sheets, with concerns that it may mask high levels of corporate debt. Furthermore, the high initial setup costs for bespoke platforms and the requirement for deep integration with existing ERP systems can deter smaller buyers from initiating these programs.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Regulatory Reporting Requirements (IFRS/GAAP) | -1.5% | United States and European Union | 2025 - 2028 |
| Complexity in Cross-Border Legal Frameworks | -1.2% | Middle East and Africa | 2025 - 2030 |
| Concerns Over Financial Transparency and Debt Masking | -0.8% | Global | Ongoing |
Reverse Factoring Market Opportunities Analysis
The emergence of blockchain and Distributed Ledger Technology (DLT) presents a transformative opportunity to enhance transparency and security in reverse factoring transactions. By creating immutable records of invoices and approvals, these technologies can significantly reduce fraud and errors. Moreover, the integration of deep-tier supply chain finance—where financing is extended beyond Tier 1 suppliers to Tier 2 and Tier 3—represents a massive untapped market segment that could redefine global trade resilience.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of Blockchain for Fraud Prevention | +3.1% | Japan, South Korea, and Singapore | 2027 - 2034 |
| Expansion into Deep-Tier Supplier Financing | +4.5% | Global (Manufacturing Hubs) | 2028 - 2034 |
| Rise of Non-Bank Financial Institutions (Fintechs) | +2.9% | Latin America and Africa | 2026 - 2034 |
Reverse Factoring Market Challenges Impact Analysis
The market must navigate challenges related to cybersecurity and the rising incidence of sophisticated financial fraud. As platforms become more interconnected, the risk of data breaches and systemic failures increases. Additionally, the volatility in global interest rates can impact the "spread" or profit margins for financial institutions, potentially making reverse factoring programs less attractive during periods of extreme economic instability or high default risks.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Increasing Cyber Threats to Financial Platforms | -0.9% | North America and Europe | 2025 - 2034 |
| Interest Rate Volatility Affecting Financing Costs | -1.4% | Global | 2025 - 2027 |
| Interoperability Between Diverse IT Platforms | -0.6% | Global | 2025 - 2030 |
Reverse Factoring Market - Updated Report Scope
This report provides a granular analysis of the global reverse factoring ecosystem, offering insights into market dynamics, competitive positioning, and technological advancements. The scope encompasses a detailed evaluation of various service types, provider categories, and diverse end-user industries across six major geographic regions. By examining the interplay between traditional banking and the rising fintech sector, the report equips stakeholders with the necessary data to navigate the evolving supply chain finance landscape through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 640.05 Billion |
| Market Forecast in 2034 | USD 2,245.15 Billion |
| Growth Rate | 14.9% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | HSBC Holdings plc, Citigroup Inc., JPMorgan Chase & Co., BNP Paribas, Deutsche Bank AG, Standard Chartered PLC, Banco Santander, S.A., Wells Fargo & Company, TradeShift, Orbian, PrimeRevenue, Inc., Taulia (SAP), C2FO, Kyriba Corp, Nordea Bank Abp, Crédit Agricole CIB, Société Générale, Mizuho Financial Group |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The reverse factoring market is segmented based on category, provider, organization size, and industry verticals to provide a comprehensive view of the liquidity landscape. Domestic reverse factoring currently dominates the market because it circumvents the complexities of multi-currency transactions and varying international trade laws. However, international reverse factoring is gaining traction as global trade corridors expand and companies seek to mitigate the risks associated with cross-border supplier networks. From a provider perspective, traditional banks leverage their massive balance sheets and long-standing corporate relationships, while fintech platforms are disrupting the market with agile, user-centric technology that simplifies the onboarding process for suppliers.
- By Category:
- Domestic Reverse Factoring
- International Reverse Factoring
- By Service Provider:
- Banks
- Non-banking Financial Institutions (NBFCs)
- Fintech/SCF Platforms
- By Organization Size:
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By End-user Vertical:
- Manufacturing
- Retail and Consumer Goods
- Healthcare and Pharmaceuticals
- Construction and Infrastructure
- IT and Telecommunications
- Food and Beverages
- Automotive
- Energy and Utilities
Regional Highlights
The regional distribution of the reverse factoring market reveals varying levels of maturity and adoption patterns. Europe stands as the cornerstone of this market, largely due to early adoption by large-scale retailers and automotive manufacturers who utilize reverse factoring to maintain supply chain integrity. Countries like France, Spain, and Italy have robust legal frameworks that favor the assignment of receivables, facilitating high market penetration. In North America, the market is characterized by technological innovation, with US-based fintech companies leading the shift toward cloud-based supply chain finance solutions.
Asia-Pacific is identified as the fastest-growing region, with a massive CAGR expected over the forecast period. The rapid growth in China and India is attributed to the digital transformation of banking and the urgent need to provide affordable credit to the vast SME sector that supports the region's manufacturing output. Latin America and the Middle East are also emerging as significant markets; in Latin America, Brazil and Mexico are witnessing increased interest as a means to stabilize local supply chains amidst economic volatility. Meanwhile, the Middle East is seeing growth driven by large-scale infrastructure projects where reverse factoring helps maintain the liquidity of sub-contractors.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Reverse Factoring Market.- HSBC Holdings plc
- Citigroup Inc.
- JPMorgan Chase & Co.
- BNP Paribas
- Deutsche Bank AG
- Standard Chartered PLC
- Banco Santander, S.A.
- Wells Fargo & Company
- TradeShift
- Orbian
- PrimeRevenue, Inc.
- Taulia (SAP)
- C2FO
- Kyriba Corp
- Nordea Bank Abp
- Crédit Agricole CIB
- Société Générale
- Mizuho Financial Group
- Basware Corporation
- Tungsten Network
Frequently Asked Questions
What is the current global market size of the reverse factoring industry?
The global reverse factoring market is estimated to be valued at USD 640.05 Billion in 2025 and is projected to experience significant growth, reaching over USD 2.2 Trillion by 2034.
How does reverse factoring differ from traditional factoring?
In traditional factoring, a supplier initiates the sale of its receivables to a factor. In reverse factoring, the buyer initiates the process, allowing their suppliers to access early payments based on the buyer's credit rating, often resulting in lower financing costs.
Which industry vertical is the largest adopter of reverse factoring?
The Manufacturing sector is currently the largest adopter of reverse factoring, as it involves complex, multi-tiered supply chains where liquidity management is critical for operational continuity.
What role does ESG play in the future of the reverse factoring market?
ESG is becoming a major differentiator; companies are increasingly implementing "Green Supply Chain Finance" programs that offer better discount rates to suppliers who meet specific environmental and social performance targets.
Which region offers the most growth potential for reverse factoring providers?
Asia-Pacific offers the highest growth potential due to its massive manufacturing base, increasing digital adoption, and the substantial credit gap faced by SMEs in the region.
Author
R
Ram Krishnan is a Manger Industry Services Research with 7+ years of experience in the Industry Services Industry. He specializes in industrial services market intelligence, service demand forecasting, competitive benchmarking, outsourcing and managed services analysis, operational performance assessment, market sizing, customer behavior analysis, pricing strategy evaluation, and industry trend forecasting across diverse service sectors. His analytical expertise transforms complex market data into actionable insights, enabling organizations to make strategic business decisions, identify growth opportunities, optimize operations, understand evolving market dynamics, and strengthen their competitive positioning in global industry services markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
