Retinal Detachment Diagnostic Market
Retinal Detachment Diagnostic Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711200 | Published On : October 16, 2026 |
Format : 


 | Author : Erika Grotto
Retinal Detachment Diagnostic Market Size
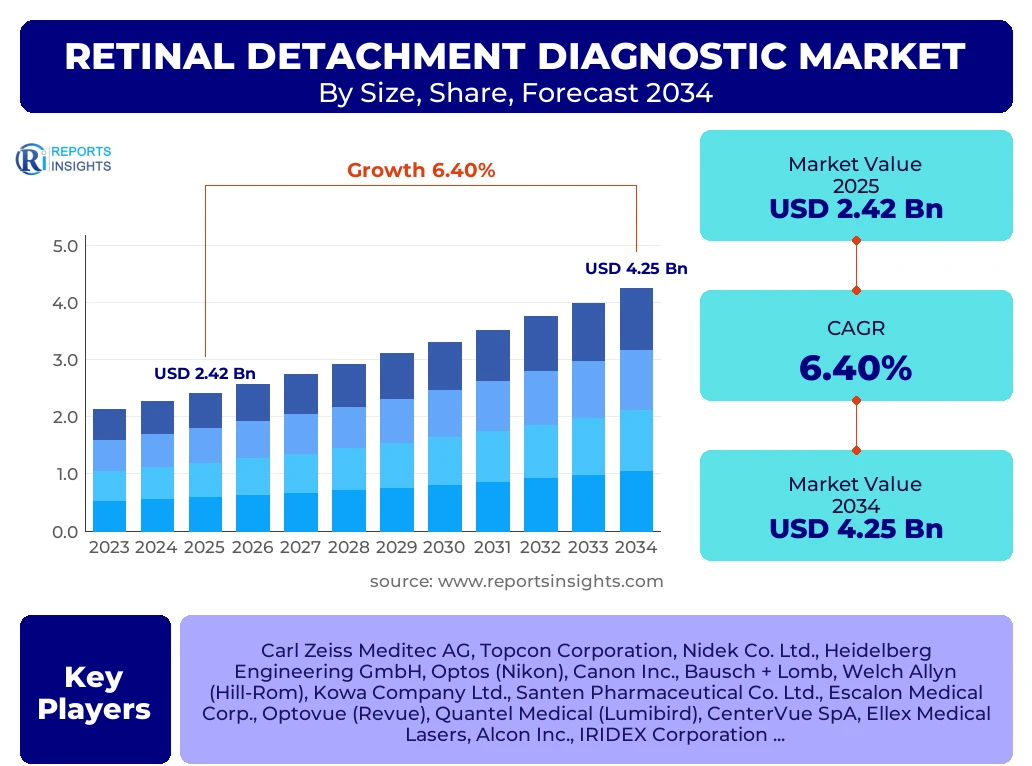
According to Reports Insights Consulting Pvt Ltd, The Retinal Detachment Diagnostic Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2025 and 2034. The market is estimated at USD 2.58 Billion in 2026 and is projected to reach USD 4.25 Billion by the end of the forecast period in 2034.
Key Retinal Detachment Diagnostic Market Trends & Insights
The global landscape for retinal detachment diagnostics is undergoing a significant transformation driven by the integration of artificial intelligence (AI) and machine learning algorithms into ocular imaging systems. Current market research indicates that the shift from traditional ophthalmoscopy to advanced high-resolution imaging such as ultra-widefield (UWF) fundus photography and swept-source optical coherence tomography (SS-OCT) is accelerating. Analysts observe a growing preference for non-invasive diagnostic tools that provide comprehensive peripheral retinal views, which is critical for early detection of rhegmatogenous tears. Furthermore, the rise of tele-ophthalmology is facilitating remote screening in underserved regions, creating new growth avenues for portable diagnostic devices. Competitive benchmarking reveals that leading players are focusing on miniaturization and cloud-based data management to streamline clinical workflows and improve patient outcomes in both acute and chronic settings.
- North America remains the largest regional market due to high healthcare expenditure and early adoption of advanced imaging technologies.
- The Asia Pacific region is identified as the fastest-growing market, fueled by a rising geriatric population and increasing prevalence of myopia.
- The Optical Coherence Tomography (OCT) segment holds the largest market share owing to its superior cross-sectional visualization capabilities.
- Integration of AI-driven diagnostic software is the most prominent trend for enhancing diagnostic accuracy and reducing clinician workload.
Key Takeaways Retinal Detachment Diagnostic Market Size & Forecast
The Retinal Detachment Diagnostic market is poised for robust expansion as healthcare systems prioritize early intervention to prevent permanent vision loss. Key takeaways suggest that the market is transitioning toward a multi-modal diagnostic approach where ultrasound and OCT are used in tandem to confirm complex cases of tractional or exudative detachment. The market forecast is heavily influenced by the rising global incidence of diabetes and high myopia, both of which are primary risk factors for retinal issues. Strategic collaborations between diagnostic hardware manufacturers and software developers are expected to redefine the competitive landscape, emphasizing the importance of digital health integration. Stakeholders are increasingly investing in research and development to create cost-effective diagnostic solutions for emerging economies, where the burden of preventable blindness is highest.
- The United States leads the global market in terms of value, supported by favorable reimbursement policies for ophthalmic procedures.
- A significant surge in the adoption of ultra-widefield imaging is expected to replace conventional fundus cameras in specialized eye clinics.
- Rhegmatogenous retinal detachment remains the leading application segment due to its high clinical prevalence.
- Hospitals and specialized eye clinics continue to be the primary end-users, accounting for over 65% of the total market revenue.
Retinal Detachment Diagnostic Market Drivers Analysis
The primary driver for the Retinal Detachment Diagnostic market is the alarming increase in the prevalence of high myopia and diabetic retinopathy globally. As the eyeball elongates in myopic patients, the retina thins and becomes more susceptible to tears and detachment, necessitating frequent and precise diagnostic screening. Additionally, the global aging population represents a permanent demographic shift that increases the pool of patients at risk for posterior vitreous detachment (PVD), a common precursor to retinal tears.
Technological advancements in imaging modalities, particularly the evolution from Time-Domain to Spectral-Domain and now Swept-Source OCT, have drastically improved the speed and resolution of retinal scans. These innovations allow for the detection of sub-clinical changes that were previously invisible, driving replacement sales in mature markets. Furthermore, increased government initiatives to curb visual impairment and the expansion of private healthcare infrastructure in developing nations are providing a steady impetus for market growth.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of High Myopia and Diabetes | +1.8% | Global (Strongest in China and India) | 2025-2034 |
| Technological Innovations in OCT and UWF Imaging | +1.5% | North America and Europe | 2025-2030 |
| Expanding Geriatric Population Base | +1.2% | Japan, Germany, and United States | 2025-2034 |
| Increasing Healthcare Infrastructure Investment | +0.9% | Southeast Asia and Latin America | 2026-2032 |
Retinal Detachment Diagnostic Market Restraints Analysis
Despite the positive growth trajectory, the market faces significant restraints, most notably the high acquisition and maintenance costs of advanced diagnostic equipment. A high-end Swept-Source OCT or an ultra-widefield fundus camera requires a substantial capital investment, which often limits their availability to large urban hospitals or premium private practices, leaving smaller clinics with outdated technology. This disparity in equipment access can hinder overall market penetration in price-sensitive regions.
Additionally, a shortage of trained ophthalmologists and technicians capable of interpreting complex retinal scans remains a critical bottleneck. In many developing countries, the patient-to-specialist ratio is extremely high, leading to delayed diagnoses and poor patient outcomes. Furthermore, stringent regulatory approval processes for new diagnostic devices and AI software can delay the time-to-market, acting as a temporary barrier for innovative startups and established players alike.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Capital Cost of Imaging Systems | -1.1% | Emerging Markets (Africa, parts of Asia) | 2025-2034 |
| Shortage of Skilled Ophthalmic Professionals | -0.8% | Global (Specifically Rural Areas) | 2025-2034 |
| Stringent Regulatory and Compliance Frameworks | -0.5% | European Union and United States | 2025-2028 |
Retinal Detachment Diagnostic Market Opportunities Analysis
The integration of Tele-ophthalmology and cloud-based diagnostic platforms presents a massive opportunity for market expansion. By enabling primary care providers or optometrists to capture high-quality retinal images and transmit them to specialists for remote review, the diagnostic gap in rural and underserved areas can be bridged. This decentralized model of care is expected to drive the demand for portable, handheld fundus cameras and simplified OCT systems that do not require extensive specialized training to operate.
Moreover, the application of Artificial Intelligence (AI) for automated screening of retinal detachment and associated pathologies offers a transformative opportunity. AI algorithms can analyze thousands of images in seconds, identifying red flags with high sensitivity and specificity. This not only improves diagnostic speed in emergency departments but also reduces the chances of human error. Markets in the Asia-Pacific region, particularly China and India, offer untapped potential due to their massive population bases and rapidly modernizing healthcare sectors.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Driven Automated Screening Solutions | +2.1% | Global (Advanced Economies First) | 2026-2034 |
| Expansion of Tele-ophthalmology Services | +1.4% | Rural USA, Canada, and Australia | 2025-2032 |
| Growth in Medical Tourism for Eye Care | +0.7% | Thailand, Turkey, and Mexico | 2027-2034 |
Retinal Detachment Diagnostic Market Challenges Impact Analysis
One of the foremost challenges is the variability in reimbursement landscape across different regions. In several countries, the lack of specific billing codes for advanced retinal imaging or AI-assisted diagnosis limits the adoption of these technologies. Providers are often hesitant to invest in new equipment if they cannot ensure a clear return on investment through patient billing. This creates a fragmented market where technological adoption is unevenly distributed based on local policy rather than clinical need.
Data privacy and security concerns also pose a significant challenge, especially with the rise of cloud-based imaging and AI. Ensuring that patient ocular data is protected against cyber threats while maintaining interoperability between different diagnostic platforms is a complex task. Furthermore, the physical limitations of current technology, such as the difficulty in imaging patients with dense cataracts or small pupils, continue to challenge the diagnostic accuracy in specific patient cohorts, necessitating further R&D in non-visible light imaging.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Inconsistent Reimbursement Policies | -0.9% | United Kingdom, Brazil, and India | 2025-2030 |
| Data Security and Interoperability Issues | -0.6% | European Union (GDPR) and USA | 2025-2034 |
| Clinical Limitations in Comorbid Patients | -0.4% | Global | 2025-2034 |
Retinal Detachment Diagnostic Market - Updated Report Scope
The scope of this report encompasses a thorough analysis of the global retinal detachment diagnostic ecosystem, covering hardware, software, and clinical service trends. It provides granular insights into various imaging modalities including OCT, Fundus Cameras, and Ophthalmic Ultrasound, while segmenting the market by application type and end-user environment. The report analyzes the impact of macroeconomic factors, such as inflation and healthcare policy changes, on the procurement of diagnostic equipment. Furthermore, it offers a detailed competitive landscape, profiling key innovators and established leaders who are shaping the future of vitreoretinal diagnostics through strategic mergers and technological breakthroughs.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.42 Billion |
| Market Forecast in 2034 | USD 4.25 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Carl Zeiss Meditec AG, Topcon Corporation, Nidek Co. Ltd., Heidelberg Engineering GmbH, Optos (Nikon), Canon Inc., Bausch + Lomb, Welch Allyn (Hill-Rom), Kowa Company Ltd., Santen Pharmaceutical Co. Ltd., Escalon Medical Corp., Optovue (Revue), Quantel Medical (Lumibird), CenterVue SpA, Ellex Medical Lasers, Alcon Inc., IRIDEX Corporation, Leica Microsystems, Volk Optical Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented by product type, application, and end-user, providing a comprehensive view of where value is being generated and where future growth is likely to occur. The Product Type segment is currently dominated by Optical Coherence Tomography (OCT) due to its essential role in identifying sub-retinal fluid and vitreoretinal interface disorders. However, the Ophthalmic Ultrasound segment is witnessing steady growth, particularly in emergency rooms where it is used to diagnose detachment in eyes with opaque media, such as vitreous hemorrhage. Application-wise, Rhegmatogenous detachment represents the majority of cases, while the Tractional detachment segment is growing rapidly due to the rising global diabetic population.
- By Product Type:
- Optical Coherence Tomography (OCT) - Including SD-OCT and SS-OCT
- Fundus Cameras - Including Mydriatic, Non-mydriatic, and Ultra-widefield
- Ophthalmic Ultrasound - A-scan and B-scan devices
- Ophthalmoscopes - Direct and Indirect variants
- Fluorescein Angiography Systems
- By Application:
- Rhegmatogenous Retinal Detachment - Primarily related to retinal tears and PVD
- Tractional Retinal Detachment - Common in advanced diabetic retinopathy
- Exudative (Serous) Retinal Detachment - Associated with inflammatory diseases and tumors
- By End-User:
- Hospitals - Large-scale facilities with comprehensive ophthalmic departments
- Specialized Eye Clinics - Private practices focusing exclusively on retinal health
- Ambulatory Surgical Centers (ASCs) - Increasing role in outpatient diagnostic procedures
- Academic and Research Institutes - Focus on clinical trials and technology development
Regional Highlights
- North America: The largest market globally, characterized by high adoption of Swept-Source OCT and ultra-widefield imaging. The presence of major industry players and a well-established reimbursement framework for retinal imaging drives the market.
- Europe: A mature market with strong growth in Germany, France, and the UK. Focus is shifting toward public-health screening programs for diabetic retinopathy, which includes retinal detachment checks.
- Asia Pacific: The fastest-growing region. China and India are the key contributors due to the sheer volume of patients with myopia and diabetes. Government investments in healthcare infrastructure are significantly boosting the sales of diagnostic equipment.
- Latin America: Growing at a moderate pace, led by Brazil and Mexico. Expansion is driven by the modernization of private healthcare facilities and an increase in ophthalmic awareness.
- Middle East and Africa: A developing market where growth is concentrated in the Gulf Cooperation Council (GCC) countries due to rising healthcare expenditure and a high prevalence of lifestyle-related eye conditions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Retinal Detachment Diagnostic Market.- Carl Zeiss Meditec AG
- Topcon Corporation
- Nidek Co. Ltd.
- Heidelberg Engineering GmbH
- Optos (Subsidiary of Nikon)
- Canon Inc.
- Bausch + Lomb
- Welch Allyn (Hill-Rom)
- Kowa Company Ltd.
- Santen Pharmaceutical Co. Ltd.
- Escalon Medical Corp.
- Optovue (Acquired by Revue)
- Quantel Medical (Lumibird Group)
- CenterVue SpA (Revue)
- Ellex Medical Lasers
- Alcon Inc.
- IRIDEX Corporation
- Leica Microsystems
- Volk Optical Inc.
- Ziemer Ophthalmic Systems AG
Frequently Asked Questions
What is the most accurate diagnostic tool for retinal detachment?
Currently, a combination of dilated fundus examination using indirect ophthalmoscopy and Optical Coherence Tomography (OCT) is considered the gold standard. B-scan ultrasound is also highly accurate, especially when the retina cannot be visualized due to cataracts or blood.
How is AI impacting the Retinal Detachment Diagnostic market?
AI is significantly improving diagnostic speed and accuracy by automatically detecting retinal breaks and fluid in imaging scans. This reduces the time to treatment, which is critical for saving vision in macula-on detachment cases.
Which region offers the most growth opportunities for diagnostic manufacturers?
The Asia Pacific region, particularly China and India, offers the highest growth potential due to increasing healthcare spending, a massive patient pool with high myopia, and the rapid expansion of specialized eye clinics.
What are the main risk factors driving the demand for these diagnostics?
The primary drivers include high myopia (nearsightedness), diabetic retinopathy, previous eye surgeries (like cataract surgery), eye trauma, and the natural aging process which leads to posterior vitreous detachment.
Are portable diagnostic devices becoming a standard in the market?
Yes, portable fundus cameras and handheld ophthalmoscopes are gaining popularity for use in emergency departments and primary care settings, facilitating early screening before the patient is referred to a vitreoretinal specialist.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
