Respiratory Filters Market
Respiratory Filters Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711468 | Published On : November 03, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Respiratory Filters Market Size
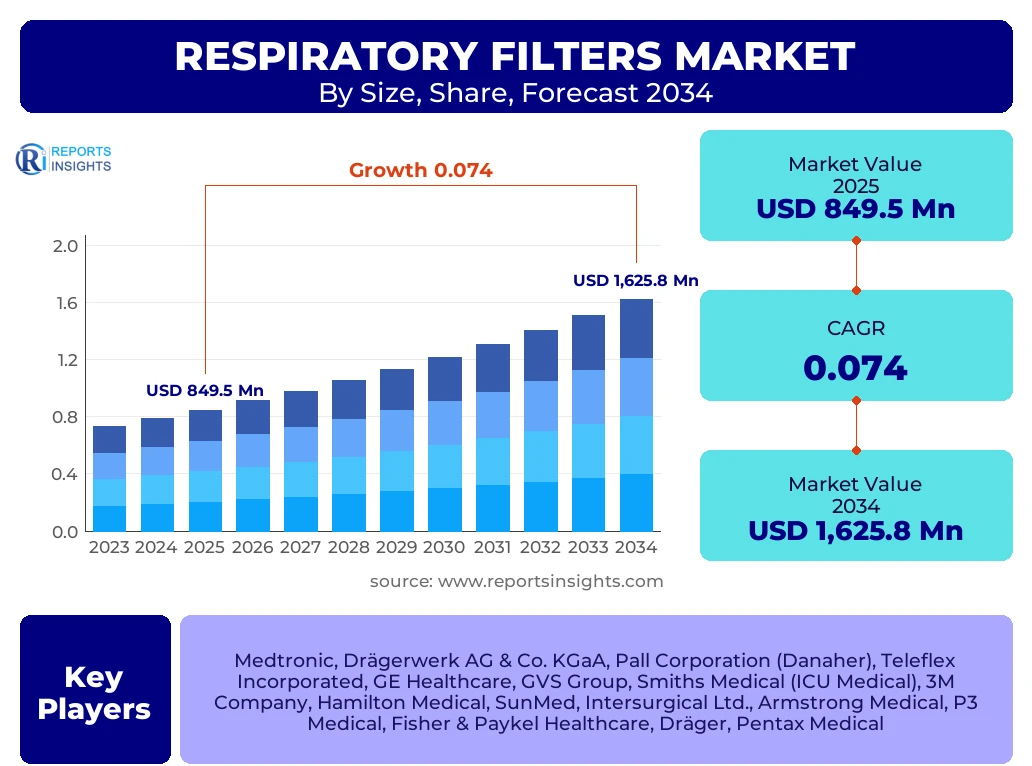
According to Reports Insights Consulting Pvt Ltd, The Respiratory Filters Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.4% between 2025 and 2034. The market is estimated at USD 912.4 Million in 2026 and is projected to reach USD 1,625.8 Million by the end of the forecast period in 2034.
The global trajectory of respiratory care is undergoing a fundamental shift, driven by a heightened focus on infection control and the rising prevalence of chronic obstructive pulmonary disease (COPD). Respiratory filters, which serve as a critical barrier against cross-contamination in mechanical ventilation and anesthesia circuits, are seeing increased integration across various clinical settings. The transition from general hospital care to specialized home-based respiratory therapy is expanding the addressable market for high-efficiency particulate air (HEPA) and heat and moisture exchange (HME) filters. Advanced filtration technologies are now prioritizing low resistance to flow and high filtration efficiency to ensure patient safety without compromising ventilator performance.
The valuation reflects a robust demand cycle sustained by aging populations in developed nations and infrastructure expansion in emerging economies. As healthcare systems globally emphasize the reduction of Ventilator-Associated Pneumonia (VAP) and other healthcare-acquired infections (HAIs), the procurement of premium-grade respiratory filters has become a standard protocol. Technological advancements, such as the development of electrostatic filters and the incorporation of antimicrobial coatings, are expected to provide additional value-added growth. Market stakeholders are increasingly focusing on the vertical integration of supply chains to mitigate risks associated with raw material price fluctuations, particularly for medical-grade polymers and specialized fiberglass media.
Key Respiratory Filters Market Trends & Insights
The contemporary market environment is characterized by a rapid move toward specialized filtration solutions that cater to specific patient demographics, including neonatal and pediatric care. One of the most significant trends is the adoption of heat and moisture exchange filters (HMEFs) which combine humidification with bacterial/viral filtration, effectively reducing the complexity of breathing circuits. Furthermore, the push for environmental sustainability in healthcare is prompting manufacturers to explore bio-based materials and recyclable components for single-use filters, addressing the rising concern over medical waste. Digital integration, though in its nascent stages, is beginning to influence the market through smart sensors that monitor filter saturation and resistance levels in real-time.
- Largest Region: North America remains the dominant revenue generator due to high healthcare expenditure and stringent clinical guidelines regarding infection control.
- Fastest Growing Region: Asia Pacific is projected to witness the highest CAGR, fueled by massive investments in hospital infrastructure in China, India, and Southeast Asia.
- Largest Product Segment: Heat and Moisture Exchange Filters (HMEFs) hold the largest market share as they provide dual functionality in critical care settings.
- Emerging Application: Home healthcare is the fastest-growing application segment as more patients utilize portable ventilators and oxygen concentrators.
- Material Innovation: Increasing shift from mechanical filters to electrostatic filters due to their lower breathing resistance and high efficiency.
Key Takeaways Respiratory Filters Market Size & Forecast
The convergence of demographic aging and the aftermath of global respiratory health crises has permanently elevated the baseline demand for high-quality filtration systems. Strategic focus is shifting toward the optimization of filter dead space and the minimization of moisture loss, which are critical parameters for long-term ventilated patients. The market is also seeing a consolidation phase where major medical device conglomerates are acquiring niche filter manufacturers to enhance their integrated respiratory care portfolios. Forecasts indicate that the adoption of high-efficiency filters will expand beyond traditional intensive care units (ICUs) into ambulatory surgical centers and emergency medical services.
- Critical Growth Driver: The global increase in chronic respiratory diseases like asthma and COPD serves as the primary long-term volume driver.
- Leading Segment: Viral and bacterial filters continue to lead in terms of unit volume due to their mandatory use in surgical anesthesia.
- Standardization: Implementation of ISO standards for respiratory tract tracheostomy and heat-and-moisture exchangers is harmonizing product quality globally.
- Cost-Efficiency: Manufacturers are focusing on reducing the cost per unit through automated high-volume production lines to penetrate price-sensitive markets.
- Pandemic Preparedness: Governments are now maintaining higher strategic stockpiles of respiratory consumables, including filters, ensuring a steady secondary demand.
Respiratory Filters Market Drivers Analysis
The expansion of the respiratory filters market is fundamentally anchored in the rising global burden of respiratory ailments and the clinical necessity of preventing cross-contamination in medical environments. As surgical volumes return to and exceed pre-pandemic levels, the use of anesthesia breathing circuits—each requiring multiple filtration points—is driving significant recurring revenue for manufacturers. Additionally, the move toward value-based care is incentivizing hospitals to invest in high-performance filters to reduce the incidence of costly hospital-acquired infections, which can lead to extended patient stays and increased morbidity.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Chronic Obstructive Pulmonary Disease (COPD) | +2.1% | Global (High in US, China, India) | 2025 - 2034 |
| Strict Protocols for Ventilator-Associated Pneumonia (VAP) Prevention | +1.8% | North America and Europe | 2025 - 2030 |
| Growth in Geriatric Population and Respiratory Comorbidities | +1.5% | Japan, Germany, Italy | 2026 - 2034 |
| Increasing Surgical Procedures Requiring General Anesthesia | +1.2% | Emerging Markets (Brazil, Mexico) | 2025 - 2034 |
Respiratory Filters Market Restraints Analysis
Despite the positive growth outlook, the market faces significant headwinds from the increasing pressure on healthcare budgets and the commoditization of basic filter types. Regulatory hurdles, particularly the stringent requirements for biocompatibility testing and clinical validation under the EU Medical Device Regulation (MDR), have increased the time-to-market and R&D costs for new entrants. Furthermore, the volatility in the prices of plastic resins and non-woven fabrics, which are essential raw materials, can squeeze profit margins for manufacturers who cannot easily pass these costs to hospital procurement groups.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rigid Regulatory Compliance and Certification Costs | -0.8% | European Union (MDR) | 2025 - 2028 |
| Environmental Concerns Regarding Single-Use Medical Plastics | -0.5% | Western Europe and Nordic Countries | 2027 - 2034 |
Respiratory Filters Market Opportunities Analysis
The evolution of personalized medicine and the shift toward home-based healthcare provide fertile ground for innovation in the respiratory filters sector. There is a significant opportunity in developing low-resistance filters optimized for portable oxygen concentrators and CPAP machines, where battery life and user comfort are paramount. Additionally, the integration of hydrophobic and hydrophilic properties into filter media can improve performance in high-humidity environments, opening doors for specialized use in neonatal intensive care units (NICU) where moisture management is critical for fragile patients.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Home Respiratory Care and CPAP Markets | +1.4% | Global (High in US) | 2026 - 2034 |
| Development of Sustainable and Biodegradable Filter Media | +0.9% | Europe and North America | 2028 - 2034 |
Respiratory Filters Market Challenges Impact Analysis
One of the primary challenges facing the industry is the high level of competition and the resulting price wars in the mid-to-low tier filter segments. Maintaining a balance between high filtration efficiency and low work-of-breathing remains a technical challenge, especially for pediatric applications. Moreover, the global supply chain for high-efficiency media is concentrated among a few key suppliers, making the market vulnerable to disruptions caused by geopolitical tensions or localized manufacturing shutdowns, as seen in recent years.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Concentration for Medical-Grade Fiberglass | -0.6% | Global | 2025 - 2030 |
| Pricing Pressures from Group Purchasing Organizations (GPOs) | -0.4% | United States | 2025 - 2034 |
Respiratory Filters Market - Updated Report Scope
This report provides a granular analysis of the global respiratory filters landscape, covering various filter types including HMEFs, HEPA, and electrostatic variants. The scope encompasses detailed financial modeling, competitive benchmarking, and regulatory analysis across major geographies. We explore the intersection of material science and clinical outcomes, providing stakeholders with actionable insights into product development and market entry strategies over the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 849.5 Million |
| Market Forecast in 2034 | USD 1,625.8 Million |
| Growth Rate | 7.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Medtronic, Drägerwerk AG & Co. KGaA, Pall Corporation (Danaher), Teleflex Incorporated, GE Healthcare, GVS Group, Smiths Medical (ICU Medical), 3M Company, Hamilton Medical, SunMed, Intersurgical Ltd., Armstrong Medical, P3 Medical, Fisher & Paykel Healthcare, Dräger, Pentax Medical |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on product functionality, clinical application, and end-user environment, reflecting the diverse requirements of the respiratory care continuum. Product-wise, the integration of viral filtration with humidification (HMEF) is the leading trend as it simplifies circuit setup and improves patient comfort during long-term mechanical ventilation. Application segments are increasingly focusing on specialized ICU protocols, while the end-user landscape is seeing a gradual shift toward decentralized care models.
- By Product Type:
- Heat and Moisture Exchange Filters (HMEFs) - Dominant due to dual-action capability.
- Bacterial and Viral Filters - High volume consumption in surgical units.
- HEPA Filters - Critical for high-risk infectious disease units and cleanroom-grade ventilation.
- Electrostatic Filters - Preferred for low resistance and high efficiency in portable devices.
- By Application:
- Anesthesia - Large usage during elective and emergency surgeries.
- Intensive Care - Driven by long-term ventilation requirements for critically ill patients.
- Home Care - Rapidly growing segment for sleep apnea and COPD management.
- By End-User:
- Hospitals - The primary procurement hub for high-performance filtration.
- Ambulatory Surgical Centers - Increasing share as more surgeries move to outpatient settings.
- Home Care Settings - Expanding due to the rise in portable medical equipment.
Regional Highlights
North America currently holds the lion's share of the global respiratory filters market, underpinned by a highly developed healthcare infrastructure and stringent adherence to infection prevention guidelines set by bodies like the CDC and OSHA. The United States market is particularly driven by a high volume of surgical procedures and a robust reimbursement framework for respiratory care consumables. In Europe, the market is characterized by strong regulatory oversight and a growing emphasis on sustainable medical devices, with Germany and the UK being key contributors to regional demand.
- North America: The largest market, characterized by early adoption of advanced HEPA and HME technologies and high per-patient spending.
- Asia Pacific: The fastest-growing region, with China and India investing heavily in upgrading their ICU capabilities and primary healthcare centers.
- Europe: A mature market focused on regulatory compliance (MDR) and the clinical efficiency of respiratory circuits in public healthcare systems.
- Latin America: Showing steady growth as healthcare access improves in Brazil and Mexico, focusing on affordable yet high-quality viral filters.
- Middle East & Africa: Emerging demand driven by the expansion of medical tourism and large-scale hospital construction projects in the GCC countries.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Respiratory Filters Market. These organizations are focusing on R&D to reduce the carbon footprint of their products while maintaining 99.99% filtration efficiency. Mergers and acquisitions are frequent as companies look to provide a "one-stop-shop" solution for breathing circuits.
- Medtronic
- Drägerwerk AG & Co. KGaA
- Pall Corporation (Danaher)
- Teleflex Incorporated
- GE Healthcare
- GVS Group
- Smiths Medical (ICU Medical)
- 3M Company
- Hamilton Medical
- Intersurgical Ltd.
- SunMed
- Fisher & Paykel Healthcare
- Armstrong Medical
- P3 Medical
- A-M Systems
- Vyaire Medical
- Flexicare Medical Limited
- Sartorius AG
Frequently Asked Questions
Analysis of common user questions regarding the Respiratory Filters market reveals concerns about filtration efficiency standards, the difference between mechanical and electrostatic filters, and the impact of environmental regulations on single-use components.
What is the main difference between an HME and an HMEF?
An HME (Heat and Moisture Exchanger) primarily focuses on retaining the patient's exhaled heat and moisture to humidify the inhaled air. An HMEF (Heat and Moisture Exchange Filter) adds a bacterial/viral filtration layer to the humidification property, providing dual protection for both the patient and the ventilator equipment.
Why is HEPA filtration critical in respiratory care?
HEPA (High-Efficiency Particulate Air) filters are designed to capture 99.97% of particles as small as 0.3 microns. In respiratory care, they are essential for preventing the spread of highly infectious airborne pathogens, such as tuberculosis or viral contaminants, within hospital environments and ventilation systems.
How is the move toward home healthcare affecting filter demand?
As more patients are treated for chronic conditions like COPD at home, there is an increased demand for smaller, more efficient filters compatible with portable oxygen concentrators and home ventilators. These filters must balance high efficiency with low resistance to preserve the battery life of portable devices.
What are the primary materials used in respiratory filter housings?
Most housings are made from medical-grade polymers like polypropylene or clear styrene-acrylonitrile (SAN). These materials are chosen for their biocompatibility, durability, and transparency, which allows clinicians to inspect the filter for moisture buildup or blockages.
Which region offers the most growth potential for manufacturers?
The Asia Pacific region offers the highest growth potential due to rapid healthcare modernization, increasing life expectancy, and the expansion of the middle class in countries like India and China, which leads to higher demand for specialized respiratory treatments.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
