Residential Real Estate Market
Residential Real Estate Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711606 | Published On : November 08, 2026 |
Format : 


 | Author : Ridam Bhatt
Residential Real Estate Market Size
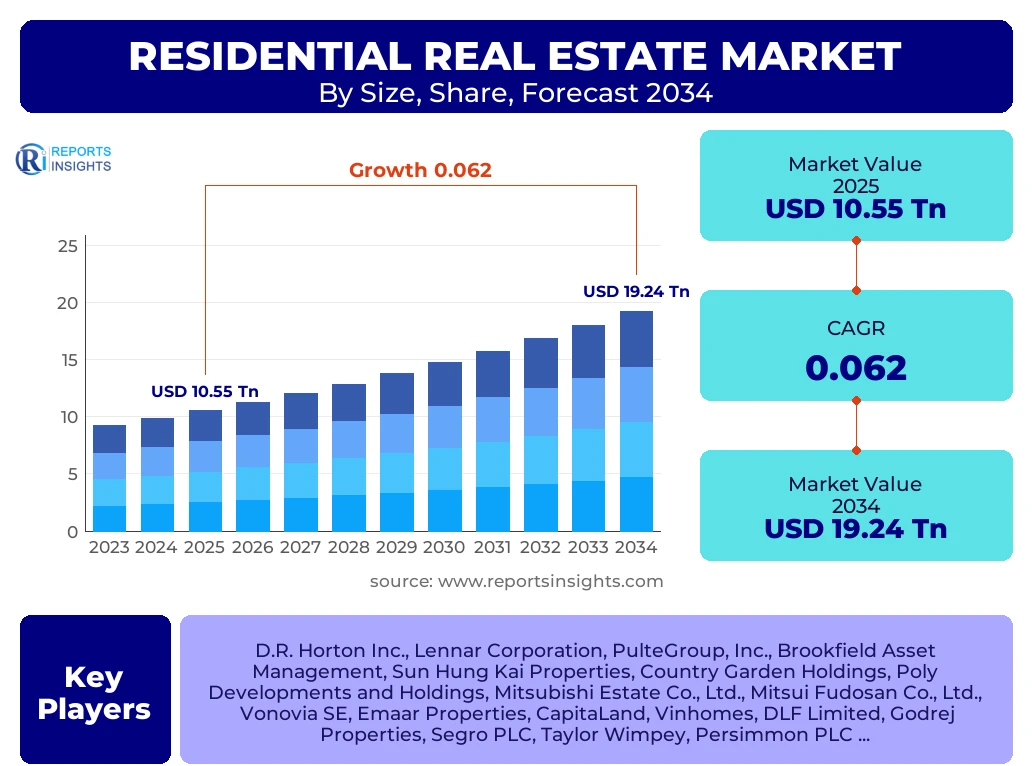
According to Reports Insights Consulting Pvt Ltd, The Residential Real Estate Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 11.20 Trillion in 2026 and is projected to reach USD 19.24 Trillion by the end of the forecast period in 2034.
Key Residential Real Estate Market Trends & Insights
The global residential real estate landscape is undergoing a profound structural transformation, driven by the convergence of demographic shifts, technological integration, and evolving consumer preferences for sustainable living. Market participants are increasingly focusing on PropTech solutions to streamline property management and enhance the buyer journey through virtual reality tours and blockchain-based transactions. Regional insights indicate a bifurcation between mature markets in North America and Europe, which are focusing on decarbonization and retrofitting, and emerging economies in Asia-Pacific and the Middle East, where rapid urbanization and government-backed affordable housing schemes are the primary growth catalysts. Competitive benchmarking reveals that leading developers are pivoting toward mixed-use developments that integrate residential spaces with commercial and recreational amenities to cater to the work-from-home culture.
- Asia-Pacific is the largest regional market, commanded by high-volume demand in China and India.
- The Middle East is the fastest-growing region, fueled by massive infrastructure projects and economic diversification strategies like Saudi Arabia Vision 2030.
- The Apartments and Condominiums segment holds the largest market share due to increasing density in urban centers.
- Integration of AI-driven smart home technologies is becoming a standard feature in high-end and mid-range residential segments.
Key Takeaways Residential Real Estate Market Size & Forecast
Analysis of market trajectories suggests that the residential sector remains a resilient asset class despite fluctuations in global interest rates. Stakeholders are prioritizing liquidity and asset diversification, with a notable surge in the Build-to-Rent (BTR) model across Western economies. The forecast period anticipates a significant influx of institutional capital into residential portfolios, traditionally dominated by private individual owners. This institutionalization of the market is expected to stabilize price volatility and improve the quality of property management services globally.
- China remains the leading country in terms of absolute market value, supported by large-scale urban redevelopment initiatives.
- India is identified as a critical growth engine, with its residential sector buoyed by a rising middle class and favorable regulatory reforms like RERA.
- The United States continues to lead in the luxury residential segment, driven by high net-worth individual investments and a persistent housing supply shortage.
- Sustainability certifications such as LEED and BREEAM are no longer optional but are essential value drivers in the European residential market.
Residential Real Estate Market Drivers Analysis
The primary catalyst for the residential real estate market is the relentless pace of urbanization across the developing world. As populations migrate to metropolitan hubs in search of economic opportunity, the demand for housing infrastructure scales exponentially. This is further supported by government-led initiatives aimed at closing the housing gap through subsidies and low-interest loan programs for first-time buyers. Additionally, the rise of the digital economy has enabled a new class of investors to enter the market through fractional ownership and REITs, significantly increasing market liquidity.
Furthermore, the evolution of lifestyle requirements in a post-pandemic world has redefined the definition of a residential asset. There is a heightened demand for larger living spaces that accommodate home offices, wellness areas, and outdoor access. This shift has revitalized suburban markets and driven a new wave of construction focused on health-centric architecture. Technological advancements in construction, such as 3D printing and modular housing, are also beginning to lower the barriers to entry by reducing time-to-market and labor costs, thus serving as a secondary growth driver for the broader industry.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Urbanization and Population Growth | +2.1% | Asia-Pacific, Africa | 2025-2034 |
| Government Affordable Housing Incentives | +1.5% | India, Brazil, GCC Countries | 2025-2030 |
| Rise of PropTech and Digital Transactions | +1.2% | Global | 2026-2034 |
| Institutional Investment in Build-to-Rent | +1.4% | North America, Europe | 2025-2034 |
Residential Real Estate Market Restraints Analysis
The most significant restraint currently facing the market is the volatility of global interest rates and the subsequent rise in mortgage costs. Central bank policies aimed at curbing inflation have made borrowing more expensive, thereby cooling demand in several key Western markets. This fiscal tightening often results in a mismatch between buyer affordability and seller expectations, leading to prolonged transaction cycles and reduced market turnover. High interest rates also increase the cost of capital for developers, potentially stalling large-scale residential projects that rely heavily on debt financing.
Moreover, the escalating costs of raw materials and skilled labor continue to pressure the profit margins of real estate developers. Supply chain disruptions, although stabilizing, have left a lasting impact on the price of steel, cement, and lumber. Environmental regulations, while beneficial for long-term sustainability, impose immediate compliance costs that can make new developments financially unviable in certain jurisdictions. These factors combined create a challenging environment for maintaining the pace of new housing supply, particularly in the affordable segment where margins are already thin.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Mortgage Rates and Fiscal Tightening | -1.8% | United States, United Kingdom, EU | 2025-2027 |
| Escalating Construction Material Costs | -1.3% | Global | 2025-2030 |
| Stringent Environmental & Zoning Regulations | -0.9% | Western Europe, California (USA) | 2025-2034 |
Residential Real Estate Market Opportunities Analysis
The transition toward green and sustainable housing presents a massive opportunity for value creation in the residential sector. Investors and homeowners are increasingly willing to pay a premium for properties that feature energy-efficient HVAC systems, solar integration, and high-performance insulation. This trend is supported by green financing options where banks offer lower interest rates for properties with high energy ratings. Developers who pioneer net-zero residential communities are likely to capture a significant share of the environmentally conscious millennial and Gen Z buyer segments.
Another emerging opportunity lies in the adaptive reuse of commercial assets into residential spaces. With the surplus of office and retail space in certain urban centers, converting these structures into modern apartments or co-living spaces addresses both the housing shortage and urban decay. Furthermore, the integration of the Silver Economy—housing specifically designed for the aging population—is a high-growth niche. Senior living facilities that offer a blend of independence and healthcare services are in high demand across Japan, Europe, and North America, offering stable, long-term yields for institutional investors.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Green Building and Energy Efficient Retrofitting | +2.5% | Europe, North America | 2026-2034 |
| Senior Living and Healthcare-Integrated Housing | +1.8% | Japan, Germany, USA | 2025-2034 |
| Commercial-to-Residential Conversions | +1.2% | Major Global Financial Hubs | 2025-2030 |
Residential Real Estate Market Challenges Impact Analysis
One of the most persistent challenges in the residential real estate market is the growing disparity between property valuations and average household incomes. This affordability crisis is particularly acute in global gateway cities, where speculative investment has driven prices to levels that exclude the local workforce. If left unaddressed, this can lead to social instability and political pressure for rent controls or vacancy taxes, which in turn can discourage further investment and development. Balancing profit motives with the social necessity of affordable housing remains a critical tightrope for the industry.
Geopolitical instability and changing migration patterns also pose significant risks to market stability. Conflicts or economic sanctions can lead to capital flight or sudden shifts in buyer demographics, impacting luxury markets that rely on foreign investment. Additionally, the industry faces a digital security challenge; as real estate becomes more tech-dependent, the risk of cyberattacks on smart home systems and digital transaction platforms increases. Ensuring data privacy and the security of the Internet of Things (IoT) ecosystem within residential buildings is a growing operational hurdle for developers and property managers alike.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Housing Affordability Crisis | -1.5% | Canada, Australia, Hong Kong | 2025-2034 |
| Geopolitical Tensions and Capital Flow Restrictions | -1.1% | Middle East, Eastern Europe, China | 2025-2028 |
| Cybersecurity Risks in Smart Home Infrastructure | -0.5% | Global (Technologically Advanced Markets) | 2027-2034 |
Residential Real Estate Market - Updated Report Scope
This comprehensive market analysis covers the global residential real estate sector across various dimensions, including property types, price points, and ownership models. The scope includes an in-depth evaluation of the macroeconomic factors influencing housing demand, the regulatory environment across six major regions, and the competitive strategies of the world top 20 real estate developers. The report provides a granular forecast from 2026 to 2034, utilizing a combination of historical data, econometric modeling, and expert interviews to ensure high accuracy and strategic relevance for investors and developers.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 10.55 Trillion |
| Market Forecast in 2034 | USD 19.24 Trillion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | D.R. Horton Inc., Lennar Corporation, PulteGroup, Inc., Brookfield Asset Management, Sun Hung Kai Properties, Country Garden Holdings, Poly Developments and Holdings, Mitsubishi Estate Co., Ltd., Mitsui Fudosan Co., Ltd., Vonovia SE, Emaar Properties, CapitaLand, Vinhomes, DLF Limited, Godrej Properties, Segro PLC, Taylor Wimpey, Persimmon PLC, Berkeley Group Holdings, China Vanke |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The residential real estate market is segmented into several critical categories that allow for a nuanced understanding of growth dynamics. The most dominant segment remains Apartments and Condominiums, particularly in high-density urban areas where land availability is restricted. However, the Villas and Independent Houses segment has seen a resurgence in popularity as remote work becomes more prevalent, allowing buyers to seek larger living spaces further from city cores. The market is also bifurcated by pricing, with the mid-range segment accounting for the highest volume of transactions globally, while the luxury segment drives significant value in global tier-1 cities.
- By Property Type: Analysis of Apartments, Condominiums, Semi-detached Houses, Detached Houses, and Luxury Villas.
- By Business Model: Direct Sales to homeowners versus the Institutional Rental (Build-to-Rent) model.
- By Budget: Comprehensive breakdown into Affordable (subsidized/low-cost), Mid-tier, and High-end/Luxury segments.
- By New Construction vs. Resale: Comparative growth of the primary sales market versus the secondary resale market.
Regional Highlights
The regional distribution of the residential real estate market reflects diverse economic stages and demographic trends. The Asia-Pacific region is the clear leader in terms of market volume, driven by China large-scale urban development and India housing-for-all initiatives. In North America, the market is characterized by a persistent supply-demand imbalance, leading to steady price appreciation and a robust rental market. Europe is at the forefront of the green transition, with strict regulations driving investment in sustainable new builds and the renovation of aging housing stock. The Middle East is emerging as a major hub for luxury residential developments, particularly in the UAE and Saudi Arabia, as part of broader efforts to attract international talent and investment.
- Asia-Pacific: Largest market share; China and India are the primary drivers of residential volume.
- Middle East: Fastest-growing region; Saudi Arabia is experiencing a residential boom due to Vision 2030.
- North America: High value market; driven by institutional players and high household net worth in the USA.
- Europe: Leading in sustainable residential practices; Germany and the UK are the most significant markets for Build-to-Rent models.
- Latin America: Emerging potential in Brazil and Mexico, supported by a young demographic and expanding middle class.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Residential Real Estate Market.- D.R. Horton Inc.
- Lennar Corporation
- PulteGroup, Inc.
- Brookfield Asset Management
- Sun Hung Kai Properties
- Country Garden Holdings
- Poly Developments and Holdings
- Mitsubishi Estate Co., Ltd.
- Mitsui Fudosan Co., Ltd.
- Vonovia SE
- Emaar Properties
- CapitaLand
- Vinhomes
- DLF Limited
- Godrej Properties
- Segro PLC
- Taylor Wimpey
- Persimmon PLC
- Berkeley Group Holdings
- China Vanke
Frequently Asked Questions
What is the projected size of the global Residential Real Estate Market by 2034?
The global residential real estate market is estimated to reach approximately USD 19.24 Trillion by 2034, growing at a steady CAGR of 6.2% from 2025 onwards.
Which region is currently leading the growth in residential real estate?
The Asia-Pacific region holds the largest market share due to rapid urbanization in China and India, while the Middle East is identified as the fastest-growing region through 2034.
How are interest rates impacting the residential market forecast?
High interest rates in North America and Europe are acting as a temporary restraint by increasing mortgage costs, but the long-term forecast remains positive due to persistent housing shortages and institutional investment.
What role does PropTech play in modern residential real estate?
PropTech is a significant growth driver, enhancing the market through digital transaction platforms, AI-driven property management, and virtual reality tools that facilitate international and remote buying.
Why is the Build-to-Rent (BTR) model gaining popularity?
The Build-to-Rent model is expanding because it offers institutional investors stable, long-term yields and addresses the growing demand for flexible, high-quality rental housing among younger demographics who face high barriers to homeownership.
Author
R
Ridam Bhatt is a Manger Consumer Goods Research with over 6+ years of experience in the Consumer Goods Industry. He specializes in consumer market intelligence, demand forecasting, category performance analysis, competitive benchmarking, pricing strategy, retail and distribution assessment, consumer purchasing behavior, product portfolio evaluation, and market trend analysis across fast-moving and durable consumer goods segments. His research delivers actionable, data-driven insights that help organizations make strategic business decisions, identify growth opportunities, optimize operational performance, understand evolving consumer trends, and strengthen their competitive positioning in global consumer goods markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
