Residential Light Frame Shear Wall Market
Residential Light Frame Shear Wall Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711623 | Published On : November 08, 2026 |
Format : 


 | Author : Jonathan Sikka
Residential Light Frame Shear Wall Market Size
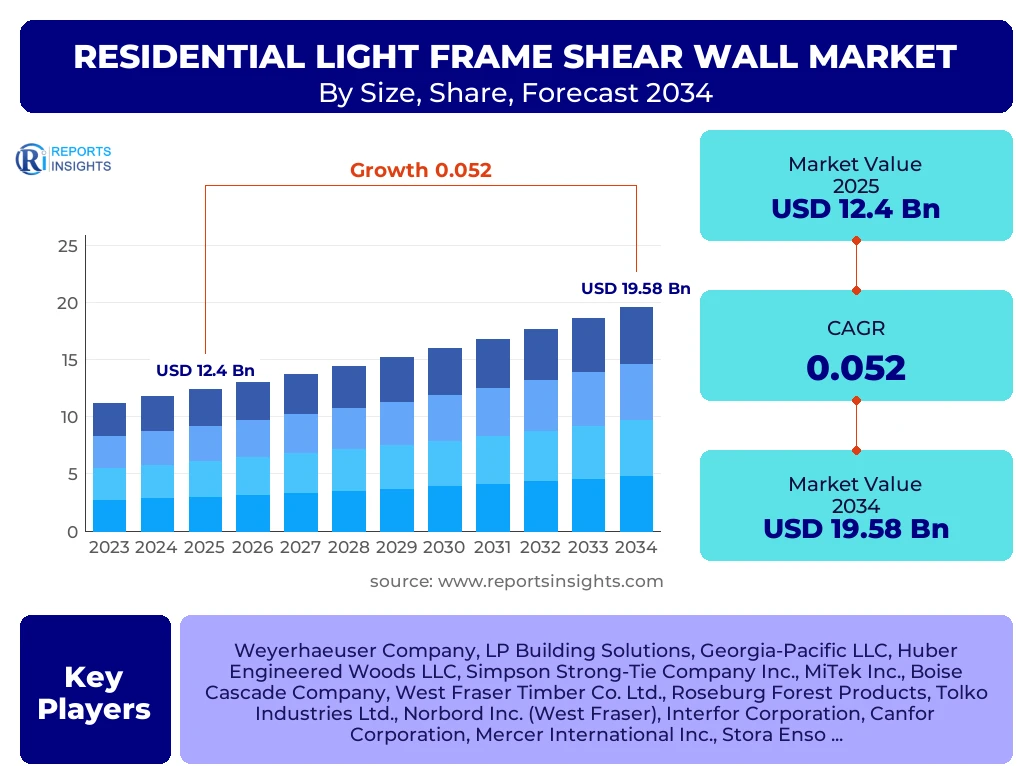
According to Reports Insights Consulting Pvt Ltd, The Residential Light Frame Shear Wall Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2025 and 2034. The market is estimated at USD 13.04 Billion in 2026 and is projected to reach USD 19.58 Billion by the end of the forecast period in 2034.
Key Residential Light Frame Shear Wall Market Trends & Insights
The global residential light frame shear wall market is undergoing a significant transformation driven by the escalating demand for resilient housing and the integration of advanced engineering materials. Contemporary market analysis reveals a paradigm shift toward prefabricated and modular construction techniques, which utilize factory-built shear wall panels to minimize on-site labor and ensure precision in structural integrity. In regions prone to seismic activity and high-wind events, there is a marked trend toward high-performance lateral force-resisting systems that exceed minimum building code requirements. Furthermore, the adoption of sustainable building materials, such as low-carbon Oriented Strand Board (OSB) and engineered wood products, is becoming a standard practice as developers seek to meet green building certifications. Digitalization in structural design, utilizing Building Information Modeling (BIM), allows for the optimization of nailing patterns and hold-down placements, significantly reducing material waste while enhancing the load-bearing capacity of residential structures.
- North America remains the largest region due to the deep-rooted prevalence of wood-frame construction in the United States and Canada.
- Asia-Pacific is the fastest-growing region, fueled by rapid urbanization and the adoption of modern light-frame timber technologies in Japan, Australia, and emerging urban centers in China.
- The Oriented Strand Board (OSB) segment holds the largest market share by material, valued for its cost-effectiveness and high shear strength-to-weight ratio.
- The New Residential Construction segment dominates the market, driven by the global housing deficit and the push for suburban expansion.
Key Takeaways Residential Light Frame Shear Wall Market Size & Forecast
The market trajectory for residential light frame shear walls is intrinsically linked to the global shift toward sustainable and disaster-resilient infrastructure. Stakeholders are increasingly prioritizing systems that offer both vertical load support and robust resistance to lateral forces. As regulatory bodies implement more stringent energy efficiency and safety standards, the market is seeing a surge in integrated wall systems that combine structural shear capacity with thermal insulation. The forecast period is expected to witness substantial investments in R&D for hybrid shear wall systems that incorporate light-gauge steel or composite materials to enhance durability in diverse climatic conditions. Global supply chain stabilization and the recovery of the lumber market are also anticipated to provide a favorable environment for consistent market expansion through 2034.
- The United States is the leading country in market value, supported by strict adherence to the International Residential Code (IRC).
- Automation in the production of prefabricated shear wall panels is expected to reduce overall project timelines by approximately 15-20%.
- Seismic-resistant shear wall designs are witnessing a 6% higher adoption rate in the Pacific Rim and Mediterranean regions.
- The renovation and retrofit segment is emerging as a high-growth area as older residential structures are upgraded to meet modern safety codes.
Residential Light Frame Shear Wall Market Drivers Analysis
The primary catalysts for the residential light frame shear wall market include the intensifying global focus on disaster-resilient housing and the structural requirements mandated by evolving building codes. Increased urbanization in developing economies and the persistent demand for single-family homes in developed nations provide a steady volume of projects requiring advanced lateral bracing systems. Additionally, the move toward sustainable wood-based construction as a carbon-sequestering alternative to concrete and steel is a critical driver for market growth.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Enforcement of Seismic and Wind Building Codes | +1.5% | Global (High impact in US, Japan, New Zealand) | 2025 - 2034 |
| Rise in Prefabricated and Modular Housing Trends | +1.2% | North America, Europe | 2026 - 2032 |
| Expansion of Sustainable and Carbon-Neutral Construction | +0.9% | European Union, Canada | 2025 - 2034 |
| Technological Advancements in Engineered Wood Products | +0.7% | Global | 2027 - 2034 |
Residential Light Frame Shear Wall Market Restraints Analysis
Despite strong growth drivers, the market faces headwinds from the volatility of raw material prices, particularly timber and OSB. Supply chain disruptions can lead to significant cost fluctuations that impact project budgets. Furthermore, a shortage of skilled structural engineers and specialized labor capable of correctly installing complex shear wall systems in emerging markets poses a challenge to widespread adoption. Competition from alternative building systems, such as Light Gauge Steel (LGS) and Insulated Concrete Forms (ICF), also limits the total addressable market in certain high-density residential sectors.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Costs of Wood-Based Raw Materials | -0.8% | North America, Europe | 2025 - 2029 |
| Shortage of Skilled Labor for Precision Installation | -0.5% | United States, UK, Australia | 2025 - 2034 |
| Competition from Steel-Frame and Concrete Alternatives | -0.4% | Middle East, parts of Asia | 2026 - 2034 |
Residential Light Frame Shear Wall Market Opportunities Analysis
The market is ripe with opportunities in the development of hybrid shear wall systems that integrate advanced materials like Carbon Fiber Reinforced Polymers (CFRP) to increase strength without adding significant weight. There is also a burgeoning opportunity in the "Green Retrofitting" sector, where existing residential buildings are reinforced with modern shear wall technology to enhance their resilience against climate-change-induced extreme weather. Digital twin technology and AI-driven structural analysis represent a frontier for manufacturers to offer high-value consultancy and design-build services alongside their physical products.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of High-Performance Hybrid Shear Systems | +1.1% | Japan, United States, Europe | 2028 - 2034 |
| Growth in Multi-Family Light-Frame Residential Projects | +0.8% | Urban centers globally | 2025 - 2034 |
| Integration of Smart Sensors for Structural Health Monitoring | +0.4% | North America, Germany | 2030 - 2034 |
Residential Light Frame Shear Wall Market Challenges Impact Analysis
One of the most pressing challenges is the lack of standardized global building codes for light-frame timber in certain high-growth developing regions, which slows down the entry of international players. Environmental concerns regarding deforestation and the long-term sustainability of old-growth timber sources also present a challenge to the industry's public image. Additionally, the need for rigorous testing and certification of new shear wall components to meet fire safety standards in multi-story residential buildings adds time and cost to the product development cycle.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Fire Safety Regulations in Multi-Story Timber | -0.6% | Europe, North America | 2025 - 2030 |
| Environmental Regulations and Timber Sourcing Compliance | -0.3% | Brazil, Southeast Asia, Russia | 2025 - 2034 |
Residential Light Frame Shear Wall Market - Updated Report Scope
This report provides a comprehensive examination of the residential light frame shear wall market, covering structural components, material science, and regional regulatory impacts. It analyzes the entire value chain from raw material processing to final on-site assembly, highlighting the competitive landscape and technological innovations shaping the industry. The scope encompasses various residential formats including single-family detached homes, townhouses, and multi-family low-to-mid-rise residential buildings.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 12.4 Billion |
| Market Forecast in 2034 | USD 19.58 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Weyerhaeuser Company, LP Building Solutions, Georgia-Pacific LLC, Huber Engineered Woods LLC, Simpson Strong-Tie Company Inc., MiTek Inc., Boise Cascade Company, West Fraser Timber Co. Ltd., Roseburg Forest Products, Tolko Industries Ltd., Norbord Inc. (West Fraser), Interfor Corporation, Canfor Corporation, Mercer International Inc., Stora Enso, Metsä Group, binderholz GmbH. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on material, application, and structural configuration to provide a granular understanding of growth pockets. The material segment is currently dominated by OSB due to its uniform properties and cost-efficiency compared to traditional plywood. However, plywood remains the preferred choice in high-moisture environments or where extreme durability is required. Application-wise, new construction accounts for the bulk of the market, though the renovation segment is growing rapidly as homeowners seek to increase the structural resilience of older properties against natural disasters. The segmentation also considers the impact of various sheathing techniques and their compliance with regional energy and safety codes.
- By Material: Oriented Strand Board (OSB), Plywood, Gypsum Board, Fiberboard, and Composite Panels.
- By Sheathing Type: Structural Wood Panels, Gypsum-based Sheathing, and specialized Cementitious Sheathing for fire-prone areas.
- By Application: New Residential Construction and Existing Home Renovations & Additions.
- By Residential Type: Single-Family units, Multi-Family (Low-to-Mid Rise) complexes, and Townhouses.
- By Structural Components: Shear Panels, Hold-downs, Anchors, and specialized Fasteners.
Regional Highlights
- North America: The largest market share holder, dominated by the United States where wood-frame construction accounts for over 90% of new residential starts. High demand for seismic and hurricane-resistant designs in the West Coast and Gulf regions drives the market for premium shear wall systems.
- Asia-Pacific: The fastest-growing region, with Japan leading in technical innovation for earthquake resistance. China and India are seeing a rise in light-frame adoption as urban housing demand shifts toward faster, more efficient building methods.
- Europe: Driven by strict sustainability mandates and the Eurocode 5 standards. Germany, Scandinavia, and the UK are pioneers in cross-laminated timber (CLT) and advanced light-frame hybrids.
- Latin America: Growth is centered in Chile and Mexico, where seismic safety is a priority in residential structural design.
- Middle East & Africa: A niche but growing market, particularly in luxury villa developments and sustainable urban projects in the UAE and Saudi Arabia.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Residential Light Frame Shear Wall Market.- Weyerhaeuser Company
- LP Building Solutions
- Georgia-Pacific LLC
- Huber Engineered Woods LLC
- Simpson Strong-Tie Company Inc.
- MiTek Inc.
- Boise Cascade Company
- West Fraser Timber Co. Ltd.
- Roseburg Forest Products
- Tolko Industries Ltd.
- Interfor Corporation
- Canfor Corporation
- Mercer International Inc.
- Stora Enso
- Metsä Group
- binderholz GmbH
Frequently Asked Questions
What is the primary purpose of a residential light frame shear wall?
A residential light frame shear wall is designed to provide lateral resistance to wind and seismic loads. It acts as a vertical structural element that transfers these horizontal forces from the roof and floors down to the foundation, preventing the building from racking or collapsing during extreme events.
How does OSB compare to Plywood in shear wall applications?
OSB (Oriented Strand Board) is generally more cost-effective and offers more uniform structural properties without the knots or voids found in plywood. However, Plywood is often preferred in areas with high moisture exposure as it tends to dry faster and retain its structural integrity better than OSB when repeatedly wetted.
Are prefabricated shear wall panels better than site-built ones?
Prefabricated shear wall panels offer superior quality control and precision, as they are manufactured in controlled factory environments. This leads to more consistent nailing patterns and hold-down installations, often resulting in higher performance ratings and significantly reduced on-site construction time.
Which regions are leading the growth in seismic-resistant shear walls?
Regions located along major fault lines, such as the West Coast of North America (California, Oregon, Washington, British Columbia), Japan, New Zealand, and parts of the Mediterranean, are the primary leaders in the adoption and innovation of seismic-resistant light-frame shear wall technologies.
What role does Building Information Modeling (BIM) play in this market?
BIM allows structural engineers and architects to model lateral forces precisely and optimize the placement and design of shear walls. This digital approach reduces material waste, ensures compliance with local codes before construction begins, and facilitates the production of prefabricated components.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
