Residential HVAC Systems Market
Residential HVAC Systems Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711342 | Published On : October 28, 2026 |
Format : 


 | Author : Jonathan Sikka
Residential Hvac Systems Market Size
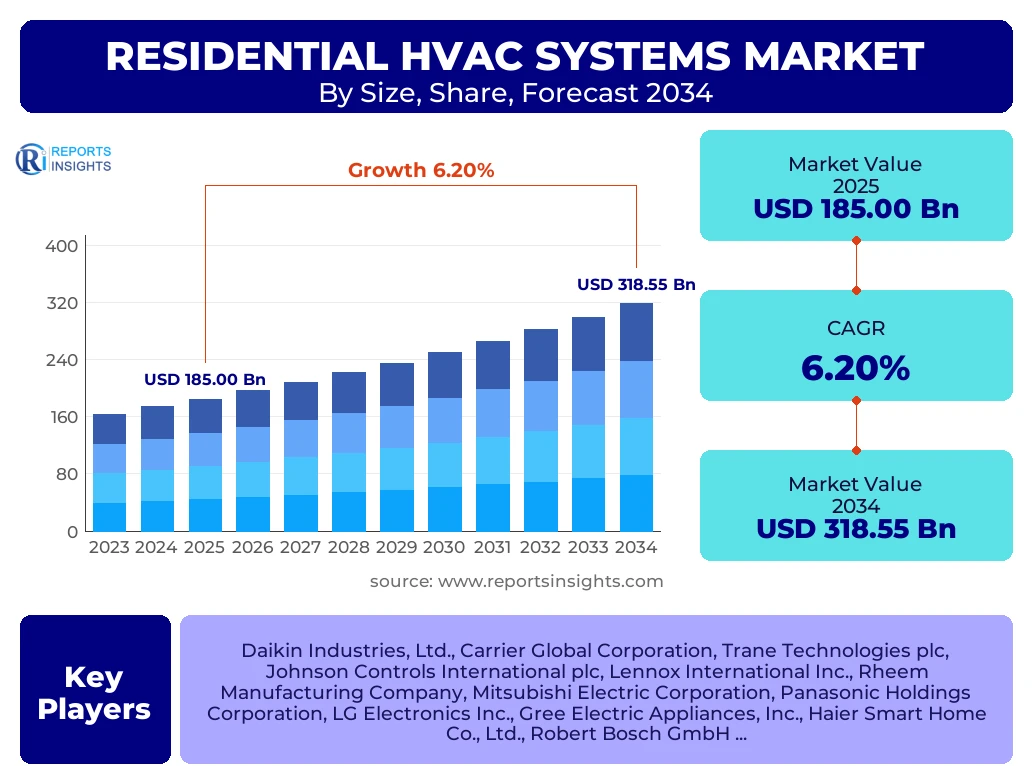
According to Reports Insights Consulting Pvt Ltd, The Residential Hvac Systems Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 196.47 Billion in 2026 and is projected to reach USD 318.55 Billion by the end of the forecast period in 2034.
Key Residential Hvac Systems Market Trends & Insights
The global residential HVAC systems market is undergoing a significant transformation driven by the dual imperatives of environmental sustainability and digital integration. As global temperatures rise and urbanization accelerates, the demand for sophisticated climate control solutions has moved beyond basic comfort to encompass energy efficiency and indoor air quality. Current market intelligence suggests a profound shift toward electrification, particularly in developed economies where government mandates are phasing out fossil-fuel-based heating systems in favor of high-efficiency heat pumps. Furthermore, the integration of Internet of Things (IoT) technology and Artificial Intelligence (AI) is redefining user interaction, allowing for predictive maintenance and automated energy optimization that aligns with smart city initiatives.
- Asia Pacific is the largest and fastest-growing regional market, driven by massive residential construction projects in China and India and an increasing middle-class appetite for air conditioning.
- The Heat Pump segment represents the fastest-growing equipment category due to global decarbonization policies and subsidies for electric heating.
- Smart HVAC systems, integrated with home automation platforms, now hold a significant and rapidly expanding share of the premium residential market.
- The replacement and retrofit segment currently dominates the market share in North America and Europe, as aging infrastructure is upgraded to meet modern efficiency standards.
Key Takeaways Residential Hvac Systems Market Size & Forecast
The trajectory of the residential HVAC market through 2034 is characterized by steady expansion and technological disruption. Market analysts highlight that while the initial capital expenditure for advanced systems remains a consideration for consumers, the long-term operational savings and regulatory compliance are steering the market toward high-value, high-efficiency units. The forecast indicates that regional growth will be uneven, with emerging economies focusing on new installations, while mature markets will see growth through value-added services and smart upgrades. The competitive landscape is also consolidating, as major players acquire niche technology firms to bolster their portfolios in software-driven climate control and sustainable refrigerants.
- China remains the leading country in terms of manufacturing capacity and domestic demand, significantly influencing global pricing and supply chain dynamics.
- The transition to low-Global Warming Potential (GWP) refrigerants is a critical regulatory milestone that will dictate product development cycles over the next decade.
- Indoor Air Quality (IAQ) features, including HEPA filtration and UV-C sterilization, have transitioned from optional add-ons to core consumer requirements post-pandemic.
- Growth in the multi-family housing sector is outpacing single-family homes in urban centers, leading to increased demand for VRF (Variable Refrigerant Flow) systems.
Residential Hvac Systems Market Drivers Analysis
The primary catalysts for the residential HVAC market involve a combination of regulatory pressure and evolving consumer lifestyles. Governments worldwide are implementing stricter energy building codes, such as the SEER2 standards in the United States and the Eco-design Directive in Europe, which necessitate the adoption of more efficient hardware. Simultaneously, the rising frequency of extreme weather events is making climate control an essential utility rather than a luxury, even in regions historically considered temperate.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Electrification & Heat Pump Subsidies | +2.1% | European Union, North America | 2025 - 2034 |
| Rapid Urbanization & Infrastructure Development | +1.8% | India, Southeast Asia, China | 2025 - 2030 |
| Advancements in Smart Home & IoT Integration | +1.2% | Global | 2026 - 2034 |
Residential Hvac Systems Market Restraints Analysis
Despite robust growth prospects, the market faces significant headwinds, primarily related to high upfront costs and the complexity of installation. Modern high-efficiency systems, while economical over their lifespan, require a substantial initial investment that can deter price-sensitive consumers, particularly in high-interest-rate environments where home improvement financing is more expensive.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Installation & Equipment Costs | -0.9% | Developing Economies, LATAM | 2025 - 2028 |
| Shortage of Skilled HVAC Technicians | -0.7% | United States, United Kingdom, Germany | 2025 - 2034 |
Residential Hvac Systems Market Opportunities Analysis
The shift toward "As-a-Service" business models and the integration of renewable energy sources present significant white-space opportunities for market participants. HVAC manufacturers are increasingly exploring subscription-based maintenance and cooling-as-a-service, which lowers the barrier to entry for consumers while providing recurring revenue streams for companies.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Solar-Powered HVAC System Integration | +1.5% | Australia, Middle East, Southwestern US | 2027 - 2034 |
| Development of Low-GWP Refrigerant Systems | +1.3% | Global Compliance Markets | 2025 - 2030 |
Residential Hvac Systems Market Challenges Impact Analysis
The primary challenges involve supply chain volatility and the rapid pace of technological obsolescence. As systems become more reliant on semiconductors and specialized components, disruptions in the global electronics supply chain can lead to significant production delays and price fluctuations that challenge inventory management for distributors.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility (Copper, Aluminum) | -0.5% | Global Manufacturing Hubs | 2025 - 2034 |
| Complex Regulatory Compliance Across Borders | -0.4% | Multinational Corporations | 2025 - 2030 |
Residential Hvac Systems Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global residential HVAC landscape, covering equipment types, technology levels, and distribution channels across all major geographic regions. It provides a granular look at the market dynamics influencing the transition from traditional combustion-based systems to modern, high-efficiency electrical solutions. The research methodology integrates primary insights from industry leaders with secondary statistical data to ensure a robust forecast of market value and volume through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 185.00 Billion |
| Market Forecast in 2034 | USD 318.55 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Daikin Industries, Ltd., Carrier Global Corporation, Trane Technologies plc, Johnson Controls International plc, Lennox International Inc., Rheem Manufacturing Company, Mitsubishi Electric Corporation, Panasonic Holdings Corporation, LG Electronics Inc., Gree Electric Appliances, Inc., Haier Smart Home Co., Ltd., Robert Bosch GmbH, Samsung Electronics Co., Ltd., Fujitsu General Limited, Viessmann Group, Nortek Global HVAC, Danfoss A/S, Midea Group Co., Ltd., Emerson Electric Co. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented primarily by equipment type, which includes heating, cooling, and ventilation. Heating currently holds a dominant position in colder climates, but cooling is the fastest-growing segment globally due to warming trends in previously temperate zones. The technology segment is also bifurcated into traditional and smart systems, with smart systems capturing a higher value share due to integrated software and connectivity features. Furthermore, the market is categorized by installation type, where the replacement of old, inefficient units in developed regions represents a substantial portion of the annual revenue.
- By Equipment Type: Heating (Heat Pumps, Furnaces, Boilers), Cooling (Central AC, Split AC, Window AC, Packaged AC), Ventilation (Air Purifiers, Dehumidifiers, Energy Recovery Ventilators).
- By Installation Type: New Construction (driven by urban housing projects), Retrofit/Replacement (driven by efficiency upgrades and equipment failure).
- By System Type: Ducted (common in North America), Ductless/Mini-split (dominant in APAC and Europe).
- By Fuel Type: Electric, Gas, Oil, Solar-Hybrid.
Regional Highlights
- Asia Pacific: Currently the largest market by value and volume. Rapid urbanization in China, India, and Vietnam, coupled with a growing middle class, is driving massive demand for residential air conditioning and heat pumps.
- North America: A mature market characterized by high replacement rates. The region is seeing a significant shift toward smart HVAC systems and high-efficiency heat pumps, supported by federal tax credits and environmental regulations.
- Europe: The fastest-growing region for heat pump technology. Driven by the REPowerEU plan and the phase-out of gas boilers, countries like Germany, France, and the UK are witnessing unprecedented growth in electric heating solutions.
- Middle East & Africa: Demand is primarily focused on cooling solutions. Extreme temperatures necessitate high-capacity, energy-intensive systems, with a growing trend toward district cooling in high-density residential developments.
- Latin America: A developing market where growth is tied to economic stability and the expansion of the construction sector in Brazil and Mexico.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Residential Hvac Systems Market.- Daikin Industries, Ltd.
- Carrier Global Corporation
- Trane Technologies plc
- Johnson Controls International plc
- Lennox International Inc.
- Rheem Manufacturing Company
- Mitsubishi Electric Corporation
- Panasonic Holdings Corporation
- LG Electronics Inc.
- Gree Electric Appliances, Inc.
- Haier Smart Home Co., Ltd.
- Robert Bosch GmbH
- Samsung Electronics Co., Ltd.
- Fujitsu General Limited
- Viessmann Group
- Nortek Global HVAC
- Danfoss A/S
- Midea Group Co., Ltd.
- Emerson Electric Co.
Frequently Asked Questions
What is the projected growth rate of the Residential HVAC Systems Market?
The market is expected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% from 2025 to 2034, driven by electrification and smart home trends.
Which region currently leads the Residential HVAC market?
Asia Pacific is the leading region, accounting for the largest market share due to extensive residential construction and rising demand in emerging economies like China and India.
What are the primary drivers for the adoption of heat pumps?
Key drivers include government subsidies for carbon reduction, the phasing out of gas boilers, and the superior energy efficiency of modern air-source and ground-source heat pumps.
How is IoT affecting the residential HVAC industry?
IoT enables smart thermostats and connected systems that allow for remote monitoring, energy consumption optimization, and predictive maintenance, enhancing consumer convenience and reducing utility costs.
What are the major challenges facing HVAC manufacturers today?
Manufacturers face challenges such as fluctuating raw material costs, a shortage of certified installation technicians, and the need to comply with rapidly changing refrigerant regulations.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
