Reed Sensor Market
Reed Sensor Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711590 | Published On : November 07, 2026 |
Format : 


 | Author : Shamin Verma
Reed Sensor Market Size
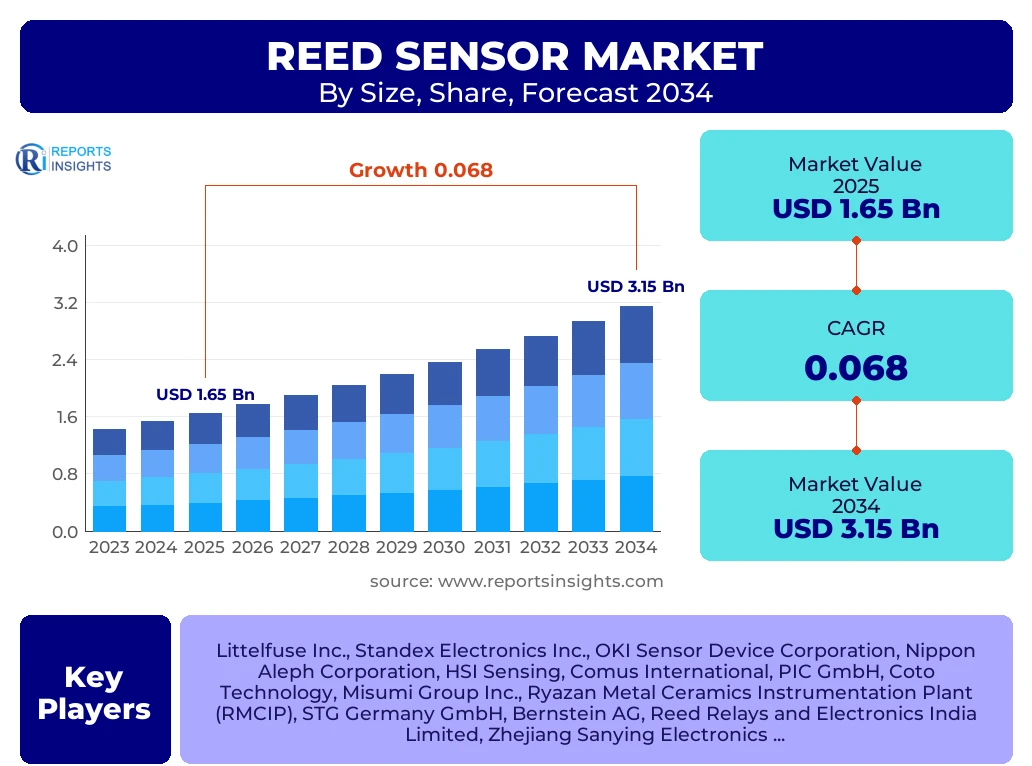
According to Reports Insights Consulting Pvt Ltd, The Reed Sensor Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2025 and 2034. The market is estimated at USD 1.76 Billion in 2026 and is projected to reach USD 3.15 Billion by the end of the forecast period in 2034.
Key Reed Sensor Market Trends & Insights
The global reed sensor market is undergoing a significant transformation driven by the rapid expansion of the Internet of Things (IoT) ecosystem and the increasing electrification of the automotive sector. Modern industrial applications are shifting toward hermetically sealed sensing solutions that offer high reliability in harsh environments, positioning reed sensors as a preferred choice over mechanical switches. Regional analysis indicates that the Asia-Pacific region remains the primary engine of growth, supported by massive electronics manufacturing hubs and a surging demand for smart home appliances. Furthermore, the integration of reed sensors into high-voltage battery management systems for electric vehicles has emerged as a critical trend, ensuring safety and precision in energy distribution. Competitive benchmarking reveals that key players are focusing on miniaturization and the development of high-power switching capabilities to meet the stringent requirements of medical and aerospace applications.
- Largest Region: Asia-Pacific (APAC) currently holds the largest market share, driven by extensive manufacturing activity in China, Japan, and South Korea.
- Fastest Growing Region: North America is expected to witness the highest CAGR due to rapid advancements in industrial automation and medical technology.
- Largest Segment by Type: The Form A (Normally Open) segment dominates the market share owing to its versatile applications in security and consumer electronics.
- Leading End-Use Industry: The automotive sector remains the primary contributor to market value, particularly through safety systems and fluid level monitoring.
Key Takeaways Reed Sensor Market Size & Forecast
The trajectory of the reed sensor market is heavily influenced by the global push for energy efficiency and the miniaturization of electronic components. Market participants are increasingly investing in research and development to enhance the sensitivity and durability of reed switches, which are the core components of these sensors. As industries migrate toward Industry 4.0, the demand for non-contact sensing solutions that can operate without external power sources becomes paramount. The forecast period 2025-2034 suggests a steady rise in adoption within the healthcare sector, where reed sensors are used in implantable devices and diagnostic equipment due to their biocompatibility and zero-leakage current characteristics. Market stability is further bolstered by the replacement of traditional Hall effect sensors in specific niches where magnetic interference or power consumption are critical concerns.
- Sustainability and Energy Efficiency: Reed sensors require no power for operation in their passive state, making them ideal for battery-operated IoT devices.
- Automotive Electrification: The surge in Electric Vehicle (EV) production is a primary catalyst for market expansion, specifically for lid sensing and charging port security.
- Smart Infrastructure: Increasing investments in smart city projects across Europe and Asia are driving the demand for reed-based security and utility metering systems.
- Technological Convergence: The combination of reed sensors with advanced materials like rhodium and ruthenium is enhancing contact reliability and lifespan.
Reed Sensor Market Drivers Analysis
The primary driver for the reed sensor market is the exponential growth of the global automotive industry, particularly the transition toward electric and autonomous vehicles. In these modern platforms, reed sensors are essential for monitoring various functions such as brake fluid levels, seatbelt positioning, and door closure verification. Their ability to function reliably in extreme temperatures and under significant vibration makes them superior to many alternative technologies in safety-critical environments.
Additionally, the proliferation of smart home technology and wearable devices is significantly boosting demand. Reed sensors are extensively used in security systems for doors and windows, as well as in consumer electronics for laptop lid closures and fluid level detection in high-end appliances. The zero-power consumption feature of these sensors is particularly attractive for manufacturers aiming to extend the battery life of wireless connected devices.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Automotive Safety and EV Integration | +2.4% | Global (Strongest in China/Germany) | 2025-2034 |
| Expansion of IoT and Smart Home Ecosystems | +1.9% | North America and Europe | 2025-2030 |
| Growth in Medical Device Miniaturization | +1.5% | United States and Japan | 2026-2034 |
Reed Sensor Market Restraints Analysis
One of the significant restraints facing the reed sensor market is the intense competition from alternative sensing technologies, most notably Hall effect sensors. While reed sensors offer advantages in terms of power consumption and isolation, Hall effect sensors are often preferred in high-speed switching applications and environments where physical fragility is a concern. The glass encapsulation of reed sensors makes them susceptible to damage during high-impact manufacturing processes or in heavy-duty industrial usage.
Furthermore, the volatility in the prices of precious metals used for contact coating, such as rhodium and ruthenium, presents a challenge for cost-effective mass production. Fluctuations in raw material costs can lead to pricing instability, forcing manufacturers to either absorb the costs or pass them on to consumers, which may hinder adoption in cost-sensitive markets like low-end consumer electronics.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Solid-State Hall Effect Sensors | -1.2% | Global | 2025-2034 |
| Raw Material Price Volatility (Precious Metals) | -0.8% | Asia and Europe | 2025-2028 |
Reed Sensor Market Opportunities Analysis
The emergence of Industry 4.0 and the industrial internet of things (IIoT) provides a substantial opportunity for reed sensor manufacturers. As factories move toward higher levels of automation, there is an increasing need for sensors that can operate in hazardous or explosive environments. Because reed sensors are hermetically sealed, they do not produce sparks, making them ideal for use in chemical processing plants, oil and gas refineries, and mining operations.
Moreover, the medical technology sector offers untapped potential for high-precision reed sensors. Advanced applications such as capsule endoscopy, pacemaker programming, and hearing aids require ultra-miniature sensors with exceptional reliability. The development of MEMS-based reed sensors could revolutionize this segment, allowing for even smaller form factors and integration into a wider range of implantable medical devices.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Hazardous Environment Industrial Automation | +2.1% | Middle East and North America | 2026-2034 |
| Advanced Medical Implantables and Diagnostics | +1.7% | Germany, US, and Switzerland | 2027-2034 |
Reed Sensor Market Challenges Impact Analysis
The technical challenge of miniaturization without compromising performance remains a critical hurdle for the industry. As electronic devices become smaller and more complex, reed sensors must also scale down. However, reducing the size of the glass envelope and the reed blades can lead to decreased sensitivity and a shorter operational lifespan, requiring sophisticated engineering and precision manufacturing techniques that can increase production costs.
Another challenge is the environmental impact and regulatory compliance regarding the materials used in sensor production. Stringent regulations such as RoHS and REACH in the European Union require manufacturers to find sustainable and non-toxic alternatives for certain components. Adapting to these evolving regulatory landscapes while maintaining high performance and competitive pricing is a constant struggle for global manufacturers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Technical Barriers in Ultra-Miniaturization | -0.9% | Japan and South Korea | 2025-2030 |
| Regulatory Compliance and Material Sustainability | -0.5% | European Union | 2025-2034 |
Reed Sensor Market - Updated Report Scope
The updated report on the Reed Sensor Market provides a comprehensive analysis of the global landscape, encompassing historical data from 2020 to 2024 and forward-looking projections through 2034. The scope includes a detailed breakdown of market dynamics, including macro and micro-economic factors influencing growth across different geographies. It evaluates the competitive landscape by profiling industry leaders and analyzing their strategic initiatives, such as mergers, acquisitions, and technological innovations. This report serves as a strategic guide for stakeholders to identify high-growth segments and navigate the complexities of the global supply chain.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.65 Billion |
| Market Forecast in 2034 | USD 3.15 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Littelfuse Inc., Standex Electronics Inc., OKI Sensor Device Corporation, Nippon Aleph Corporation, HSI Sensing, Comus International, PIC GmbH, Coto Technology, Misumi Group Inc., Ryazan Metal Ceramics Instrumentation Plant (RMCIP), STG Germany GmbH, Bernstein AG, Reed Relays and Electronics India Limited, Zhejiang Sanying Electronics, ifm electronic gmbh, ABB Ltd, TE Connectivity, SMC Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The reed sensor market is segmented based on contact form, mount type, and industry vertical, providing a granular view of the various applications and technical specifications. The Form A segment continues to lead the market due to its simplicity and widespread use in door/window sensors and liquid level indicators. In terms of mounting, Surface Mount (SMD) technology is gaining traction as electronic assemblies become more compact and automated, allowing for high-density PCB layouts in smartphones and wearable technology.
- By Contact Form:
- Form A (Normally Open): The most common type used in general sensing applications.
- Form B (Normally Closed): Utilized in safety-critical systems where an alert is triggered upon contact break.
- Form C (Changeover): Used in complex switching logic where toggling between two states is required.
- By Mount Type:
- Surface Mount (SMD): Preferred for high-volume automated electronic manufacturing.
- Through-hole (THT): Used in robust industrial applications requiring strong mechanical bonds.
- Screw/Panel Mount: Common in heavy machinery and security infrastructure.
- By Industry Vertical:
- Automotive: Safety systems, fluid monitoring, and EV charging.
- Consumer Electronics: Laptops, white goods, and mobile devices.
- Medical: Diagnostic tools and implantable medical devices.
- Industrial: Automation, robotics, and hazardous environment monitoring.
- Telecommunication: Signal switching and infrastructure protection.
Regional Highlights
The regional distribution of the reed sensor market reflects the global manufacturing landscape. Asia-Pacific is the dominant region, accounting for over 40% of the market share. This dominance is attributed to the presence of major electronics manufacturers in China and Japan, coupled with the rapid growth of the automotive sector in India. The region is also a hub for reed switch production, ensuring a steady supply of components for downstream sensor assembly.
- North America: This region is characterized by high adoption rates in the medical and aerospace sectors. The United States leads in the development of specialized sensors for high-reliability applications, contributing significantly to the regional value.
- Europe: Driven by Germany’s automotive excellence and the Nordic countries' focus on smart grid technology. Strict environmental regulations are pushing manufacturers toward sustainable production methods.
- Asia-Pacific: The fastest-growing and largest market, fueled by consumer electronics demand and massive investments in 5G infrastructure and EV production.
- Latin America & MEA: These regions are witnessing gradual growth, primarily driven by investments in the oil and gas sector and the modernization of utility grids in countries like Brazil and the UAE.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Reed Sensor Market.- Littelfuse Inc.
- Standex Electronics Inc.
- OKI Sensor Device Corporation
- Nippon Aleph Corporation
- HSI Sensing
- Comus International
- PIC GmbH
- Coto Technology
- Misumi Group Inc.
- Ryazan Metal Ceramics Instrumentation Plant (RMCIP)
- STG Germany GmbH
- Bernstein AG
- Reed Relays and Electronics India Limited
- Zhejiang Sanying Electronics
- ifm electronic gmbh
- ABB Ltd
- TE Connectivity
- SMC Corporation
Frequently Asked Questions
What are the primary advantages of reed sensors over Hall effect sensors?
Reed sensors offer several advantages, including zero power consumption in a passive state, high isolation resistance, and the ability to switch higher voltages and currents compared to solid-state Hall effect sensors. They are also hermetically sealed, making them immune to dust, moisture, and corrosion.
How is the growth of Electric Vehicles (EVs) impacting the reed sensor market?
The growth of EVs is a major driver, as reed sensors are used in battery management systems, charging port lids, and seatbelt tensioners. Their reliability in high-voltage environments and non-contact operation makes them essential for automotive safety and efficiency.
Which industry vertical is expected to grow the fastest during the forecast period?
The medical industry vertical is expected to see the fastest growth due to the increasing demand for miniature, high-reliability sensors in implantable devices, surgical tools, and diagnostic equipment where safety and precision are paramount.
What materials are commonly used for the contacts in reed sensors?
Reed sensor contacts are typically coated with precious metals such as rhodium, ruthenium, or iridium. These materials are chosen for their excellent conductivity and resistance to contact wear, ensuring millions of switching cycles over the sensor's life.
What are the main factors limiting the adoption of reed sensors in some applications?
Main limiting factors include the physical fragility of the glass envelope, sensitivity to external magnetic interference, and the relatively larger size compared to some semiconductor-based sensors. Additionally, high-speed applications may prefer solid-state alternatives due to the mechanical nature of reed blades.
Author
S
Shamin Verma is a Senior Analyst Semiconductor and Electronics Research with over 7+ years of experience in the Semiconductor and Electronics Industry. She specializes in semiconductor market intelligence, electronics supply chain analysis, wafer fabrication trends, competitive benchmarking, demand forecasting, component pricing analysis, emerging technology assessment, integrated circuit market evaluation, and industry ecosystem research. Her expertise in translating complex market data into strategic insights enables organizations to make informed business decisions, identify high-growth opportunities, optimize operational planning, anticipate evolving technology trends, and strengthen their competitive positioning in the global semiconductor and electronics market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
