Recycled Copper Market
Recycled Copper Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711695 | Published On : November 12, 2026 |
Format : 


 | Author : Erika Grotto
Recycled Copper Market Size
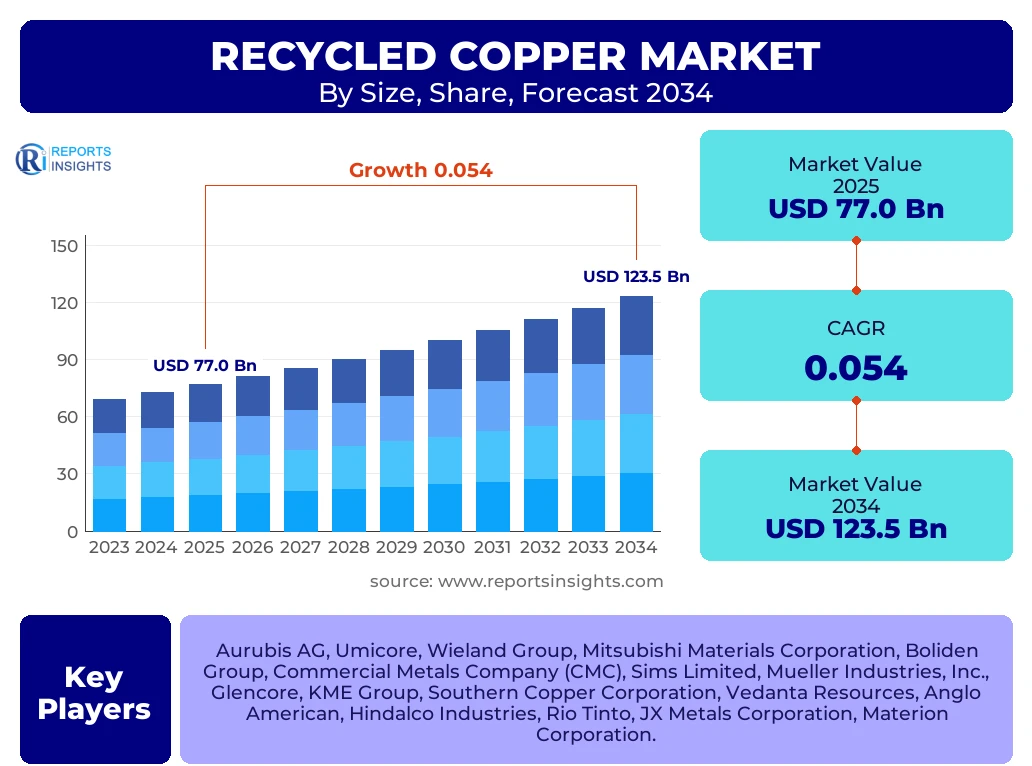
According to Reports Insights Consulting Pvt Ltd, The Recycled Copper Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 81.2 Billion in 2026 and is projected to reach USD 123.5 Billion by the end of the forecast period in 2034.
Key Recycled Copper Market Trends & Insights
The global shift toward a circular economy and the intensifying pressure on mining industries to reduce carbon footprints are the primary catalysts reshaping the recycled copper landscape. As industries pivot toward decarbonization, secondary copper production—which consumes up to 85% less energy than primary extraction—has transitioned from a peripheral activity to a core strategic necessity for global manufacturing hubs. Market analysis indicates a sharp rise in technological integration, particularly in automated sensor-based sorting systems that enhance the purity of recovered scrap, thereby increasing the marketability of No. 2 copper and light copper grades. Furthermore, the rapid electrification of the global automotive sector is creating a closed-loop ecosystem where end-of-life electric vehicle (EV) components are becoming a vital feedstock for new production cycles.
- Largest Region: Asia Pacific remains the dominant regional force, accounting for over 45% of the total market share, driven by China’s massive smelting capacity and secondary metal processing infrastructure.
- Fastest Growing Region: North America is projected to witness the highest growth rate during the forecast period due to aggressive infrastructure modernization and strict federal mandates regarding recycled content in electronics.
- Largest Segment by Share: The Building and Construction segment holds the majority share, as copper piping and wiring from demolition activities provide a consistent and high-volume stream of scrap material.
- Emerging Trend: The adoption of hydrometallurgical recycling processes is gaining traction, allowing for the recovery of copper from complex electronic waste with minimal environmental emissions.
Key Takeaways Recycled Copper Market Size & Forecast
The market forecast reflects a robust trajectory fueled by the widening gap between primary copper supply and the surging demand for conductive materials in green energy infrastructure. Analysts observe that the supply-side constraints in traditional mining are forcing Tier-1 manufacturers to secure long-term scrap supply agreements, effectively "urban mining" to mitigate geopolitical risks associated with ore imports. The convergence of ESG (Environmental, Social, and Governance) mandates and the economic viability of scrap processing ensures that recycled copper is no longer viewed merely as a secondary alternative but as a primary strategic asset for the 21st-century industrial economy.
- Leading Country: China continues to lead both consumption and processing of copper scrap, although recent policy shifts toward higher-quality scrap imports are redistributing the processing load to Southeast Asian nations.
- Key Market Driver: The global energy transition, specifically the build-out of solar and wind farms, is significantly increasing the per-capita demand for recycled copper.
- Economic Impact: Rising LME (London Metal Exchange) copper prices are making recycling more economically attractive, encouraging informal collection sectors to formalize and scale their operations.
- Material Evolution: High-purity "Millberry" scrap remains the most sought-after grade, commanding premiums nearly identical to cathode copper.
Recycled Copper Market Drivers Analysis
The primary driver for the recycled copper market is the global mandate for decarbonization. Primary copper mining is increasingly energy-intensive and environmentally disruptive, leading to a structural shift where secondary copper becomes the preferred choice for eco-conscious brands. Additionally, the proliferation of electronics and the shortening lifecycles of consumer gadgets provide a continuous influx of feedstock. The electrification of everything, from home heating to industrial transport, ensures that the demand for copper—and by extension, recycled copper—remains insulated from cyclical economic downturns.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Transition to Electric Vehicles (EVs) | +1.8% | Europe & China | 2025 - 2034 |
| Implementation of Circular Economy Policies | +1.2% | European Union | 2025 - 2030 |
| Infrastructure Modernization & Urbanization | +0.9% | India & Southeast Asia | 2026 - 2034 |
| Rising Cost of Primary Mining Operations | +0.7% | Global | 2025 - 2034 |
Recycled Copper Market Restraints Analysis
Despite the positive outlook, the market faces significant hurdles in the form of scrap quality and contamination. Copper scrap is often alloyed with other metals or bonded to plastics, making separation expensive and technically demanding. Furthermore, the volatility of global metal prices can deter investment in large-scale recycling facilities, as profit margins are often thin and highly dependent on the spread between scrap purchase prices and finished copper prices. Regulatory complexities regarding the transboundary movement of hazardous waste also act as a bottleneck for international scrap trade.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Import Regulations on Low-Grade Scrap | -0.5% | China & Malaysia | 2025 - 2028 |
| Technical Complexity in E-Waste Separation | -0.4% | Global | 2025 - 2034 |
Recycled Copper Market Opportunities Analysis
The integration of Artificial Intelligence (AI) and Machine Learning (ML) into sorting facilities presents a massive opportunity to maximize yield from low-grade scrap. By automating the identification of copper-bearing components in mixed waste streams, companies can significantly reduce labor costs and improve purity levels. There is also an emerging opportunity in the "closed-loop" recycling partnerships between electronics manufacturers and recycling firms, ensuring that old products are directly funneled back into the production line, thereby securing supply chains against global market shocks.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Advanced Smelting Technologies | +1.5% | Germany & Japan | 2026 - 2034 |
| Investment in African E-waste Collection | +0.8% | Nigeria & South Africa | 2027 - 2034 |
Recycled Copper Market Challenges Impact Analysis
The informal recycling sector remains a significant challenge, particularly in developing economies, where rudimentary smelting practices lead to high environmental pollution and poor metal recovery rates. Bridging the gap between the informal and formal sectors is essential for market health. Additionally, the increasing use of complex alloys in modern technology makes it harder to extract pure copper without sophisticated and energy-heavy chemical processes, which can sometimes negate the environmental benefits of recycling.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Contamination from Hazardous Materials | -0.6% | Global | 2025 - 2030 |
| Logistical Constraints & Shipping Costs | -0.3% | Trans-Pacific Routes | 2025 - 2027 |
Recycled Copper Market - Updated Report Scope
This report provides a granular analysis of the global recycled copper ecosystem, encompassing the entire value chain from collection and sorting to smelting and refining. The scope includes a detailed evaluation of various scrap grades, including No. 1 and No. 2 copper, and their application across diverse industrial verticals. The analysis covers the period from 2020 to 2034, providing a comprehensive view of historical trends and future projections influenced by geopolitical shifts, technological breakthroughs, and evolving environmental regulations.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 77.0 Billion |
| Market Forecast in 2034 | USD 123.5 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Aurubis AG, Umicore, Wieland Group, Mitsubishi Materials Corporation, Boliden Group, Commercial Metals Company (CMC), Sims Limited, Mueller Industries, Inc., Glencore, KME Group, Southern Copper Corporation, Vedanta Resources, Anglo American, Hindalco Industries, Rio Tinto, JX Metals Corporation, Materion Corporation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The recycled copper market is segmented based on the source of the scrap, the grade of the material, and the final processing method. The source of scrap is a critical indicator of material quality, with the Building and Construction sector providing the most consistent flow of high-grade copper wire and tube. In contrast, the Electrical and Electronics segment is the fastest-growing source, though it requires more complex processing due to the presence of plastics and other precious metals. Grade segmentation is essential for pricing, where No. 1 Copper (unalloyed and clean) fetches the highest market value, whereas No. 2 Copper requires more intensive refining to remove coatings and oxidation.
- By Source:
- Building & Construction (Pipes, Wiring, Roofing)
- Electrical & Electronics (Cables, Circuit Boards, Motors)
- Transportation (Automotive wiring, Radiators, EV batteries)
- Industrial Machinery (Heat Exchangers, Transformers)
- Consumer Products (Appliances, Cookware)
- By Grade:
- No. 1 Copper Scrap (Millberry, Candy, Clove)
- No. 2 Copper Scrap (Birch, Cliff)
- Light Copper (Dream)
- Copper-Nickel & Other Alloys
- By Application:
- Wire and Cable Production
- Brass and Bronze Ingots
- Alloying Elements
- Electroplating
Regional Highlights
- Asia Pacific: The largest market globally, APAC is led by China, which consumes over 50% of the world’s copper scrap. The region’s growth is sustained by rapid industrialization and the presence of massive secondary smelting clusters in China, Vietnam, and Thailand.
- North America: This region is characterized by high-efficiency collection systems and a growing focus on domestic supply chains. The US market is seeing significant investment in new secondary smelting facilities to reduce reliance on exported scrap and imported cathodes.
- Europe: Europe is the most advanced region in terms of recycling regulations and circular economy integration. Germany, Italy, and Belgium are hubs for advanced copper refining, focusing on high-purity recovery from complex electronic waste.
- Latin America: Countries like Brazil and Mexico are emerging as significant collection points for industrial scrap, with growth driven by the local automotive and manufacturing industries.
- Middle East & Africa: While currently smaller in share, the MEA region is witnessing a rise in infrastructure projects and better waste management practices, particularly in the GCC countries, providing untapped potential for copper recovery.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Recycled Copper Market.- Aurubis AG
- Umicore
- Wieland Group
- Mitsubishi Materials Corporation
- Boliden Group
- Commercial Metals Company (CMC)
- Sims Limited
- Mueller Industries, Inc.
- Glencore
- KME Group
- Southern Copper Corporation
- Vedanta Resources
- Anglo American
- Hindalco Industries
- Rio Tinto
- JX Metals Corporation
- Materion Corporation
- Luvata
- Sherritt International
Frequently Asked Questions
What is the current market value of the Recycled Copper Market?
As of 2025, the global Recycled Copper Market is valued at approximately USD 77.0 Billion, with expectations to reach over USD 123 Billion by 2034 due to increased demand for sustainable materials.
Why is recycled copper becoming more important than primary copper?
Recycled copper is more energy-efficient, requiring up to 85% less energy to produce than primary copper. It also helps companies meet ESG goals and reduces the environmental impact of mining operations.
Which industry is the largest consumer of recycled copper?
The Building and Construction industry is the largest consumer, utilizing recycled copper for electrical wiring, plumbing, and architectural features due to its durability and conductivity.
What are the differences between No. 1 and No. 2 copper scrap?
No. 1 copper scrap consists of clean, unalloyed, and uncoated copper with a minimum 99% copper content. No. 2 copper scrap includes oxidized or coated copper and requires more refining, usually containing about 94-96% copper.
How does the growth of Electric Vehicles (EVs) affect the copper recycling market?
EVs require significantly more copper than internal combustion engine vehicles. As first-generation EVs reach their end-of-life, they provide a rich source of high-quality copper scrap, fueling the growth of secondary copper markets.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
