Ready To Drink Cocktails Market
Ready To Drink Cocktails Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711136 | Published On : October 11, 2026 |
Format : 


 | Author : Hameer Thakur
Ready To Drink Cocktails Market Size
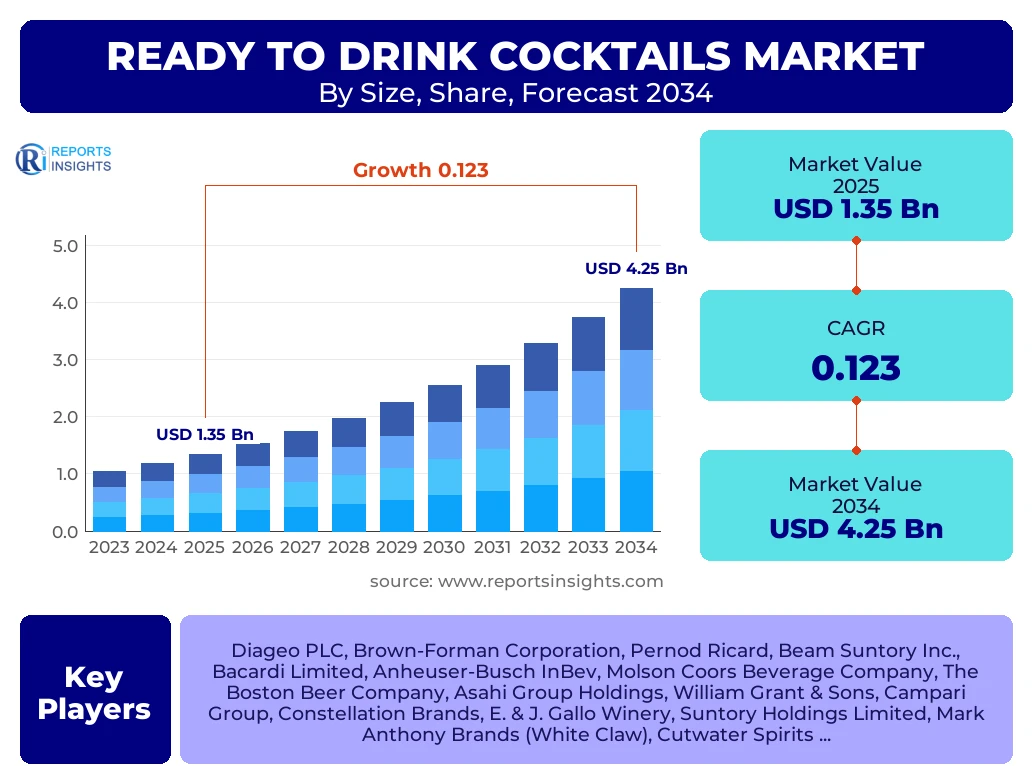
According to Reports Insights Consulting Pvt Ltd, The Ready To Drink Cocktails Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 12.3% between 2025 and 2034. The market is estimated at USD 1.52 Billion in 2026 and is projected to reach USD 4.25 Billion by the end of the forecast period in 2034.
Key Ready To Drink Cocktails Market Trends & Insights
The Ready To Drink (RTD) Cocktails market is undergoing a significant transformation driven by the premiumization of spirits and the evolving consumer preference for convenience without compromising quality. Modern consumers, particularly Millennials and Gen Z, are increasingly gravitating toward high-quality, spirit-based cocktails that offer the same complexity as a freshly mixed drink at a bar. This shift has forced manufacturers to move beyond traditional malt-based beverages toward premium vodka, tequila, and gin-based formulations. The market is also seeing a surge in "better-for-you" options, characterized by low-calorie, low-sugar, and natural ingredient profiles, reflecting a broader global trend toward health and wellness. Furthermore, packaging innovation, such as the rise of sleek aluminum cans and sustainable glass formats, has enhanced portability and expanded the occasions for consumption, from outdoor festivals to casual home gatherings.
- North America remains the largest regional market, driven by a deep-rooted cocktail culture and high demand for spirit-based convenience products.
- Asia Pacific is identified as the fastest-growing region, fueled by rising disposable incomes and the rapid adoption of Western beverage trends in countries like India, China, and Vietnam.
- Spirit-based RTD cocktails represent the largest segment in terms of market share, significantly outpacing malt and wine-based alternatives.
- Tequila-based RTD cocktails are currently the fastest-growing spirit sub-segment, capitalizing on the global popularity of Margaritas and Palomas.
- Hypermarkets and supermarkets continue to be the dominant distribution channel, although e-commerce is witnessing the highest growth rate.
Key Takeaways Ready To Drink Cocktails Market Size & Forecast
The global Ready To Drink Cocktails market is positioned for robust growth over the next decade, supported by a fundamental change in the beverage alcohol landscape. The convergence of convenience and premium quality has made RTDs a staple in the modern consumer’s repertoire. Strategic partnerships between traditional spirits companies and soft drink giants have further accelerated market penetration, allowing for unique flavor profiles and extensive distribution reach. As the market matures, the focus is shifting toward niche flavor profiles, functional ingredients, and sustainable supply chains. The forecast period is expected to see a consolidation of market players as large beverage conglomerates acquire successful craft RTD brands to bolster their portfolios and capture emerging market niches.
- The United States is the leading country globally, accounting for a substantial portion of the total market value due to its mature retail infrastructure and diverse consumer base.
- The shift from hard seltzers to spirit-based RTDs is a critical market pivot that is expected to sustain high CAGR levels through 2034.
- Canned packaging holds the majority share of the market due to its portability, durability, and superior recyclability compared to other formats.
- On-trade consumption of RTD cocktails is rising in venues like stadiums, cinemas, and airplanes where speed of service is paramount.
- Technological advancements in cold-fill and carbonation processes are enabling manufacturers to maintain the integrity of complex flavor notes over longer shelf lives.
Ready To Drink Cocktails Market Drivers Analysis
The primary driver of the Ready To Drink Cocktails market is the intensifying consumer demand for convenience in the beverage sector. As urban lifestyles become more fast-paced, the ability to enjoy a sophisticated cocktail without the need for specialized tools, multiple ingredients, or bartending skills has become highly attractive. This trend is bolstered by the premiumization wave, where consumers are willing to pay a price premium for products containing real spirits and natural botanicals rather than artificial flavorings. Additionally, the expansion of distribution channels, particularly the rise of direct-to-consumer (DTC) platforms and specialized alcohol delivery services, has significantly lowered the barrier to entry for new brands and increased product visibility.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Consumer Demand for Convenience and Portability | +4.2% | Global (High in North America & Europe) | 2025 - 2034 |
| Premiumization and Use of High-Quality Spirits | +3.5% | North America, United Kingdom | 2025 - 2030 |
| Expansion of E-commerce and Delivery Apps | +2.8% | China, USA, Brazil | 2026 - 2034 |
| Flavor Innovation and Diversification | +1.8% | Western Europe, Australia | 2025 - 2034 |
Ready To Drink Cocktails Market Restraints Analysis
Despite the strong growth trajectory, the market faces significant restraints, primarily in the form of complex and varying regulatory frameworks. Many jurisdictions apply higher excise taxes to spirit-based RTDs compared to malt-based beverages or beer, which can lead to higher retail prices and dampen consumer demand. Furthermore, the growing global movement toward health and wellness has led a segment of the population to reduce alcohol consumption, posing a threat to traditional high-ABV cocktail products. Stringent labeling requirements and marketing restrictions on alcoholic beverages in certain regions also present hurdles for brand expansion and international trade.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Excise Taxes on Spirit-Based Products | -2.1% | USA, India, Thailand | 2025 - 2034 |
| Strict Advertising and Distribution Regulations | -1.5% | France, Norway, Middle East | 2025 - 2030 |
| Health Consciousness and Alcohol Moderation Trends | -1.2% | Global (Specifically Gen Z) | 2027 - 2034 |
Ready To Drink Cocktails Market Opportunities Analysis
The emergence of the "low and no" alcohol movement presents a unique opportunity for RTD cocktail manufacturers to innovate. By developing sophisticated non-alcoholic or low-ABV (Alcohol by Volume) RTD cocktails that mimic the flavor profile of classic drinks, companies can tap into the expanding "sober-curious" demographic. Additionally, there is significant untapped potential in the integration of functional ingredients, such as adaptogens or antioxidants, which align with the holistic health interests of modern consumers. Geographical expansion into emerging markets in Africa and Latin America, where the middle class is growing and Western drinking habits are being adopted, also offers a long-term growth lever for global beverage brands.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Growth of Non-Alcoholic and Low-ABV RTDs | +3.9% | Western Europe, North America | 2026 - 2034 |
| Untapped Emerging Markets (APAC & LATAM) | +2.5% | India, Vietnam, Mexico | 2028 - 2034 |
| Strategic Partnerships with Non-Alcoholic Brands | +1.7% | Global | 2025 - 2030 |
Ready To Drink Cocktails Market Challenges Impact Analysis
One of the most pressing challenges in the RTD cocktail market is the fierce competition for shelf space in retail environments. As the number of brands and SKUs (Stock Keeping Units) proliferates, both established giants and small craft producers must compete for limited visibility in coolers and on shelves. Supply chain volatility, including fluctuations in the cost of raw materials like aluminum for cans and the logistics of transporting glass bottles, can also squeeze profit margins. Moreover, maintaining brand loyalty in an environment characterized by "repertoire drinking," where consumers frequently switch between different brands and beverage types, requires constant innovation and high marketing expenditures.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shelf Space Saturation and Intense Competition | -1.8% | USA, UK | 2025 - 2034 |
| Raw Material and Packaging Cost Volatility | -1.3% | Global | 2025 - 2029 |
| Maintaining Product Quality and Stability Over Time | -0.9% | Global | 2025 - 2034 |
Ready To Drink Cocktails Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the global Ready To Drink Cocktails market, covering historical data from 2020 to 2024 and providing detailed projections for the forecast period of 2026 to 2034. The scope includes a meticulous breakdown of the market by base spirit, packaging type, distribution channel, and regional performance. The report identifies key growth drivers, technological advancements, and regulatory hurdles that will shape the industry's future. By profiling the leading 20 companies, the report offers insights into competitive strategies, product launches, and merger and acquisition activities, providing stakeholders with a clear roadmap for investment and strategic planning.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.35 Billion |
| Market Forecast in 2034 | USD 4.25 Billion |
| Growth Rate | 12.3% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Diageo PLC, Brown-Forman Corporation, Pernod Ricard, Beam Suntory Inc., Bacardi Limited, Anheuser-Busch InBev, Molson Coors Beverage Company, The Boston Beer Company, Asahi Group Holdings, William Grant & Sons, Campari Group, Constellation Brands, E. & J. Gallo Winery, Suntory Holdings Limited, Mark Anthony Brands (White Claw), Cutwater Spirits, Heineken N.V., Manchester Drinks Company, Two Chicks Cocktails, and Surfside Spirits. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Ready To Drink Cocktails market is segmented based on the base spirit, which is the primary determinant of flavor and consumer appeal. Currently, vodka-based RTDs hold a significant portion of the market due to vodka's versatile nature, but tequila-based options are growing rapidly. Packaging segmentation reveals a clear preference for aluminum cans due to their environmental benefits and portability. The distribution channel is bifurcated into on-trade and off-trade, with the off-trade segment being the primary revenue generator as consumers increasingly choose to drink at home. ABV (Alcohol by Volume) content is another crucial segment, as it caters to different consumption occasions, from light daytime socializing to more intense evening settings.
- By Base Spirit: Vodka, Tequila, Gin, Whiskey, Rum, and Malt/Wine-based blends.
- By Packaging Type: Sleek Cans, Standard Cans, Glass Bottles, and Tetra Packs.
- By Flavor Profile: Citrus, Tropical, Berry, Spiced, and Classic (Margarita, Mojito, Negroni).
- By Distribution Channel: Online Retail, Hypermarkets/Supermarkets, Specialist Liquor Stores, Convenience Stores, and On-Trade venues (Stadiums/Arenas/Airlines).
- By ABV Content: Low ABV (<5%), Mid-Range (5%-8%), and High Strength (>8%).
Regional Highlights
- North America: This region is the largest market globally, with the United States acting as the primary hub for innovation and consumption. The market is driven by a shift away from beer and hard seltzers toward spirit-based RTDs.
- Europe: Europe holds a substantial market share, particularly in the UK and Germany, where there is a long-standing tradition of gin and tonic RTDs and a growing interest in premium, canned pre-mixed cocktails.
- Asia Pacific: This is the fastest-growing region, with countries like Japan (the birthplace of the "Chu-Hi") leading the way, and China and India showing immense potential due to the rising middle-class preference for international spirit brands.
- Latin America: Led by Mexico and Brazil, this region is seeing growth in tequila and rum-based RTDs, often integrated with local tropical fruit flavors.
- Middle East and Africa: While currently the smallest market due to cultural and regulatory factors, certain urban centers in South Africa and the UAE are showing increased demand for premium RTD beverages in high-end hospitality sectors.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Ready To Drink Cocktails Market.- Diageo PLC
- Brown-Forman Corporation
- Pernod Ricard
- Beam Suntory Inc.
- Bacardi Limited
- Anheuser-Busch InBev
- Molson Coors Beverage Company
- The Boston Beer Company
- Asahi Group Holdings
- William Grant & Sons
- Campari Group
- Constellation Brands
- E. & J. Gallo Winery
- Suntory Holdings Limited
- Mark Anthony Brands (White Claw)
- Cutwater Spirits
- Heineken N.V.
- Manchester Drinks Company
- Two Chicks Cocktails
- Surfside Spirits
Frequently Asked Questions
What is the current size of the global Ready To Drink Cocktails market?
The global Ready To Drink Cocktails market is estimated to be valued at USD 1.35 Billion in 2025 and is expected to grow significantly to reach USD 4.25 Billion by 2034.
Which region is the fastest growing in the RTD Cocktails market?
Asia Pacific is the fastest-growing region, driven by the rapid adoption of spirit-based convenience beverages in countries like India, China, and Vietnam.
What are the primary factors driving the growth of this market?
The primary drivers include the increasing consumer demand for convenience, the premiumization of spirits, the shift from malt to spirit-based RTDs, and the expansion of e-commerce distribution channels.
Which spirit type dominates the RTD Cocktail segment?
Vodka remains the dominant base spirit due to its versatility, though Tequila-based RTDs are currently the fastest-growing sub-segment globally.
How is the "better-for-you" trend impacting the market?
The trend is driving manufacturers to launch low-calorie, low-sugar, and natural ingredient-based cocktails, as well as non-alcoholic and low-ABV options to cater to health-conscious consumers.
Author
H
Hameer Thakur is a Manger Food and Beverages Research with over 8+ years of experience in the Food and Beverages Industry. He possesses extensive expertise in food and beverage market intelligence, consumer behavior analysis, demand forecasting, competitive benchmarking, product innovation assessment, pricing strategy, supply chain evaluation, regulatory compliance analysis, and market trend forecasting across packaged foods and beverage segments. His comprehensive research and data-driven insights enable organizations to make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, respond to evolving consumer preferences, and strengthen their competitive positioning in the global food and beverages market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
