Rainscreen Cladding Market
Rainscreen Cladding Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710908 | Published On : September 16, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Rainscreen Cladding Market Size
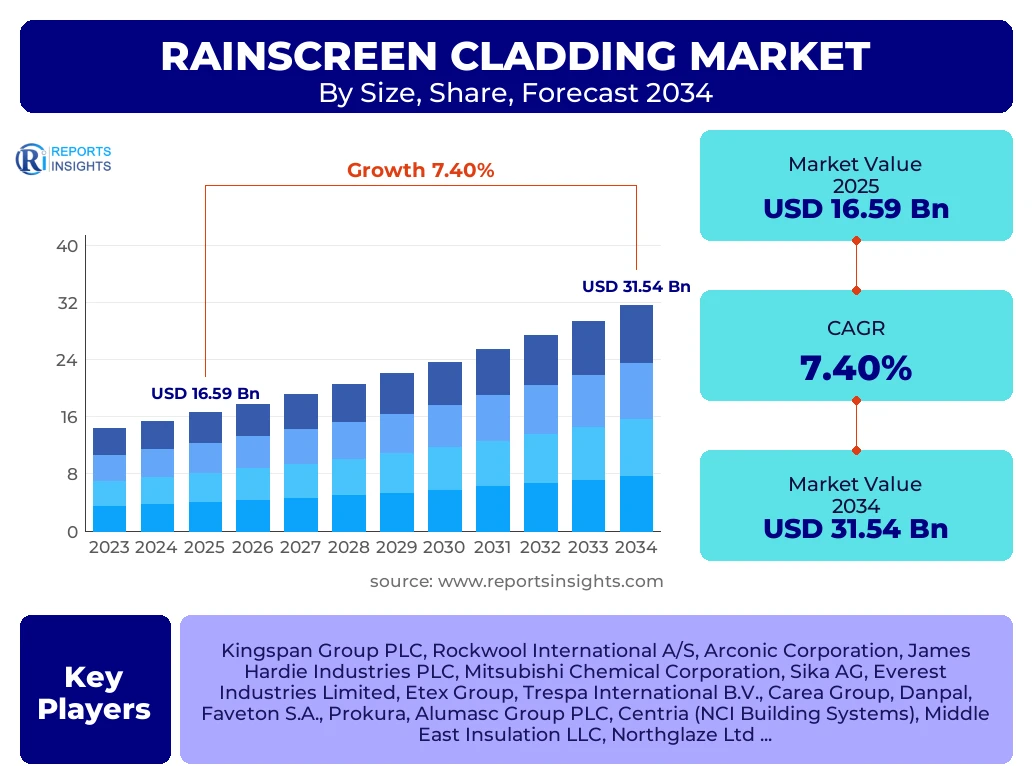
According to Reports Insights Consulting Pvt Ltd, The Rainscreen Cladding Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.4% between 2026 and 2034. The market is estimated at USD 17.82 Billion in 2026 and is projected to reach USD 31.54 Billion by the end of the forecast period in 2034.
Key Rainscreen Cladding Market Trends & Insights
The global rainscreen cladding market is undergoing a significant transformation driven by the escalating demand for energy-efficient building envelopes and the increasing stringency of fire safety regulations across the globe. Modern architectural designs are prioritizing both aesthetic appeal and structural longevity, leading to the adoption of advanced materials such as fiber cement and high-pressure laminates. Market participants are increasingly focusing on the development of pressure-equalized systems that offer superior moisture management compared to traditional back-ventilated systems. Additionally, the rise of green building certifications like LEED and BREEAM is pushing developers toward sustainable cladding solutions that minimize thermal bridging and reduce carbon footprints. The integration of Building Information Modeling (BIM) in the design phase is also facilitating more accurate installation and reducing material waste, further optimizing the value chain for large-scale commercial projects.
- Europe currently stands as the largest regional market due to mature energy efficiency mandates and a high volume of building renovation projects.
- The Asia Pacific region is identified as the fastest-growing market, propelled by rapid urbanization and infrastructure development in emerging economies like India and China.
- In terms of material, the composite materials segment holds the largest market share, valued for its versatility, lightweight nature, and durability.
- Commercial applications represent the largest end-use segment, driven by the construction of high-rise offices and premium retail spaces.
- There is a growing shift toward non-combustible materials, particularly A1 and A2 rated metal and ceramic panels, following updated global building safety codes.
Key Takeaways Rainscreen Cladding Market Size & Forecast
The Rainscreen Cladding market is poised for robust expansion, supported by a global shift toward sustainable and resilient infrastructure. Analysis of user inquiries suggests a high level of interest in the cost-benefit ratio of different cladding materials and the impact of climate-specific variations on system performance. Stakeholders are particularly focused on the long-term maintenance costs and the thermal performance of rainscreen systems in varying humidity levels. The forecast period indicates that while new construction remains a primary driver, the refurbishment sector will provide substantial growth opportunities as older buildings are retrofitted to meet modern environmental standards. Investment in research and development for bio-based cladding materials and smart facade technologies is expected to redefine competitive benchmarking in the coming decade.
- The United Kingdom and Germany are leading the European market through intensive retrofitting programs aimed at improving the thermal performance of residential high-rises.
- Technological advancements in manufacturing have significantly reduced the lead times for custom-designed rainscreen panels.
- A significant portion of the market growth is attributed to the rising adoption of "ventilated facades" in regions with high precipitation to prevent mold and structural rot.
- The market is seeing a trend toward vertical integration, where manufacturers offer end-to-end solutions from design and simulation to final installation.
- Regulatory compliance regarding fire resistance remains the single most influential factor affecting material selection and market entry for new manufacturers.
Rainscreen Cladding Market Drivers Analysis
The primary driver for the rainscreen cladding market is the global movement toward energy-efficient building solutions. As governments implement stricter carbon emission targets, the role of the building envelope in maintaining interior climate control has become paramount. Rainscreen systems provide an effective thermal break, reducing the energy required for heating and cooling. Furthermore, the aesthetic versatility of these systems allows architects to achieve complex designs without compromising structural integrity. The rising urbanization in the APAC region and the subsequent need for high-density housing also provide a steady stream of demand for durable cladding solutions that can withstand environmental stressors.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Energy Efficiency Regulations | +2.1% | European Union, North America | 2025–2034 |
| Rapid Urbanization and Infrastructure Projects | +1.8% | China, India, Southeast Asia | 2025–2030 |
| Increasing Demand for Fire-Resistant Materials | +1.5% | Global | 2025–2034 |
| Rise in Building Refurbishment & Retrofitting | +1.2% | United Kingdom, France, Germany | 2026–2034 |
Rainscreen Cladding Market Restraints Analysis
Despite strong growth prospects, the market faces significant restraints, most notably the high initial cost of materials and installation compared to traditional cladding methods. The complexity of rainscreen systems requires specialized labor, and a shortage of skilled installers in certain regions can lead to project delays and increased costs. Additionally, the fragmented nature of international building codes creates hurdles for manufacturers looking to standardize products across different jurisdictions. Price volatility in raw materials like aluminum and copper also impacts the profit margins of manufacturers and can lead to fluctuating project quotes for end-users.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capital Investment | -0.9% | Global | 2025–2034 |
| Shortage of Skilled Installation Labor | -0.7% | North America, Europe | 2025–2028 |
| Raw Material Price Fluctuations | -0.5% | Global | Ongoing |
Rainscreen Cladding Market Opportunities Analysis
The transition toward "Smart Cities" presents a massive opportunity for the integration of smart facade technologies within rainscreen systems. Future cladding panels could incorporate photovoltaic cells to generate solar energy or sensors to monitor structural health and environmental conditions. There is also a burgeoning market for recycled and bio-composites as developers seek to lower the embodied carbon of their projects. Furthermore, the expansion of the e-commerce and logistics sector is driving the construction of large-scale, climate-controlled warehouses that require robust and efficient cladding solutions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of Building Integrated Photovoltaics (BIPV) | +1.4% | Japan, Germany, USA | 2027–2034 |
| Development of Eco-friendly & Recycled Panels | +1.1% | Scandinavia, North America | 2026–2034 |
| Expansion in Industrial and Logistics Construction | +0.8% | India, Brazil, GCC Countries | 2025–2030 |
Rainscreen Cladding Market Challenges Impact Analysis
Meeting the evolving safety standards remains a core challenge for the industry. Following high-profile incidents involving facade fires, testing and certification requirements have become incredibly rigorous, requiring significant R&D investment. Moreover, the environmental impact of manufacturing certain composite materials is under scrutiny, forcing companies to innovate their production processes. The technical challenge of ensuring moisture-tight performance while maintaining airflow in extreme weather conditions also necessitates continuous engineering improvements.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Compliance with Fire Safety Standards | -0.6% | Global | Ongoing |
| Logistical Complexities in Global Supply Chains | -0.4% | Global | 2025–2027 |
Rainscreen Cladding Market - Updated Report Scope
This report provides a comprehensive analysis of the global Rainscreen Cladding market, covering technological advancements, material innovations, and regional regulatory landscapes. It explores the competitive dynamics and provides strategic recommendations for stakeholders navigating the transition toward sustainable building envelopes. The scope includes a detailed breakdown of market drivers, restraints, and opportunities across various segments and geographies through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 16.59 Billion |
| Market Forecast in 2034 | USD 31.54 Billion |
| Growth Rate | 7.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Kingspan Group PLC, Rockwool International A/S, Arconic Corporation, James Hardie Industries PLC, Mitsubishi Chemical Corporation, Sika AG, Everest Industries Limited, Etex Group, Trespa International B.V., Carea Group, Danpal, Faveton S.A., Prokura, Alumasc Group PLC, Centria (NCI Building Systems), Middle East Insulation LLC, Northglaze Ltd, and Euro Panels. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented primarily by material, which dictates the performance, aesthetics, and cost of the cladding system. Composite materials and metals remain dominant due to their durability and ease of maintenance. Fiber cement is gaining rapid traction as a cost-effective and fire-resistant alternative. System-wise, the back-ventilated approach is widely used for residential buildings, while pressure-equalized systems are preferred for high-rise commercial structures where wind pressure management is critical. The application segment is led by commercial construction, though the institutional sector, specifically healthcare and education, is showing increased interest in rainscreen solutions for better occupant comfort.
- By Material: This includes high-performance composites, lightweight metals, natural terracotta, durable ceramics, and cost-effective fiber cement options.
- By System Type: Back-ventilated systems focus on air circulation to dry moisture, whereas pressure-equalized systems manage air pressure to prevent water ingress.
- By End-Use Sector: Broadly categorized into residential housing, commercial complexes, institutional buildings (hospitals, universities), and specialized industrial facilities.
- By Construction Activity: Segregated into new builds and the rapidly growing refurbishment and renovation market.
Regional Highlights
- Europe: The largest market share holder, driven by the Energy Performance of Buildings Directive (EPBD) and extensive renovation of historic and aging residential blocks. Germany and the UK are primary hubs.
- Asia Pacific: The fastest-growing region with a high CAGR, fueled by massive urbanization in China, India, and Vietnam. The demand for modern, high-rise office spaces is a key factor.
- North America: A steady market focused on premium commercial aesthetics and strict compliance with the International Building Code (IBC). The US leads in the adoption of composite and HPL panels.
- Middle East & Africa: Growth is concentrated in the GCC countries, where rainscreen systems are used to manage extreme heat through advanced thermal insulation and ventilated facades.
- Latin America: Emerging opportunities in Brazil and Mexico as industrial construction and luxury residential projects adopt modern facade technologies.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Rainscreen Cladding Market.- Kingspan Group PLC
- Rockwool International A/S
- Arconic Corporation
- James Hardie Industries PLC
- Mitsubishi Chemical Corporation
- Sika AG
- Everest Industries Limited
- Etex Group
- Trespa International B.V.
- Carea Group
- Danpal
- Faveton S.A.
- Prokura
- Alumasc Group PLC
- Centria (NCI Building Systems)
- Middle East Insulation LLC
- Northglaze Ltd
- Euro Panels
Frequently Asked Questions
What is the main advantage of using a rainscreen cladding system?
The primary advantage is superior moisture management. By creating a ventilated cavity between the cladding and the building wall, moisture is evaporated or drained away, preventing structural rot and mold while enhancing thermal insulation and energy efficiency.
Which material is currently dominating the Rainscreen Cladding market?
Composite materials currently dominate the market due to their excellent strength-to-weight ratio, design flexibility, and durability. However, fiber cement is the fastest-growing sub-segment due to its inherent fire resistance and cost-effectiveness.
How do fire safety regulations affect the market?
Fire safety regulations are a major market driver and restraint. Strict codes (like A1/A2 ratings) force manufacturers to move away from combustible cores in panels, driving innovation in non-combustible materials but also increasing R&D and certification costs.
Which region offers the highest growth potential for investors?
Asia Pacific offers the highest growth potential due to rapid infrastructure development and urbanization. However, Europe remains a stable and large market due to the high volume of mandatory energy-efficient retrofitting projects.
What is the difference between back-ventilated and pressure-equalized systems?
Back-ventilated systems rely on an air cavity to dry out moisture through convection. Pressure-equalized systems use compartments to equalize external wind pressure with internal cavity pressure, preventing water from being "sucked" into the building structure, making them ideal for high-rise buildings.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted