PVC Pipes Market
PVC Pipes Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711660 | Published On : November 11, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
PVC Pipes Market Size
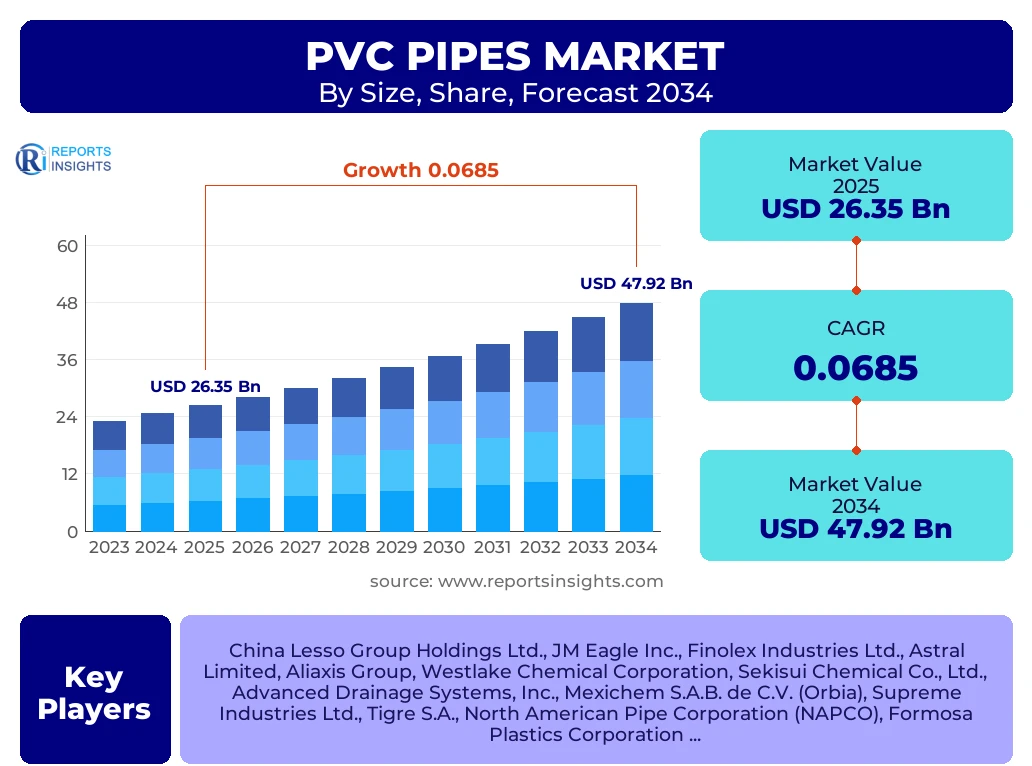
According to Reports Insights Consulting Pvt Ltd, The PVC Pipes Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.85% between 2025 and 2034. The market is estimated at USD 28.15 Billion in 2026 and is projected to reach USD 47.92 Billion by the end of the forecast period in 2034.
Key PVC Pipes Market Trends & Insights
The global PVC Pipes market is currently undergoing a significant transformation driven by the integration of advanced polymer stabilization techniques and a pivot toward sustainable manufacturing processes. Industry stakeholders are increasingly focusing on the replacement of aging metallic infrastructure with high-performance plastic piping systems due to their superior corrosion resistance and longevity. Regional insights suggest that while mature economies in North America and Europe are concentrating on trenchless technology for urban pipe replacement, the Asia-Pacific region remains the primary engine for volume growth, fueled by massive irrigation projects and residential construction. Competitive benchmarking reveals that leading manufacturers are diversifying their portfolios to include Chlorinated Polyvinyl Chloride (CPVC) and Molecularly Oriented PVC (PVC-O) to cater to high-pressure and high-temperature industrial applications.
- Largest Region: Asia-Pacific, holding a dominant market share of over 45% due to extensive agricultural and infrastructural development in China and India.
- Fastest Growing Region: Southeast Asia and parts of Africa are exhibiting the highest growth rates, driven by rapid urbanization and investments in water sanitation.
- Largest Segment by Type: Unplasticized PVC (uPVC) continues to be the largest segment owing to its widespread use in drinking water distribution and drainage.
- Leading Application: Agriculture and Irrigation represent the primary demand drivers, particularly in emerging economies where efficient water management is critical.
- Technological Shift: The adoption of lead-free stabilizers and recycled PVC content is becoming a standard to comply with tightening environmental regulations.
Key Takeaways PVC Pipes Market Size & Forecast
The market trajectory for PVC Pipes remains robust, with a clear shift from basic utility applications to specialized industrial and municipal infrastructure roles. Analysis of global demand indicates that the market is not merely expanding in volume but also in value, as higher-grade variants like PVC-O gain traction for their enhanced hydraulic capacity and impact resistance. Stakeholders are closely monitoring the volatility of feedstock prices, particularly ethylene and chlorine, which directly influence the cost structure of the end product. Forecasts suggest that the integration of smart piping technologies, featuring sensors for leak detection and flow monitoring, will redefine the competitive landscape by 2034, offering integrated solutions rather than just hardware.
- Infrastructure Modernization: The replacement of legacy lead and iron pipes in municipal networks across the United States and Western Europe is a multi-billion dollar long-term driver.
- Agricultural Dominance: India remains the most significant single-country market for agricultural PVC Pipes, supported by government initiatives for micro-irrigation.
- Material Innovation: CPVC is witnessing accelerated adoption in the residential sector for hot and cold water plumbing systems, displacing traditional copper and galvanized steel.
- Sustainability Focus: The circular economy is influencing the market, with an increasing number of manufacturers investing in closed-loop recycling systems for construction waste.
- Market Consolidation: Strategic mergers and acquisitions are expected to increase as larger players seek to expand their geographic footprint and acquire specialized manufacturing capabilities.
PVC Pipes Market Drivers Analysis
The primary driver for the global PVC Pipes market is the escalating global requirement for efficient water management systems. As water scarcity becomes a pressing geopolitical issue, governments are investing heavily in leak-proof, durable piping solutions for both agricultural irrigation and urban water supply. The inherent properties of PVC, such as its lightweight nature, ease of installation, and resistance to chemical and biological erosion, make it the preferred material over traditional alternatives like ductile iron or concrete.
Furthermore, the rapid pace of urbanization in developing nations is creating an unprecedented demand for residential and commercial plumbing. The construction sector relies heavily on PVC for drainage, waste, and vent (DWV) systems. Additionally, the expansion of the telecommunications sector has spurred demand for PVC conduits to protect underground fiber optic cables, providing a secondary but consistent revenue stream for pipe manufacturers.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Urbanization and Construction Boom | +2.1% | Asia-Pacific and Africa | 2025 - 2034 |
| Aging Infrastructure Replacement Programs | +1.5% | North America and Europe | 2026 - 2030 |
| Expansion of Micro-Irrigation Projects | +1.8% | India and Brazil | 2025 - 2034 |
| Advancements in PVC-O and CPVC Technology | +1.2% | Global | 2027 - 2034 |
PVC Pipes Market Restraints Analysis
Despite the positive growth outlook, the market faces significant headwinds from the volatility of raw material prices. PVC production is energy-intensive and dependent on the pricing of crude oil and natural gas, which serve as precursors for ethylene. Frequent fluctuations in the global energy market can lead to unpredictable manufacturing costs, squeezing profit margins for small and medium-sized enterprises. This volatility often forces manufacturers to adjust prices, which can lead to project delays in cost-sensitive sectors like public housing.
Environmental and regulatory scrutiny also serves as a major restraint. The use of certain phthalates and heavy-metal stabilizers, such as lead, in the PVC manufacturing process has come under fire from environmental advocacy groups and health organizations. Strict regulations, particularly in the European Union under the REACH framework, necessitate costly transitions to alternative stabilizers. Additionally, the competition from High-Density Polyethylene (HDPE) pipes, which offer higher flexibility and better performance in certain seismic zones, poses a credible threat to PVC's market share in specific underground applications.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Feedstock Price Volatility (Ethylene/Chlorine) | -1.2% | Global | Ongoing |
| Stringent Environmental Regulations (Lead/Phthalates) | -0.8% | Europe and North America | 2025 - 2028 |
| Competition from HDPE and Alternative Materials | -0.7% | Global | 2025 - 2034 |
PVC Pipes Market Opportunities Analysis
One of the most promising opportunities in the PVC Pipes market lies in the development of "Smart Pipes." By integrating IoT sensors directly into the pipe structure or joints during the manufacturing process, companies can offer systems capable of real-time monitoring for pressure drops, temperature changes, and chemical leaks. This is particularly attractive for municipal water boards and industrial chemical plants looking to reduce non-revenue water (NRW) losses and prevent environmental disasters. The premium associated with smart infrastructure offers a path to higher value-added growth.
Another significant opportunity is the emergence of bio-based PVC. Research into bio-attributed PVC, which uses renewable feedstocks instead of fossil fuels, is gaining momentum. As corporate social responsibility (CSR) and Environmental, Social, and Governance (ESG) criteria become central to procurement policies in the construction industry, bio-based PVC Pipes could capture a premium segment of the market. Furthermore, the expansion of the 5G network globally requires extensive underground conduit systems, offering a lucrative niche for specialized PVC ducting products.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| IoT Integration and Smart Piping Systems | +1.4% | Developed Economies | 2027 - 2034 |
| Development of Bio-based and Recycled PVC | +0.9% | Europe and North America | 2026 - 2034 |
| Expansion of 5G and Telecommunication Conduits | +1.1% | Global (APAC focus) | 2025 - 2030 |
PVC Pipes Market Challenges Impact Analysis
The primary challenge for the industry is the logistical complexity and cost associated with transporting large-diameter pipes. Because pipes are hollow and occupy significant volume relative to their weight, shipping costs can be disproportionately high, often limiting the effective service radius of a manufacturing facility. This leads to a highly fragmented market where regional players dominate, and global companies must invest heavily in local manufacturing hubs to remain competitive. Maintaining consistent quality standards across decentralized production sites remains a significant operational hurdle.
Additionally, the industry must contend with a negative public perception regarding plastic waste. Despite PVC being one of the most recyclable plastics, the infrastructure for collecting and processing used pipes is still in its infancy in many regions. Mismanagement of PVC waste and its perceived non-biodegradability can lead to legislative bans or shifts toward more expensive traditional materials in public projects. Overcoming this through industry-wide recycling initiatives and transparent sustainability reporting is a critical challenge for the coming decade.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Logistical and Transportation Costs | -1.0% | Geographically Large Nations (USA, China, Russia) | Ongoing |
| Public Perception and Plastic Waste Management | -0.6% | Global | 2025 - 2034 |
| Fragmentation of Local Markets | -0.4% | Emerging Markets | 2025 - 2034 |
PVC Pipes Market - Updated Report Scope
This report provides a granular analysis of the global PVC Pipes industry, encompassing the entire value chain from raw material procurement to end-use applications. It evaluates the impact of macroeconomic trends, technological shifts, and regulatory changes on market dynamics. The scope includes a detailed breakdown of different PVC resin types and their specific performance characteristics in diverse environments. Furthermore, the report offers a competitive landscape analysis, identifying key strategic moves by market leaders, including capacity expansions, product innovations, and geographic diversifications. The forecast period (2026-2034) provides a strategic roadmap for stakeholders to navigate the evolving market landscape.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 26.35 Billion |
| Market Forecast in 2034 | USD 47.92 Billion |
| Growth Rate | 6.85% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | China Lesso Group Holdings Ltd., JM Eagle Inc., Finolex Industries Ltd., Astral Limited, Aliaxis Group, Westlake Chemical Corporation, Sekisui Chemical Co., Ltd., Advanced Drainage Systems, Inc., Mexichem S.A.B. de C.V. (Orbia), Supreme Industries Ltd., Tigre S.A., North American Pipe Corporation (NAPCO), Formosa Plastics Corporation, National Pipe and Plastics, Inc., Pipelife International GmbH. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The PVC Pipes market is segmented based on chemical composition, physical properties, and specific industrial requirements. This detailed segmentation allows for a precise understanding of which product types are driving growth in specific regional markets. For instance, while uPVC remains the standard for general drainage and low-pressure water transport, the rise of specialized CPVC has revolutionized the indoor plumbing sector by providing a cost-effective alternative to metallic pipes for hot water distribution. Understanding these nuances is vital for manufacturers looking to optimize their production lines based on regional demand signals.
- By Type:
- Unplasticized PVC (uPVC): Rigid and resistant to chemicals; primarily used for water mains, soil and waste pipes.
- Chlorinated PVC (CPVC): Enhanced heat resistance; ideal for hot and cold water distribution and industrial liquid handling.
- Molecularly Oriented PVC (PVC-O): Created through a restructuring process that enhances strength and flexibility; used for high-pressure applications.
- Plasticized PVC: More flexible; used in specialized medical and industrial hose applications.
- By Application:
- Irrigation: Largest consumer by volume, particularly in agricultural-driven economies.
- Sewerage and Drainage: Essential for urban sanitation and wastewater management.
- Water Supply: Includes both municipal mainlines and residential connections.
- Electrical Conduits: Protecting cables in construction and utility projects.
- Industrial/Chemical: Handling corrosive substances in manufacturing environments.
Regional Highlights
- Asia-Pacific (APAC): The largest and most dynamic region. China and India lead the market due to massive investments in the "Jal Jeevan Mission" (India) and large-scale urbanization in China. The region accounts for over 45% of global demand.
- North America: A mature market characterized by the replacement of aging infrastructure. The U.S. Infrastructure Investment and Jobs Act is a major catalyst for the renewal of municipal water and sewer lines.
- Europe: Focused heavily on sustainability and the transition to lead-free stabilizers. Germany and France are leading in the adoption of advanced recycling technologies for construction plastics.
- Latin America: Growing demand driven by agricultural exports from Brazil and Argentina, which require extensive irrigation networks.
- Middle East and Africa: Significant growth in the GCC countries due to desalination projects and the construction of new mega-cities (e.g., NEOM), while Africa presents long-term opportunities in basic water sanitation.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the PVC Pipes Market.- China Lesso Group Holdings Ltd.
- JM Eagle Inc.
- Finolex Industries Ltd.
- Astral Limited
- Aliaxis Group
- Westlake Chemical Corporation
- Sekisui Chemical Co., Ltd.
- Advanced Drainage Systems, Inc.
- Mexichem S.A.B. de C.V. (Orbia)
- Supreme Industries Ltd.
- Tigre S.A.
- North American Pipe Corporation (NAPCO)
- Formosa Plastics Corporation
- National Pipe and Plastics, Inc.
- Pipelife International GmbH
- Prince Pipes and Fittings Ltd.
- Georg Fischer Ltd.
- Ductile Iron Pipe Research Association
- IPEX Inc.
- Plastics Pipe Institute
Frequently Asked Questions
What is the primary factor driving the growth of the PVC Pipes market?
The primary factor is the increasing global investment in water infrastructure and irrigation systems, coupled with the rapid urbanization in emerging economies that requires durable, cost-effective plumbing and sewerage solutions.
How does CPVC differ from standard uPVC in terms of market application?
CPVC (Chlorinated Polyvinyl Chloride) can withstand higher temperatures and pressures compared to standard uPVC, making it the preferred choice for hot water plumbing and industrial chemical processing where uPVC might fail.
Which region currently dominates the global PVC Pipes market share?
Asia-Pacific is the dominant region, holding over 45% of the market share. This is attributed to the massive agricultural sectors in India and China, alongside extensive government-led infrastructure development projects.
Are there environmental concerns regarding the use of PVC Pipes?
Yes, concerns primarily relate to the use of heavy-metal stabilizers like lead and the production of dioxins. However, the industry is rapidly shifting toward lead-free stabilizers and enhanced recycling programs to mitigate these environmental impacts.
What is the expected CAGR for the PVC Pipes market through 2034?
The market is expected to grow at a steady CAGR of approximately 6.85% from 2025 to 2034, driven by technological advancements and the ongoing global shift from metal to plastic piping.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
