Pta Balloon Catheter Market
Pta Balloon Catheter Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710973 | Published On : September 24, 2026 |
Format : 


 | Author : Erika Grotto
Pta Balloon Catheter Market Size
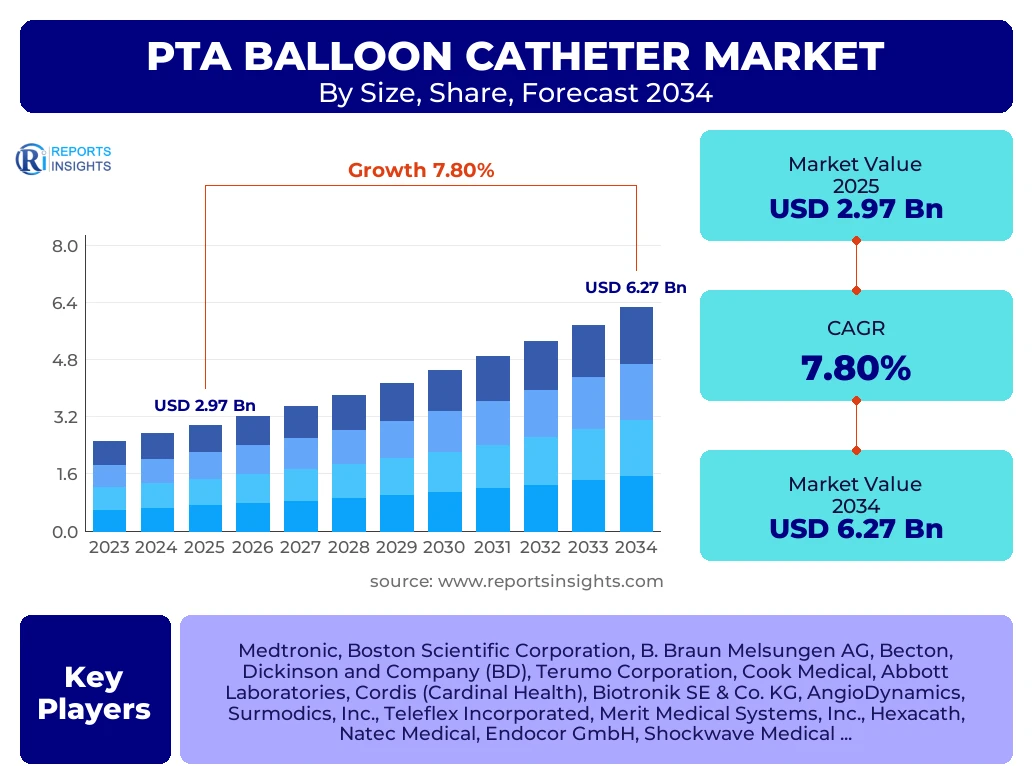
According to Reports Insights Consulting Pvt Ltd, The Pta Balloon Catheter Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.8% between 2026 and 2034. The market is estimated at USD 3.20 Billion in 2026 and is projected to reach USD 6.27 Billion by the end of the forecast period in 2034.
Key Pta Balloon Catheter Market Trends & Insights
The global market for Percutaneous Transluminal Angioplasty (PTA) balloon catheters is experiencing a significant transformation driven by the rising prevalence of peripheral artery disease (PAD) and the transition toward minimally invasive endovascular procedures. Current trends indicate a strong shift toward specialty balloons, particularly drug-coated balloons (DCBs) and scoring/cutting balloons, which offer superior clinical outcomes by reducing restenosis rates compared to standard PTA catheters. Furthermore, advancements in material science have led to the development of ultra-high-pressure balloons and lower-profile delivery systems that allow clinicians to treat complex, highly calcified lesions in smaller distal vessels with greater precision and safety.
- Largest Region: North America remains the largest market due to its advanced healthcare infrastructure, high healthcare expenditure, and the high prevalence of obesity and diabetes-related vascular complications.
- Fastest Growing Region: Asia-Pacific is anticipated to be the fastest-growing region, fueled by expanding healthcare access in China and India, a rapidly aging population, and increasing medical tourism for cardiovascular interventions.
- Largest Segment: The Drug-Coated Balloon (DCB) segment currently holds the largest market share in terms of value, as these devices command premium pricing due to their efficacy in preventing neo-intimal hyperplasia.
- Key Trend: Growing adoption of PTA balloon catheters in Ambulatory Surgical Centers (ASCs) and outpatient settings to reduce procedural costs and recovery times.
Key Takeaways Pta Balloon Catheter Market Size & Forecast
The PTA balloon catheter market is poised for robust growth as clinical data continues to favor endovascular intervention over traditional open bypass surgeries for many peripheral vascular conditions. Stakeholders are increasingly focusing on vertical integration and strategic partnerships to navigate stringent regulatory landscapes and capture emerging market opportunities. The forecast suggests that technological convergence between imaging modalities and catheter delivery systems will be a primary differentiator for market leaders in the coming decade.
- Leading Country: The United States leads the global market, accounting for a substantial portion of revenue generated through high-volume peripheral interventions and favorable reimbursement policies for angioplasty.
- Market Maturity: While standard PTA balloons are reaching a stage of market maturity in developed nations, specialty balloons are in a high-growth phase.
- CAGR Driver: The increasing incidence of critical limb ischemia (CLI) is a primary driver, necessitating the use of high-performance balloon catheters to prevent limb amputation.
- Regulatory Impact: Harmonization of regulatory standards across the EU and North America is expected to streamline product launches and enhance global supply chain efficiency.
Pta Balloon Catheter Market Drivers Analysis
The growth of the PTA balloon catheter market is primarily underpinned by the escalating global burden of chronic lifestyle diseases such as diabetes and hypertension, which are major precursors to peripheral vascular disorders. As the global population ages, the incidence of arterial stiffness and calcification increases, driving the demand for advanced interventional tools. Additionally, the shift in patient preference toward minimally invasive surgeries, which offer shorter hospital stays and lower complication rates, is compelling healthcare providers to invest heavily in endovascular technology.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rise in Peripheral Artery Disease (PAD) Prevalence | +2.5% | Global / High in US and EU | 2025–2034 |
| Advancements in Drug-Coated Balloon Technology | +2.1% | North America and Germany | 2025–2030 |
| Expansion of Ambulatory Surgical Centers (ASCs) | +1.8% | United States and China | 2026–2034 |
Pta Balloon Catheter Market Restraints Analysis
Despite strong growth drivers, the market faces significant hurdles, including the high cost associated with specialty PTA catheters like drug-coated and scoring balloons, which limits their accessibility in low-to-middle-income countries. Furthermore, stringent regulatory approval processes, such as the EU Medical Device Regulation (MDR), have increased the time and cost required for product commercialization. Potential clinical risks, including vessel dissection or distal embolization during balloon inflation, also remain a concern that necessitates highly skilled interventionalists.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Approval Pathways | -1.2% | European Union (MDR) | 2025–2028 |
| High Cost of Advanced Specialty Balloons | -0.9% | India, Brazil, and SE Asia | 2025–2034 |
Pta Balloon Catheter Market Opportunities Analysis
Significant opportunities exist in the development of bioresorbable coating technologies and the integration of artificial intelligence in pre-procedural planning. Emerging markets in the Asia-Pacific and Latin American regions offer untapped potential due to improving healthcare infrastructure and a growing middle class with better access to insurance. Moreover, the trend toward value-based healthcare encourages the development of cost-effective PTA solutions that provide long-term clinical durability, opening doors for innovative tier-two manufacturers to gain market share.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Emerging Market Healthcare Infrastructure Growth | +2.3% | China, India, and GCC Countries | 2027–2034 |
| Development of Bioresorbable PTA Platforms | +1.5% | Japan and Western Europe | 2028–2034 |
Pta Balloon Catheter Market Challenges Impact Analysis
The primary challenge for the PTA balloon catheter market lies in the intense competitive landscape and the presence of alternative treatment modalities, such as stenting and atherectomy, which may be preferred in certain clinical scenarios. Manufacturers must also contend with price erosion caused by group purchasing organizations (GPOs) and hospital procurement policies that prioritize bulk discounts over technical innovation. Additionally, the volatility in raw material costs and disruptions in the global medical supply chain continue to pose operational risks for manufacturers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Intense Competition and Price Erosion | -1.4% | Global / High in US | 2025–2034 |
| Supply Chain and Raw Material Volatility | -0.7% | Global | 2025–2027 |
Pta Balloon Catheter Market - Updated Report Scope
This report provides a granular analysis of the global PTA balloon catheter market, covering technological advancements, competitive dynamics, and regional growth patterns. The scope encompasses various balloon types used in the treatment of peripheral arterial disease across different healthcare settings. It provides quantitative and qualitative insights designed to assist stakeholders in making informed investment and strategic decisions through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.97 Billion |
| Market Forecast in 2034 | USD 6.27 Billion |
| Growth Rate | 7.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Medtronic, Boston Scientific Corporation, B. Braun Melsungen AG, Becton, Dickinson and Company (BD), Terumo Corporation, Cook Medical, Abbott Laboratories, Cordis (Cardinal Health), Biotronik SE & Co. KG, AngioDynamics, Surmodics, Inc., Teleflex Incorporated, Merit Medical Systems, Inc., Hexacath, Natec Medical, Endocor GmbH, Shockwave Medical, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The PTA balloon catheter market is segmented based on product type, material, and end-user, reflecting the diverse clinical needs of vascular interventions. The product segmentation highlights the transition from traditional mechanical dilation to therapeutic delivery systems. Material segmentation focuses on the balance between catheter flexibility and burst pressure resistance, which is critical for traversing tortuous anatomy and treating calcified lesions.
- By Product Type:
- Standard PTA Balloons: These remain the workhorse of the industry for simple stenotic lesions due to their cost-effectiveness.
- Drug-Coated Balloons (DCB): The highest-value segment, primarily using paclitaxel or sirolimus to prevent restenosis.
- Specialty Balloons (Scoring/Cutting): Used for complex, fibrotic, or calcified lesions where standard balloons may fail or cause vessel trauma.
- High-Pressure Balloons: Specifically designed for resistant or non-compliant lesions requiring significant force.
- By Material:
- Nylon: Preferred for its high-pressure resistance and durability in semi-compliant and non-compliant balloons.
- Polyurethane: Utilized for its superior trackability and flexibility in lower-profile catheters.
- By End-User:
- Hospitals: The primary setting for complex interventional procedures involving high-risk patients.
- Ambulatory Surgical Centers (ASCs): A rapidly growing segment due to the cost-effectiveness and efficiency of outpatient vascular care.
- Specialty Clinics: Often focused on specific pathologies like venous insufficiency or dialysis access maintenance.
Regional Highlights
- North America: The largest market share holder, North America is characterized by high adoption rates of premium devices like DCBs and a well-established reimbursement framework (CPT codes) for peripheral interventions.
- Europe: A mature market with a strong emphasis on clinical evidence and cost-effectiveness. Germany and France are key contributors to the regional market growth.
- Asia-Pacific: Expected to witness the highest CAGR. Factors such as the massive diabetic population in India and China, increasing healthcare spending, and localization of manufacturing are driving growth.
- Latin America: Growth is driven by Brazil and Mexico, where efforts to modernize healthcare infrastructure are expanding access to endovascular therapies.
- Middle East and Africa: A developing market where growth is concentrated in the GCC countries, driven by high rates of metabolic disorders requiring vascular intervention.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Pta Balloon Catheter Market.- Medtronic plc
- Boston Scientific Corporation
- Becton, Dickinson and Company (BD)
- Abbott Laboratories
- Terumo Corporation
- Cook Medical
- B. Braun Melsungen AG
- Cordis (a Cardinal Health company)
- Biotronik SE & Co. KG
- AngioDynamics
- Surmodics, Inc.
- Teleflex Incorporated
- Merit Medical Systems, Inc.
- Hexacath
- Natec Medical
- Endocor GmbH
- Shockwave Medical, Inc.
- Acrostak
- Cardionovum GmbH
- Philips (Spectranetics)
Frequently Asked Questions
What is driving the growth of the Drug-Coated Balloon (DCB) segment?
The DCB segment is growing due to its ability to deliver anti-proliferative drugs directly to the vessel wall, significantly reducing the rates of restenosis and the need for repeat interventions compared to standard balloons.
Which region is expected to lead the PTA balloon catheter market by 2034?
North America is expected to maintain the leading position in terms of market value, although the Asia-Pacific region will likely see the fastest percentage growth during the forecast period.
How do scoring balloons differ from standard PTA balloons?
Scoring balloons feature longitudinal elements (wires or blades) on the balloon surface that focus the force of inflation to "score" or crack calcified plaque, allowing for vessel expansion at lower pressures with less trauma.
What impact does the move to Ambulatory Surgical Centers have on this market?
The shift to ASCs increases the volume of procedures by offering lower-cost alternatives to hospital stays, encouraging the development of user-friendly, high-efficiency PTA catheter systems tailored for outpatient settings.
What are the primary regulatory challenges for new market entrants?
New entrants must navigate complex clinical trial requirements and rigorous quality management standards, such as the EU MDR and US FDA 510(k) or PMA pathways, which require significant capital and time.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted