Prostate Cancer Nuclear Medicine Diagnostics Market
Prostate Cancer Nuclear Medicine Diagnostics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711172 | Published On : October 14, 2026 |
Format : 


 | Author : Erika Grotto
Prostate Cancer Nuclear Medicine Diagnostics Market Size
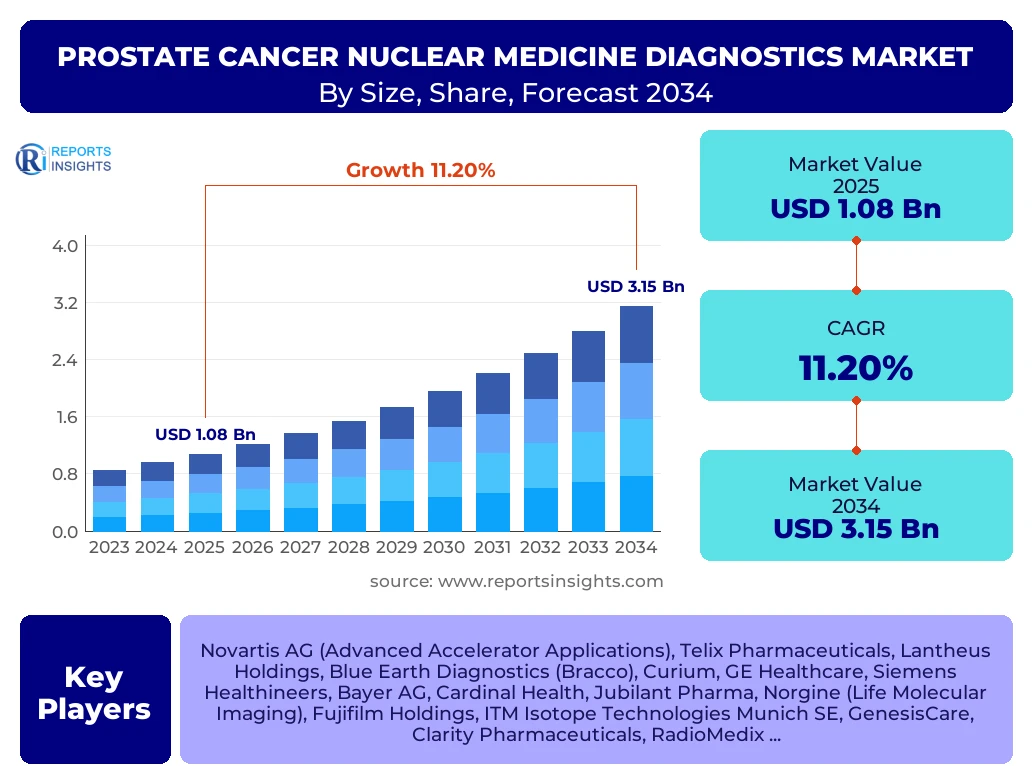
According to Reports Insights Consulting Pvt Ltd, The Prostate Cancer Nuclear Medicine Diagnostics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 11.2% between 2025 and 2034. The market is estimated at USD 1.2 Billion in 2026 and is projected to reach USD 3.15 Billion by the end of the forecast period in 2034.
Key Prostate Cancer Nuclear Medicine Diagnostics Market Trends & Insights
The global landscape for prostate cancer nuclear medicine is undergoing a seismic shift driven by the rapid clinical adoption of Prostate-Specific Membrane Antigen (PSMA) targeted imaging. Stakeholders are increasingly focusing on the integration of Positron Emission Tomography (PET) with Computed Tomography (CT) and Magnetic Resonance Imaging (MRI) to enhance diagnostic precision. Insights indicate a significant migration from traditional bone scans toward more sensitive radiopharmaceuticals like Gallium-68 (Ga-68) and Fluorine-18 (F-18) labeled agents. The market is also seeing a trend toward theranostics, where diagnostic imaging directly informs the subsequent radioligand therapy, creating a seamless continuum of care for metastatic castration-resistant prostate cancer (mCRPC) patients. Competitive benchmarking reveals that leading companies are investing heavily in localized isotope production and supply chain resilience to mitigate the short half-life limitations of diagnostic tracers.
- Largest Region: North America currently holds the largest market share due to high healthcare expenditure and the early FDA approval of advanced PSMA tracers.
- Fastest Growing Region: Asia Pacific is anticipated to exhibit the highest CAGR, fueled by improving diagnostic infrastructure in China and India and an aging male population.
- Largest Segment: The PET Imaging segment dominates the market share compared to SPECT, attributed to its superior sensitivity and resolution in detecting small lesions.
- Leading Radiopharmaceutical: F-18 labeled agents are gaining rapid traction over Ga-68 due to their longer half-life and easier centralized distribution model.
Key Takeaways Prostate Cancer Nuclear Medicine Diagnostics Market Size & Forecast
Analyzing the long-term forecast, the market's trajectory is primarily dictated by the increasing incidence of prostate cancer globally and the shift toward personalized oncology. Users and investors are particularly concerned with the cost-benefit ratio of nuclear medicine versus traditional biopsy or MRI alone. The consensus among medical experts is that nuclear medicine provides a more comprehensive "whole-body" view of the disease, which is essential for accurate staging and detecting biochemical recurrence. The forecast period 2025–2034 will likely see a standardization of imaging protocols, making these high-end diagnostics accessible beyond specialized academic medical centers into community-based oncology practices.
- Global Prevalence: Prostate cancer remains one of the most diagnosed malignancies in men, ensuring a steady and growing patient pool for diagnostic services.
- Regulatory Tailwinds: Increasing approvals for novel PSMA-targeting agents by the FDA and EMA are major catalysts for market expansion.
- Technological Synergy: The rise of Digital PET/CT scanners is significantly reducing scan times and improving patient throughput for diagnostic centers.
- Reimbursement Stability: Expanded Medicare and private insurance coverage for PSMA PET scans in the United States is a critical driver for volume growth.
- Supply Chain Innovation: The transition toward cyclotron-produced isotopes is reducing the reliance on aging nuclear reactors for isotope supply.
Prostate Cancer Nuclear Medicine Diagnostics Market Drivers Analysis
The primary drivers for the prostate cancer nuclear medicine diagnostics market involve the convergence of demographic shifts and technological breakthroughs in radiochemistry. As the global population ages, the clinical burden of prostate cancer rises, necessitating more sophisticated diagnostic tools that can differentiate between indolent and aggressive disease. Furthermore, the clinical success of radioligand therapies has created a "pull effect," where the need to identify eligible patients for therapy drives the volume of diagnostic nuclear imaging. The precision of PSMA-PET imaging in identifying lymph node involvement and distant metastasis at low PSA levels has set a new gold standard in urological oncology.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Adoption of PSMA-Targeted Tracers | +4.5% | Global (Strongest in US & EU) | 2025 - 2034 |
| Expansion of Theranostics Infrastructure | +3.2% | North America & Western Europe | 2026 - 2032 |
| Rising Geriatric Population and Cancer Incidence | +2.1% | Japan, China, Germany | 2025 - 2034 |
| Technological Advancements in PET/CT Hardware | +1.4% | Global | 2025 - 2030 |
Prostate Cancer Nuclear Medicine Diagnostics Market Restraints Analysis
Despite robust growth, the market faces significant restraints related to the high cost of imaging equipment and the logistical complexities of handling short-lived radioactive isotopes. The initial capital investment for a PET/CT suite can exceed several million dollars, which remains a barrier for smaller hospitals and developing nations. Additionally, the stringent regulatory environment governing nuclear materials and the limited number of trained nuclear medicine physicians and technicians pose operational challenges to market scaling.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of PET/CT Procedures & Equipment | -2.5% | Emerging Markets (LAMEA/APAC) | 2025 - 2034 |
| Logistical Challenges of Isotope Decay | -1.8% | Remote Regions/Developing Nations | 2025 - 2030 |
| Shortage of Skilled Nuclear Medicine Professionals | -1.2% | Global | 2026 - 2034 |
Prostate Cancer Nuclear Medicine Diagnostics Market Opportunities Analysis
The market is ripe with opportunities, particularly in the development of Copper-64 (Cu-64) based tracers, which offer longer half-lives and potentially better imaging windows compared to Ga-68. There is also a massive untapped opportunity in the integration of Artificial Intelligence (AI) for automated lesion detection and quantitative analysis, which can standardize reporting across different centers. Furthermore, the expansion of healthcare infrastructure in emerging economies like Brazil, India, and Southeast Asia provides a fertile ground for market players to establish new diagnostic networks.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Long-lived Isotopes (e.g., Cu-64) | +3.8% | Global | 2027 - 2034 |
| AI-Driven Diagnostic Software Integration | +2.5% | North America, South Korea | 2025 - 2032 |
| Expansion into Emerging Tier-2/3 Cities | +2.2% | India, China, Brazil | 2028 - 2034 |
Prostate Cancer Nuclear Medicine Diagnostics Market Challenges Impact Analysis
Supply chain volatility remains the most critical challenge, specifically the reliance on a limited number of aging nuclear reactors for the production of parent isotopes. Any unscheduled reactor maintenance can cause global shortages of diagnostic materials. Additionally, competition from alternative diagnostic modalities, such as multi-parametric MRI (mpMRI) and emerging liquid biopsy technologies, requires nuclear medicine to continuously demonstrate superior clinical outcomes and cost-effectiveness to maintain its market position.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Isotope Supply Chain Fragility | -2.1% | Global | 2025 - 2034 |
| Competition from mpMRI and Liquid Biopsy | -1.5% | Western Europe, USA | 2026 - 2034 |
| Strict Regulatory & Environmental Compliance | -0.8% | European Union | 2025 - 2030 |
Prostate Cancer Nuclear Medicine Diagnostics Market - Updated Report Scope
This comprehensive report provides a deep-dive analysis into the global prostate cancer nuclear medicine diagnostics sector, covering the technological transition from SPECT to PET imaging and the evolution of PSMA-targeted radiopharmaceuticals. The scope encompasses detailed financial modeling, competitive landscape mapping, and regional regulatory analysis. It serves as a strategic roadmap for healthcare providers, pharmaceutical companies, and investors looking to capitalize on the high-growth theranostics ecosystem.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.08 Billion |
| Market Forecast in 2034 | USD 3.15 Billion |
| Growth Rate | 11.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Novartis AG (Advanced Accelerator Applications), Telix Pharmaceuticals, Lantheus Holdings, Blue Earth Diagnostics (Bracco), Curium, GE Healthcare, Siemens Healthineers, Bayer AG, Cardinal Health, Jubilant Pharma, Norgine (Life Molecular Imaging), Fujifilm Holdings, ITM Isotope Technologies Munich SE, GenesisCare, Clarity Pharmaceuticals, RadioMedix, Positron Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented by technology, radiopharmaceutical type, and clinical application, reflecting the diverse needs of the urological oncology community. PET imaging remains the dominant technology due to its high resolution, while the radiopharmaceutical segment is witnessing a transition toward F-18 based agents due to logistical advantages. Clinical application segments are expanding as nuclear medicine is now utilized not just for staging, but also for monitoring therapy response in patients undergoing novel androgen receptor signaling inhibitors (ARSI) or radioligand therapies.
- By Type:
- Positron Emission Tomography (PET) - Includes PET/CT and PET/MRI
- Single Photon Emission Computed Tomography (SPECT) - Including Bone Scintigraphy
- By Radiopharmaceutical:
- F-18 Labeled Agents (Pylarify, Axumin)
- Ga-68 Labeled Agents (Illuccix, Locametz)
- C-11 Choline
- Tc-99m Based Agents
- By Application:
- Staging of High-Risk Primary Prostate Cancer
- Detection of Biochemical Recurrence (BCR)
- Treatment Planning and Response Monitoring
- By End-User:
- Public and Private Hospitals
- Stand-alone Diagnostic and Imaging Centers
- Cancer Research Centers
Regional Highlights
- North America: The largest market, driven by the presence of major players like Lantheus and Blue Earth, and a robust reimbursement framework for PSMA PET imaging. The United States leads in the number of installed PET/CT bases globally.
- Europe: A mature market with strong growth in Germany, France, and the UK. Europe is a pioneer in theranostics, with many academic centers performing in-house labeling of Ga-68 PSMA.
- Asia Pacific: The fastest-growing region. China and India are investing heavily in nuclear medicine infrastructure. Japan’s aging population is a significant driver for prostate cancer diagnostic demand.
- Latin America: Brazil and Mexico are emerging as key hubs, though market growth is somewhat hampered by economic volatility and high import duties on equipment.
- Middle East & Africa: Growth is concentrated in the UAE, Saudi Arabia, and South Africa, where luxury "Medical City" projects are installing state-of-the-art PET/MRI facilities.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Prostate Cancer Nuclear Medicine Diagnostics Market.- Novartis AG (Advanced Accelerator Applications)
- Telix Pharmaceuticals
- Lantheus Holdings
- Blue Earth Diagnostics (Bracco Imaging)
- Curium
- GE Healthcare
- Siemens Healthineers
- Bayer AG
- Cardinal Health
- Jubilant Pharma
- Norgine (Life Molecular Imaging)
- Fujifilm Holdings
- ITM Isotope Technologies Munich SE
- GenesisCare
- Clarity Pharmaceuticals
- RadioMedix
- Eckert & Ziegler
- Positron Corporation
- IBA Radiopharma Solutions
- NorthStar Medical Radioisotopes
Frequently Asked Questions
What is the current market size of the Prostate Cancer Nuclear Medicine Diagnostics market?
As of 2025, the market is valued at approximately USD 1.08 Billion and is expected to grow significantly over the next decade as PSMA PET imaging becomes the standard of care for staging and recurrence detection.
What is PSMA PET imaging and why is it driving market growth?
PSMA PET imaging uses radiopharmaceuticals that target the Prostate-Specific Membrane Antigen found on the surface of prostate cancer cells. Its high sensitivity and specificity allow for earlier detection of metastases compared to conventional imaging, driving its widespread adoption.
Which radiopharmaceutical is leading the market: Ga-68 or F-18?
While Ga-68 was the first to gain prominence, F-18 labeled tracers (like Pylarify) are currently leading the market in regions like the US due to their longer half-life, which allows for centralized production and distribution to centers without an on-site cyclotron.
How does theranostics impact the diagnostic market?
Theranostics combines diagnostics and therapeutics. The success of radioligand therapies (like Pluvicto) requires a companion diagnostic PSMA PET scan to identify eligible patients, thereby creating a symbiotic growth relationship between the diagnostic and therapeutic markets.
What are the main challenges in the supply chain for nuclear medicine?
The primary challenges include the short physical half-life of isotopes, which requires precise logistics, and the global reliance on a few nuclear reactors for Mo-99/Tc-99m and other parent isotopes, making the supply chain vulnerable to reactor shutdowns.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
