Productivity Management Software Market
Productivity Management Software Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710957 | Published On : September 22, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Productivity Management Software Market Size
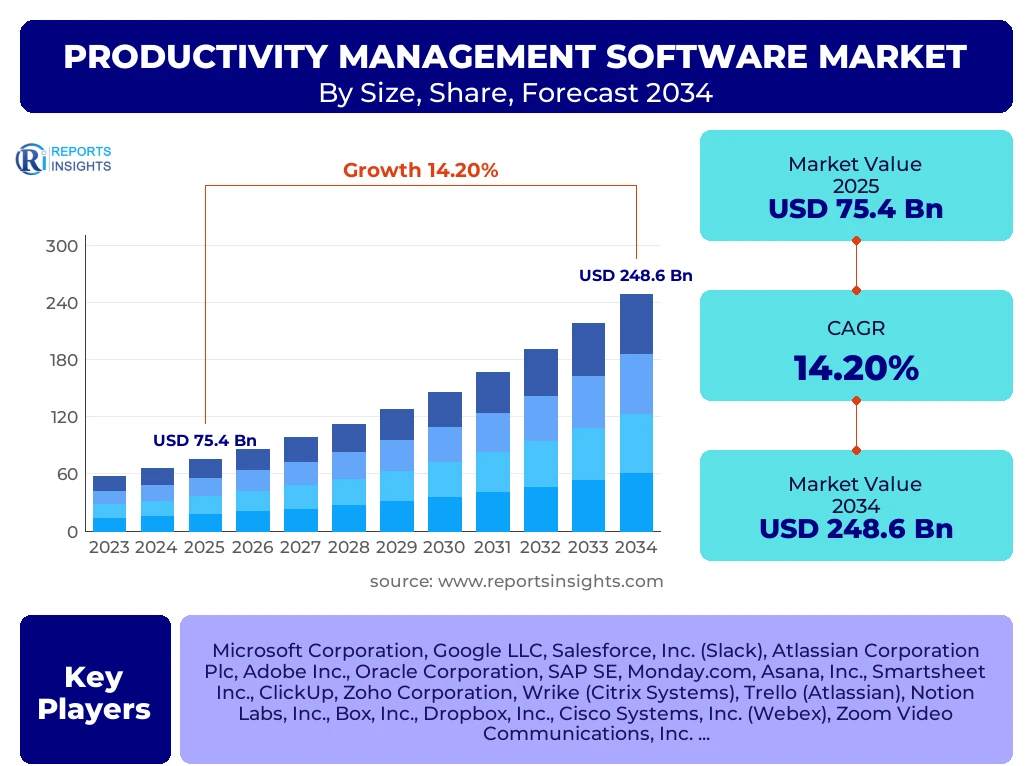
According to Reports Insights Consulting Pvt Ltd, The Productivity Management Software Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 14.2% between 2026 and 2034. The market is estimated at USD 86.1 Billion in 2026 and is projected to reach USD 248.6 Billion by the end of the forecast period in 2034.
Key Productivity Management Software Market Trends & Insights
The global Productivity Management Software market is undergoing a significant transformation driven by the integration of Generative Artificial Intelligence (AI) and the permanent shift toward hybrid work environments. Organizations are increasingly seeking unified platforms that consolidate disparate tools into a single ecosystem to reduce "app fatigue" and streamline workflows. Current market intelligence suggests that the demand for automated task prioritization and predictive analytics is reshaping how enterprises approach resource allocation. Furthermore, the emphasis on data sovereignty and secure collaboration is pushing developers to enhance encryption protocols and compliance features within their software suites.
- Largest Region: North America remains the dominant region, accounting for over 38% of the total market share due to early adoption of cloud technologies and high concentration of tech enterprises.
- Fastest Growing Region: Asia Pacific is anticipated to exhibit the highest CAGR through 2034, fueled by rapid digital transformation in India, China, and Southeast Asia.
- Largest Segment: The Cloud-based deployment segment holds the largest share, as businesses prioritize scalability, accessibility, and lower upfront infrastructure costs.
- Emerging Trend: Integration of Generative AI assistants (copilots) within content creation and project management tools is becoming a standard competitive requirement.
Key Takeaways Productivity Management Software Market Size & Forecast
The trajectory of the Productivity Management Software market indicates a robust expansion as digital-first operations become the baseline for global business competitiveness. Analysts observe that the transition from simple task tracking to comprehensive "Work OS" platforms is the primary catalyst for long-term growth. The market is also seeing a surge in specialized vertical solutions tailored for industries such as healthcare, construction, and legal services, which require specific compliance and workflow nuances. Strategic investments in user experience (UX) and mobile-first functionality are proving to be critical differentiators for vendors looking to capture the burgeoning SME market segment.
- Leading Country: The United States continues to lead in value, driven by massive investments from Fortune 500 companies into enterprise-wide digital productivity suites.
- Infrastructure Shift: There is a definitive move toward serverless architectures and microservices to support high-concurrency collaboration in real-time environments.
- SME Growth: Small and Medium Enterprises are expected to contribute significantly to the volume of new subscriptions as affordable SaaS models lower the barrier to entry.
- Competitive Landscape: The market is characterized by high fragmentation in the niche tool space, contrasted by extreme consolidation among the top five platform providers.
Productivity Management Software Market Drivers Analysis
The proliferation of remote and distributed workforces is the primary structural driver for the market, necessitating robust digital bridges for team coordination. As organizations strive for higher efficiency, the need to eliminate manual data entry and repetitive tasks has made workflow automation features indispensable. Additionally, the rapid advancement of Natural Language Processing (NLP) allows for more intuitive software interactions, broadening the user base to non-technical staff across all corporate departments.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rise of Hybrid and Remote Work Models | +4.5% | Global (Strongest in North America/Europe) | 2025 - 2034 |
| Integration of Generative AI and ML | +3.8% | United States, China, UK | 2025 - 2030 |
| SME Digital Transformation Initiatives | +2.9% | Asia Pacific (India, Vietnam) | 2026 - 2034 |
| Demand for Real-time Collaboration Tools | +3.0% | Global | 2025 - 2034 |
Productivity Management Software Market Restraints Analysis
Despite the optimistic growth outlook, the market faces significant headwinds related to data security and privacy regulations. The increasing frequency of cyberattacks targeting corporate data stored in the cloud has made some traditional industries hesitant to fully migrate their sensitive workflows. Furthermore, the complexity of integrating new productivity tools with legacy ERP and CRM systems often leads to operational friction and extended implementation timelines, which can deter potential adopters in the short term.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Security and Data Privacy Concerns | -2.1% | European Union (GDPR focus) | 2025 - 2034 |
| Interoperability and Legacy Integration Issues | -1.5% | Global (Industrial/Manufacturing sectors) | 2025 - 2028 |
| Subscription Fatigue and Budget Constraints | -1.2% | Latin America, Africa | 2025 - 2030 |
Productivity Management Software Market Opportunities Analysis
The emergence of the "citizen developer" movement presents a massive opportunity for low-code and no-code productivity platforms. By empowering non-technical employees to build their own custom workflows and applications, software vendors can deepen their penetration within the enterprise ecosystem. Additionally, the expansion into emerging markets where mobile penetration is high offers a pathway for mobile-centric productivity apps that cater to a younger, tech-savvy workforce.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Low-Code/No-Code Platform Expansion | +3.5% | Global | 2026 - 2034 |
| Vertical-Specific Productivity Solutions | +2.8% | North America, Germany, Japan | 2025 - 2034 |
| Mobile-First Productivity Applications | +2.2% | Southeast Asia, India, Brazil | 2027 - 2034 |
Productivity Management Software Market Challenges Impact Analysis
One of the most critical challenges facing the market is the saturation of common features, leading to intense price competition and margin pressure for vendors. As basic task management becomes commoditized, companies must constantly innovate in the realms of AI and advanced analytics to maintain a competitive edge. Moreover, the cultural resistance within some organizations to adopt digital-first workflows remains a significant barrier to achieving full market potential.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Feature Commoditization and Price Wars | -1.8% | Global | 2025 - 2034 |
| User Adoption and Cultural Resistance | -1.4% | Global | 2025 - 2029 |
| Rapid Technological Obsolescence | -1.1% | Silicon Valley, Global Tech Hubs | 2025 - 2034 |
Productivity Management Software Market - Updated Report Scope
The report provides an exhaustive analysis of the global Productivity Management Software landscape, covering historical data from 2020 to 2024 and delivering precise forecasts through 2034. It examines the market through various lenses, including deployment modes, organizational sizes, and diverse end-use industries. The scope also encompasses a detailed competitive benchmarking of the top 20 industry leaders, focusing on their product roadmaps, strategic partnerships, and regional expansion strategies. This analysis is designed to assist stakeholders in navigating the complex digital transformation environment with data-backed insights.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 75.4 Billion |
| Market Forecast in 2034 | USD 248.6 Billion |
| Growth Rate | 14.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Microsoft Corporation, Google LLC, Salesforce, Inc. (Slack), Atlassian Corporation Plc, Adobe Inc., Oracle Corporation, SAP SE, Monday.com, Asana, Inc., Smartsheet Inc., ClickUp, Zoho Corporation, Wrike (Citrix Systems), Trello (Atlassian), Notion Labs, Inc., Box, Inc., Dropbox, Inc., Cisco Systems, Inc. (Webex), Zoom Video Communications, Inc., HubSpot, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Productivity Management Software market reflects the diverse needs of the modern workforce, ranging from individual creative tasks to complex, multi-departmental project coordination. Cloud-based solutions continue to dominate due to the inherent flexibility they provide for remote workers. Among end-users, the IT and Telecom sector leads in adoption, although the Healthcare and BFSI sectors are showing accelerated growth as they digitize legacy document management and compliance processes. The task management segment is evolving rapidly, with a focus on visual progress tracking and automated dependencies.
- By Solution:
- Content Creation and Editing
- Communication and Collaboration
- Project and Task Management
- Time Tracking and Performance Monitoring
- Knowledge and Document Management
- By Deployment:
- Cloud-based (Public, Private, Hybrid)
- On-premise
- By Organization Size:
- Large Enterprises
- Small & Medium Enterprises (SMEs)
- By End-use Industry:
- Banking, Financial Services, and Insurance (BFSI)
- IT and Telecommunications
- Healthcare and Life Sciences
- Retail and E-commerce
- Manufacturing and Engineering
- Education and Government
- Others
Regional Highlights
- North America: Holds the largest market share, driven by the presence of major tech giants and a culture of rapid innovation and early software adoption. The U.S. is the primary contributor to the regional revenue.
- Europe: Exhibits steady growth with a heavy emphasis on data privacy and local cloud infrastructure. Germany, the UK, and France are the leading markets, particularly in manufacturing and financial services.
- Asia Pacific: Identified as the fastest-growing region. Rapid industrialization, a massive young workforce, and government-led digital initiatives in China and India are propelling the market forward.
- Latin America: Showing increased interest in affordable SaaS productivity tools as the startup ecosystem expands in Brazil, Mexico, and Chile.
- Middle East & Africa: Gaining momentum through smart city projects and digital transformation in the oil and gas and finance sectors, with the UAE and Saudi Arabia leading the charge.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Productivity Management Software Market.- Microsoft Corporation
- Google LLC
- Salesforce, Inc. (Slack)
- Atlassian Corporation Plc
- Adobe Inc.
- Oracle Corporation
- SAP SE
- Monday.com
- Asana, Inc.
- Smartsheet Inc.
- ClickUp
- Zoho Corporation
- Wrike (Citrix Systems)
- Trello (Atlassian)
- Notion Labs, Inc.
- Box, Inc.
- Dropbox, Inc.
- Cisco Systems, Inc. (Webex)
- Zoom Video Communications, Inc.
- HubSpot, Inc.
Frequently Asked Questions
What is the current and projected market size of Productivity Management Software?
The Productivity Management Software market is valued at approximately USD 86.1 Billion in 2026 and is expected to grow to USD 248.6 Billion by 2034, following a 14.2% CAGR.
What are the primary drivers for growth in this market?
Growth is primarily driven by the permanent shift to hybrid work models, the integration of Generative AI for automation, and the increasing digital transformation efforts within Small and Medium Enterprises (SMEs).
Which region is expected to grow the fastest during the forecast period?
The Asia Pacific region is projected to be the fastest-growing market due to rapid digitization, an expanding workforce, and increasing corporate investments in technology infrastructure.
How is AI impacting the Productivity Management Software market?
AI is revolutionizing the market by enabling automated content drafting, predictive scheduling, intelligent task prioritization, and advanced data analytics, significantly reducing the time spent on administrative overhead.
What are the key security concerns for Productivity Management Software users?
The main concerns include data breaches, unauthorized access to sensitive corporate information, and compliance with varying regional data protection laws like GDPR in Europe and CCPA in California.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted