Primary Biliary Cholangitis Therapeutics Market
Primary Biliary Cholangitis Therapeutics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711305 | Published On : October 25, 2026 |
Format : 


 | Author : Erika Grotto
Primary Biliary Cholangitis Therapeutics Market Size
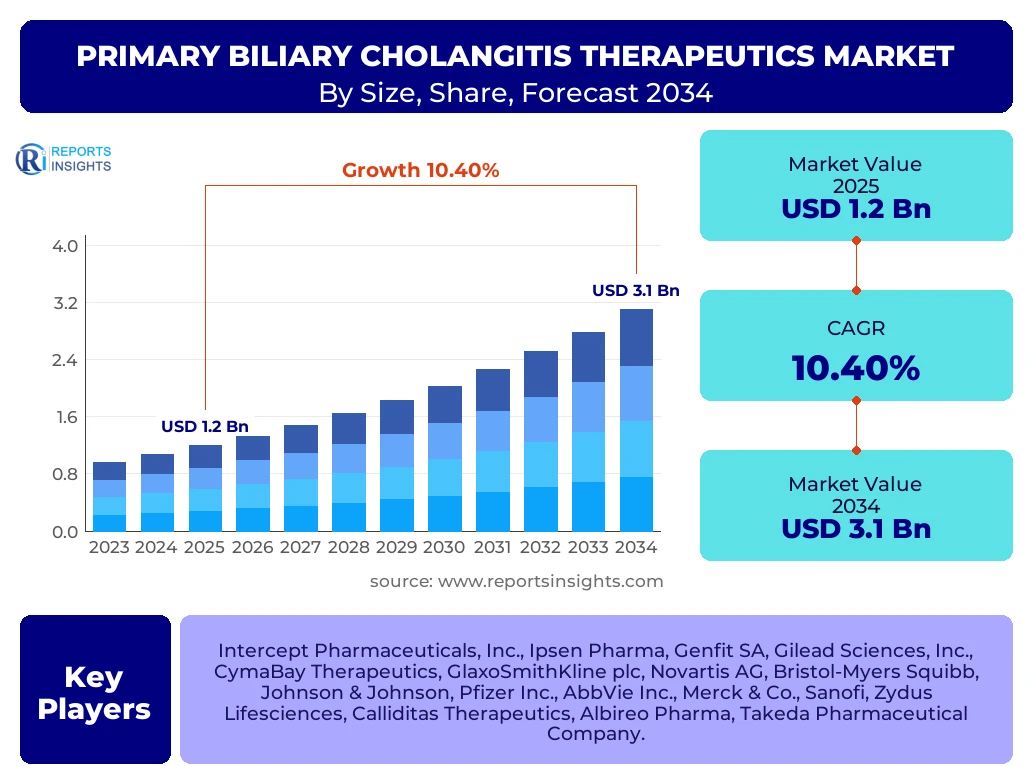
According to Reports Insights Consulting Pvt Ltd, The Primary Biliary Cholangitis Therapeutics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 10.4% between 2025 and 2034. The market is estimated at USD 1.32 Billion in 2026 and is projected to reach USD 3.1 Billion by the end of the forecast period in 2034.
Key Primary Biliary Cholangitis Therapeutics Market Trends & Insights
The global market for Primary Biliary Cholangitis (PBC) therapeutics is undergoing a transformative shift characterized by the transition from singular bile acid therapy to multi-modal pharmacological approaches. User interest and industry focus are increasingly directed toward second-line therapies as approximately 40% of patients show an incomplete response to the standard-of-care Ursodeoxycholic Acid (UDCA). Current competitive benchmarking highlights a significant surge in the development of Peroxisome Proliferator-Activated Receptor (PPAR) agonists and Farnesoid X Receptor (FXR) agonists, which aim to address biochemical non-response and pruritus simultaneously. Furthermore, the integration of non-invasive biomarkers, such as FibroScan and alkaline phosphatase (ALP) levels, is streamlining clinical trial endpoints and accelerating the approval process for novel biologics and small molecules.
- Largest Region: North America remains the dominant regional market, holding a share of over 45% due to high diagnosis rates and early adoption of premium-priced second-line therapies.
- Fastest Growing Region: Asia Pacific is anticipated to exhibit the highest CAGR through 2034, driven by improving healthcare infrastructure and rising awareness of rare autoimmune liver diseases in China and India.
- Largest Segment by Drug Class: The FXR Agonists segment currently holds the largest share among second-line treatments, though PPAR Agonists are the fastest-growing sub-segment.
- Dominant Distribution Channel: Hospital Pharmacies account for the majority of the market share, supported by the specialized nature of hepatology treatments.
Key Takeaways Primary Biliary Cholangitis Therapeutics Market Size & Forecast
The Primary Biliary Cholangitis therapeutics market is poised for robust expansion as pharmaceutical innovators focus on specialized niche indications within hepatology. Key market takeaways suggest that the market is moving away from generic UDCA reliance toward high-value, branded specialty drugs. Stakeholders are closely monitoring the commercialization of newly approved therapies like Seladelpar and Elafibranor, which are expected to redefine the treatment algorithm for patients who are intolerant to current therapies. The forecast period underscores a significant investment in late-stage clinical pipelines, suggesting a highly competitive landscape with frequent mergers and acquisitions involving rare disease specialists.
- United States Leadership: The U.S. market is the primary revenue generator, supported by favorable reimbursement policies for orphan drugs and high healthcare expenditure.
- Orphan Drug Designations: A significant portion of the pipeline holds Orphan Drug Status, providing manufacturers with extended market exclusivity and tax credits.
- Focus on Pruritus: New therapeutics are increasingly assessed not just for liver enzyme reduction but for their efficacy in managing PBC-associated pruritus (itching), a major quality-of-life factor.
- Strategic Collaborations: Cross-border partnerships between biotech firms and large pharmaceutical entities are accelerating the global distribution of second-line agents.
Primary Biliary Cholangitis Therapeutics Market Drivers Analysis
The market is primarily propelled by the rising global prevalence of autoimmune liver conditions and the continuous evolution of diagnostic capabilities. As medical professionals transition toward early intervention and personalized medicine, the demand for targeted therapeutics that can prevent disease progression to cirrhosis is escalating rapidly.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Unmet Need for Second-Line Therapies | +4.2% | Global | 2025 - 2034 |
| Rising FDA Approvals for PPAR Agonists | +3.5% | United States & Europe | 2025 - 2028 |
| Expansion of Diagnostic Biomarkers | +2.7% | Developed Markets | 2026 - 2034 |
Primary Biliary Cholangitis Therapeutics Market Restraints Analysis
Despite growth, the market faces constraints such as the high cost of specialized biologics and the lack of awareness in developing economies. Regulatory hurdles and the potential for adverse side effects in advanced cirrhosis patients also limit the rapid adoption of certain new molecular entities.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Orphan Drugs | -2.1% | Latin America & MEA | 2025 - 2034 |
| Stringent Regulatory Approval Cycles | -1.5% | European Union | 2025 - 2030 |
Primary Biliary Cholangitis Therapeutics Market Opportunities Analysis
The expansion into emerging markets and the development of combination therapies present significant growth avenues. Companies investing in digital health platforms for patient monitoring and real-world evidence (RWE) generation are likely to gain a competitive advantage in securing reimbursement.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Market Entry in APAC & BRICS | +3.8% | China, India, Brazil | 2027 - 2034 |
| Combination Therapy Research | +2.4% | Global | 2026 - 2034 |
Primary Biliary Cholangitis Therapeutics Market Challenges Impact Analysis
Challenges include the difficulty of conducting clinical trials in rare disease populations and the competitive pressure from generic manufacturers of first-line agents. Maintaining long-term safety profiles for new drug classes remains a critical concern for clinicians.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Recruitment for Rare Disease Trials | -1.8% | Global | Ongoing |
| Side Effect Profiles (e.g., Pruritus in FXR) | -1.2% | Developed Markets | 2025 - 2029 |
Primary Biliary Cholangitis Therapeutics Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the therapeutic landscape for PBC, covering drug classes from traditional bile acids to emerging targeted therapies. It includes financial modeling, competitive intelligence, and regional demand forecasting to provide a holistic view of the market ecosystem for the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.2 Billion |
| Market Forecast in 2034 | USD 3.1 Billion |
| Growth Rate | 10.4% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Intercept Pharmaceuticals, Inc., Ipsen Pharma, Genfit SA, Gilead Sciences, Inc., CymaBay Therapeutics, GlaxoSmithKline plc, Novartis AG, Bristol-Myers Squibb, Johnson & Johnson, Pfizer Inc., AbbVie Inc., Merck & Co., Sanofi, Zydus Lifesciences, Calliditas Therapeutics, Albireo Pharma, Takeda Pharmaceutical Company. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on pharmacological mechanism, patient response profiles, and logistical supply chains. The transition from first-line UDCA treatment to advanced second-line agents like FXR and PPAR agonists represents the most significant value-add segment in the current market landscape. While UDCA remains the volume leader, premium-priced second-line therapies are driving the majority of revenue growth.
- By Drug Class:
- Bile Acids: The foundational treatment (UDCA) used for initial diagnosis.
- FXR Agonists: Includes Obeticholic Acid, primarily for patients with inadequate response to UDCA.
- PPAR Agonists: The high-growth segment featuring novel drugs like Elafibranor and Seladelpar.
- Others: Investigational agents including biologics and antifibrotics.
- By Distribution Channel:
- Hospital Pharmacies: Dominant for initial prescription and monitoring.
- Retail Pharmacies: Increasing share for long-term maintenance therapy.
- Online Pharmacies: Rapidly growing due to convenience and home delivery of chronic medications.
Regional Highlights
- North America: Currently the largest market due to high healthcare spending, a robust network of hepatology centers, and early access to FDA-approved orphan drugs. The US accounts for the bulk of this regional share.
- Europe: The second-largest market, with significant contributions from Germany, France, and the UK. Centralized health systems are increasingly providing reimbursement for second-line PBC treatments.
- Asia Pacific: The fastest-growing region. Improvements in diagnostic techniques and an aging population in China and Japan are leading to higher detection rates of PBC, creating a large untapped patient pool.
- Latin America & MEA: These regions are seeing moderate growth as healthcare infrastructure improves and awareness regarding autoimmune liver diseases increases among general practitioners.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Primary Biliary Cholangitis Therapeutics Market.- Intercept Pharmaceuticals, Inc.
- Ipsen Pharma
- Genfit SA
- Gilead Sciences, Inc.
- CymaBay Therapeutics (Acquired by Gilead)
- GlaxoSmithKline plc
- Novartis AG
- Bristol-Myers Squibb
- Johnson & Johnson
- Pfizer Inc.
- AbbVie Inc.
- Merck & Co., Inc.
- Sanofi
- Zydus Lifesciences
- Calliditas Therapeutics
- Albireo Pharma (Acquired by Ipsen)
- Takeda Pharmaceutical Company
- Escient Pharmaceuticals
- Mirum Pharmaceuticals
Frequently Asked Questions
What is the current standard of care for Primary Biliary Cholangitis?
The standard of care remains Ursodeoxycholic Acid (UDCA), which is the first-line therapy. However, for the 40% of patients who do not respond adequately, second-line options like Obeticholic Acid or newly approved PPAR agonists are utilized.
What is driving the high CAGR in the PBC therapeutics market?
The market growth is driven by the introduction of expensive, targeted second-line therapies (PPAR and FXR agonists), an increase in disease prevalence awareness, and a robust pipeline of orphan drugs entering the commercialization phase.
Are there new drugs expected to be approved between 2025 and 2034?
Yes, several PPAR agonists such as Seladelpar and Elafibranor have recently received or are nearing regulatory approvals, which are expected to significantly shift the market dynamics in the forecast period.
Which region is expected to dominate the market share by 2034?
North America is expected to maintain its dominant position in terms of market share due to its established reimbursement framework and high adoption rates of premium specialty medications.
How does pruritus affect the PBC therapeutics market?
Pruritus is a debilitating symptom of PBC. Many new drugs are being evaluated for their ability to alleviate itching, which is a major differentiator for market success and patient compliance.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
