Precision Farming Market
Precision Farming Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711142 | Published On : October 12, 2026 |
Format : 


 | Author : Shawn Patel
Precision Farming Market Size
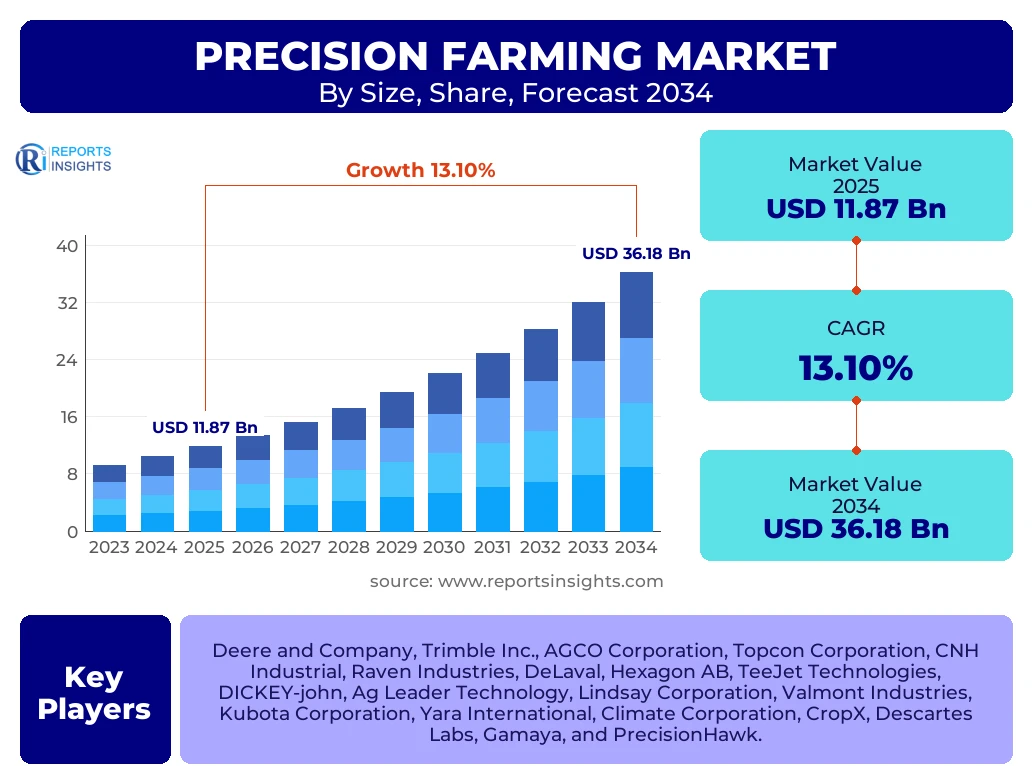
According to Reports Insights Consulting Pvt Ltd, The Precision Farming Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 13.1% between 2025 and 2034. The market is estimated at USD 13.42 Billion in 2026 and is projected to reach USD 36.18 Billion by the end of the forecast period in 2034.
Key Precision Farming Market Trends & Insights
The precision farming market is currently undergoing a radical transformation driven by the convergence of high-speed connectivity, artificial intelligence, and autonomous machinery. Modern agriculture is shifting from traditional uniform field management to site-specific crop management (SSCM), where variability within a single field is measured and managed with surgical precision. This transition is underpinned by the urgent need to optimize resource utilization, including water, fertilizers, and pesticides, in response to fluctuating commodity prices and tightening environmental regulations globally. Enterprise-level stakeholders are increasingly investing in integrated digital ecosystems that allow for seamless data flow between sensors, cloud platforms, and automated equipment.
Current technological advancements are predominantly focused on the democratization of data. Satellite imagery, which was once cost-prohibitive, is now readily available with high temporal resolution, enabling farmers to monitor crop health in near real-time. Furthermore, the integration of 5G technology is facilitating the deployment of massive IoT sensor networks, providing granular insights into soil moisture, nutrient levels, and local micro-climates. These trends indicate a move toward fully autonomous farming operations, where decision-making is assisted by predictive analytics and machine learning algorithms that can forecast yield outcomes with high accuracy.
- Largest Region: North America remains the dominant market due to early technology adoption and large-scale industrialized farming operations.
- Fastest Growing Region: Asia-Pacific is expected to witness the highest CAGR, fueled by rapid digitalization in countries like China and India and government subsidies for ag-tech.
- Leading Segment by Offering: The Hardware segment, including GPS/GNSS systems and sensors, currently holds the largest market share.
- Leading Segment by Application: Yield Monitoring represents the primary application, as it provides the fundamental data required for further precision interventions.
- Emerging Trend: The rise of Farm Management Information Systems (FMIS) as a centralized hub for cross-platform data integration.
Key Takeaways Precision Farming Market Size & Forecast
The precision farming sector is positioned for sustained growth as global food demand rises in tandem with a shrinking agricultural workforce. The market forecast reflects a clear trajectory toward automation and intelligence, where the emphasis is shifting from hardware sales to recurring service-based revenue models. As input costs rise, the value proposition of precision tools—centered on waste reduction and yield maximization—becomes indisputable for both small-holders and large-scale commercial enterprises. Investors and technology providers are prioritizing interoperability between different brands of machinery, which has historically been a significant barrier to widespread adoption.
- Market Valuation: The total addressable market is expected to triple over the next decade as emerging economies modernize their agricultural infrastructure.
- Technology Dominance: Guidance systems and variable rate technology (VRT) are becoming standard features in new agricultural machinery.
- Strategic Focus: Leading players are pivoting toward AI-driven software solutions to provide actionable insights rather than just raw data.
- Regional Leadership: The United States and Canada continue to lead in per-acre technology investment, while Brazil is emerging as a critical growth engine in Latin America.
- Sustainability Impact: Precision farming is increasingly recognized as a core component of ESG (Environmental, Social, and Governance) strategies for large agribusinesses.
Precision Farming Market Drivers Analysis
The primary catalysts for the precision farming market include the global imperative for food security and the critical shortage of skilled agricultural labor. As the global population approaches 10 billion by mid-century, traditional farming methods are proving insufficient to meet the required caloric output. Precision technologies enable higher yields per hectare while minimizing the environmental footprint. Additionally, government initiatives worldwide are incentivizing the adoption of smart farming tools through subsidies and grants aimed at sustainable land management.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of AI and Machine Learning | +3.2% | Global | 2025 - 2034 |
| Rising Global Food Demand | +2.8% | Developing Economies (India, China) | 2025 - 2034 |
| Government Subsidies for Ag-Tech | +2.1% | Europe and Asia-Pacific | 2025 - 2030 |
| Labor Shortages in Rural Areas | +1.9% | North America and Western Europe | 2025 - 2034 |
Precision Farming Market Restraints Analysis
Despite the high potential, the precision farming market faces significant hurdles related to the initial capital investment required for high-end technology. For many small to medium-sized farms, the cost of advanced sensors, drones, and autonomous tractors remains prohibitive without substantial financing. Furthermore, the lack of standardized data protocols between different equipment manufacturers often leads to fragmentation, preventing farmers from fully utilizing data across their entire fleet.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Investment Costs | -2.4% | Latin America and Africa | 2025 - 2028 |
| Data Privacy and Ownership Concerns | -1.5% | European Union (GDPR compliance) | 2025 - 2034 |
| Limited Technical Knowledge among Farmers | -1.2% | Emerging Markets | 2025 - 2030 |
Precision Farming Market Opportunities Analysis
The expansion of 5G networks into rural regions presents a massive opportunity for real-time telemetry and edge computing applications in the field. This connectivity will allow for the mass adoption of autonomous "swarms" of small robots that can manage crops at an individual plant level. Additionally, the growing carbon credit market offers a new revenue stream for farmers who use precision tools to document and prove sustainable practices, such as reduced fertilizer application and improved soil sequestration.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of 5G Rural Infrastructure | +4.1% | USA, South Korea, China | 2026 - 2034 |
| Carbon Credit Monetization via Data | +2.5% | Global | 2027 - 2034 |
| Autonomous Swarm Robotics | +1.8% | North America and Japan | 2028 - 2034 |
Precision Farming Market Challenges Impact Analysis
Technical challenges remain centered around the robustness of hardware in harsh agricultural environments. Sensors and electronic components must withstand extreme temperatures, moisture, and dust over long periods without frequent maintenance. Additionally, the digital divide in rural infrastructure, particularly the lack of reliable broadband in remote parts of Africa and South America, continues to hinder the deployment of cloud-based precision farming platforms.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rural Connectivity Gaps | -2.0% | Africa and Parts of Latin America | 2025 - 2034 |
| Interoperability Between OEM Platforms | -1.8% | Global | 2025 - 2030 |
| Extreme Weather Impact on Hardware | -0.7% | Global | 2025 - 2034 |
Precision Farming Market - Updated Report Scope
This report provides a comprehensive examination of the precision farming ecosystem, detailing the technological evolution from simple GPS guidance to fully autonomous, AI-driven operations. The scope encompasses hardware, software, and services across various agricultural applications, offering stakeholders a granular view of the competitive landscape and growth drivers across six major geographic regions. The analysis is built on a foundation of primary data from industry experts and secondary data from verified economic databases to ensure maximum accuracy.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 11.87 Billion |
| Market Forecast in 2034 | USD 36.18 Billion |
| Growth Rate | 13.1% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Deere and Company, Trimble Inc., AGCO Corporation, Topcon Corporation, CNH Industrial, Raven Industries, DeLaval, Hexagon AB, TeeJet Technologies, DICKEY-john, Ag Leader Technology, Lindsay Corporation, Valmont Industries, Kubota Corporation, Yara International, Climate Corporation, CropX, Descartes Labs, Gamaya, and PrecisionHawk. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The precision farming market is segmented by offering, technology, and application to provide a clear view of where value is being generated. Hardware remains the foundational segment, though Software is expanding rapidly as data processing becomes the key differentiator for competitive farming. Variable Rate Technology (VRT) is particularly significant as it directly influences the reduction of input costs, making it a high-priority investment for commercial farmers.
- By Offering:
- Hardware: Includes GPS/GNSS, sensors, drones, and automated steering systems.
- Software: Cloud-based and on-premise platforms for farm management.
- Services: Consulting, installation, and data analytics services.
- By Technology:
- Guidance Systems: Utilizing satellite positioning for precise vehicle movement.
- Remote Sensing: Multi-spectral imaging from satellites and UAVs.
- Variable Rate Technology: Precision application of seeds and chemicals.
- By Application:
- Yield Monitoring: Measuring and mapping crop productivity.
- Irrigation Management: Optimized water delivery based on soil moisture data.
- Crop Scouting: Identifying pest and disease outbreaks via automated imaging.
Regional Highlights
North America currently holds the largest market share, driven by the presence of major industry players and a high rate of mechanization. The United States is the primary contributor, where large farm sizes facilitate the economic viability of precision investments. Europe follows closely, with a strong focus on environmental regulations that mandate the use of precision tools to reduce nitrogen runoff and pesticide use.
- North America: Market leader; characterized by high adoption of autonomous tractors and large-scale data analytics.
- Europe: Focused on sustainability and "Green Deal" initiatives; high adoption of VRT and sensor technologies.
- Asia-Pacific: The fastest-growing region; driven by government support in China and India and a rising focus on rice and wheat yield optimization.
- Latin America: Significant potential in Brazil and Argentina for soybean and corn production; increasing use of satellite imagery and drones.
- Middle East and Africa: Growing interest in precision irrigation and soil management to combat water scarcity and desertification.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Precision Farming Market.- Deere and Company
- Trimble Inc.
- AGCO Corporation
- Topcon Corporation
- CNH Industrial
- Raven Industries
- DeLaval
- Hexagon AB
- TeeJet Technologies
- DICKEY-john
- Ag Leader Technology
- Lindsay Corporation
- Valmont Industries
- Kubota Corporation
- Yara International
- Climate Corporation
- CropX
- Descartes Labs
- Gamaya
- PrecisionHawk
Frequently Asked Questions
What is the primary benefit of adopting precision farming?
The primary benefit is the optimization of resources. By using data to apply seeds, water, and fertilizers only where and when they are needed, farmers can significantly reduce costs, increase yields, and minimize environmental impact.
What is the expected growth rate of the Precision Farming Market?
The market is projected to grow at a CAGR of 13.1% from 2025 to 2034, reaching an estimated value of over USD 36 billion by the end of the forecast period.
Which technology is most dominant in precision agriculture today?
Guidance and steering systems using GPS/GNSS technology are currently the most dominant, as they are the entry point for most farmers looking to improve field efficiency and reduce overlap.
How does AI impact precision farming operations?
AI enables predictive modeling, allowing farmers to anticipate pest outbreaks, predict weather impacts on yields, and automate decision-making processes for variable rate applications, shifting from reactive to proactive management.
What are the main barriers to market expansion in developing regions?
The main barriers include high initial setup costs, lack of reliable high-speed rural internet connectivity, and a shortage of technical training for smallholder farmers to interpret and act on digital data.
Author
S
Shawn Patel is a Manger Agriculture Research Industry with 6+ years of experience in the Agriculture Industry. He specializes in agricultural market intelligence, crop production analysis, agribusiness trend assessment, demand forecasting, competitive benchmarking, supply chain evaluation, precision agriculture technologies, commodity pricing analysis, and market sizing across farming and agricultural input sectors. His research combines industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, understand evolving market trends, and strengthen their competitive positioning in the global agriculture industry.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
