Polyvinyl Chloride PVC Films Market
Polyvinyl Chloride PVC Films Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711230 | Published On : October 21, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Polyvinyl Chloride Pvc Films Market Size
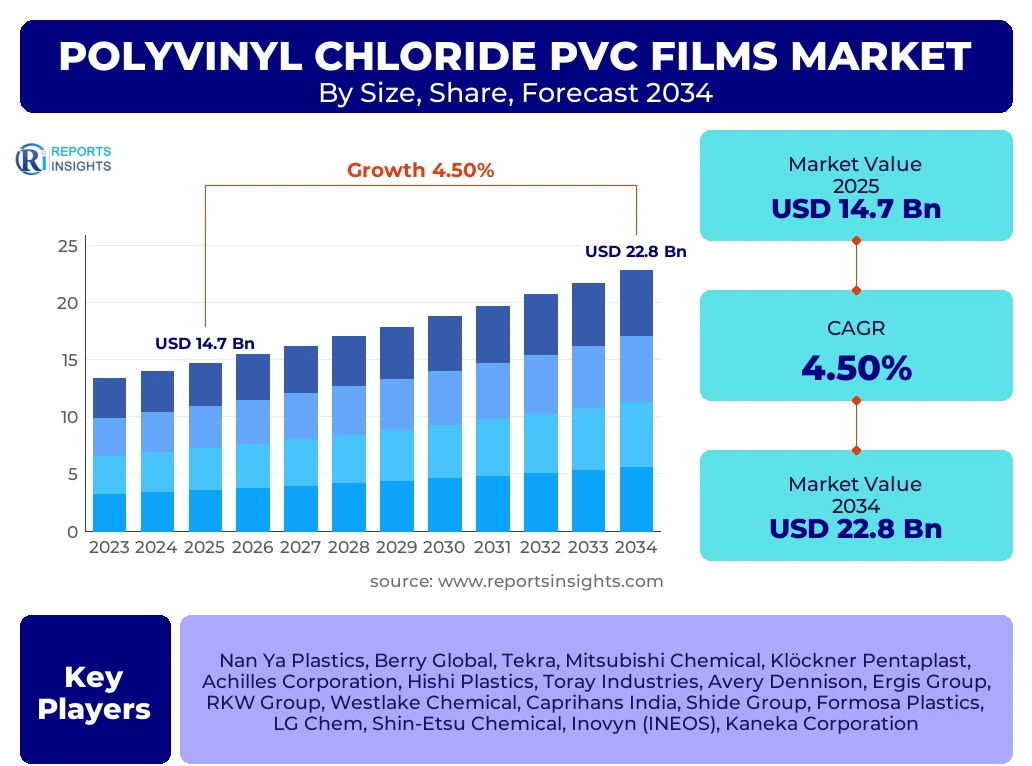
According to Reports Insights Consulting Pvt Ltd, The Polyvinyl Chloride Pvc Films Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.5% between 2025 and 2034. The market is estimated at USD 15.4 Billion in 2026 and is projected to reach USD 22.8 Billion by the end of the forecast period in 2034.
The global demand for Polyvinyl Chloride (PVC) films is driven by a convergence of industrial expansion in emerging economies and the increasing requirement for high-performance packaging solutions. As the construction and healthcare sectors undergo significant modernization, the adoption of specialized PVC films for applications ranging from building membranes to sterile medical packaging has surged. This market is characterized by a high degree of technical innovation, particularly in the development of phthalate-free and ultraviolet-resistant variants that cater to stringent environmental and safety regulations.
Furthermore, the logistical shift toward more efficient global supply chains has emphasized the need for durable, cost-effective wrapping and protection materials. PVC films, known for their exceptional versatility, transparency, and chemical resistance, remain a cornerstone in both consumer and industrial markets. The forecast period reflects a steady upward trajectory as manufacturers invest in advanced calendering and extrusion technologies to enhance product properties while optimizing production costs to maintain competitive pricing in a crowded global landscape.
Key Polyvinyl Chloride Pvc Films Market Trends & Insights
The Polyvinyl Chloride Pvc Films market is currently shaped by a structural transition toward sustainability and specialized application performance. Users and enterprise stakeholders frequently inquire about the impact of the circular economy on PVC usage, the shift from traditional plasticizers to bio-based alternatives, and the competitive benchmarking of major players in the Asia-Pacific region. Current trends indicate a significant move toward high-barrier films in the pharmaceutical industry to extend product shelf-life and ensure safety during long-distance transit. Additionally, the integration of digital printing capabilities directly onto PVC films is revolutionizing the decor and branding sectors, allowing for greater customization and reduced lead times.
- Largest Region: Asia-Pacific remains the dominant global force, accounting for over 45% of the total market share due to massive infrastructure projects and a booming manufacturing base in China and India.
- Fastest Growing Region: Southeast Asia and parts of Latin America are emerging as the fastest-growing zones, driven by rapid urbanization and the expansion of the retail sector.
- Largest Segment: Flexible PVC films hold the largest market share, utilized extensively in packaging, stationery, and industrial protective covers.
- Technological Shift: There is an increasing transition toward non-phthalate plasticizers to comply with REACH and FDA regulations in North America and Europe.
- Sustainability Focus: Development of recyclable PVC film grades and closed-loop recycling systems is becoming a primary competitive differentiator for global manufacturers.
Key Takeaways Polyvinyl Chloride Pvc Films Market Size & Forecast
The market trajectory for Polyvinyl Chloride (PVC) films underscores a robust recovery and growth phase post-global supply chain realignments. Analysis of market size and forecast data reveals that the integration of PVC films into the automotive sector for interior trim and protective coatings is a significant secondary growth engine. Decision-makers are increasingly focusing on the APAC region not just as a manufacturing hub, but as the primary demand center. The forecast suggests that while volume growth is steady, value growth is being driven by premium, high-specification films that offer superior thermal and chemical stability.
- China’s Market Dominance: China continues to be the leading producer and consumer of PVC films, influencing global pricing and raw material availability.
- Medical Grade Surge: The demand for medical-grade PVC films for IV bags and blister packaging is projected to outpace the general market CAGR.
- Urbanization Impact: The construction sector’s reliance on PVC films for flooring, roofing membranes, and window profiles remains a primary stabilizer for long-term demand.
- Regional Resilience: Despite regulatory pressures in Europe, the region remains a leader in technical PVC film innovation, focusing on high-end specialized applications.
- Supply Chain Optimization: Vertical integration among top-tier players is reducing price volatility and ensuring consistent quality for enterprise-level buyers.
Polyvinyl Chloride Pvc Films Market Drivers Analysis
The fundamental growth drivers of the PVC films market are rooted in the material’s unmatched cost-to-performance ratio and its critical role in essential industries. The global expansion of the healthcare infrastructure requires vast quantities of sterile, reliable packaging, while the ongoing urbanization in developing nations fuels the need for resilient construction materials. Additionally, the rise of e-commerce has necessitated durable secondary packaging solutions where PVC films provide necessary protection against moisture and physical damage during shipping.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Healthcare Infrastructure | +1.2% | Global (High in India/China) | 2025 - 2034 |
| Urbanization & Construction Demand | +0.9% | Asia-Pacific & Middle East | 2025 - 2030 |
| Growth in Food Packaging Sector | +0.8% | North America & Europe | 2026 - 2034 |
| Advancements in Calendering Technology | +0.6% | Germany & Japan | 2025 - 2034 |
Polyvinyl Chloride Pvc Films Market Restraints Analysis
The market faces significant headwinds from evolving environmental regulations and the negative public perception regarding plastic waste. Governments in developed regions are implementing stricter controls on the use of phthalates and specific stabilizers, forcing manufacturers to invest heavily in R&D for alternative formulations. Furthermore, the volatility of crude oil prices directly impacts the cost of vinyl chloride monomer (VCM), leading to unpredictable pricing structures for end-users.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Environmental Regulations (REACH) | -0.7% | European Union | 2025 - 2034 |
| Raw Material Price Volatility | -0.5% | Global | 2025 - 2028 |
| Competition from Bio-Based Films | -0.4% | North America | 2027 - 2034 |
Polyvinyl Chloride Pvc Films Market Opportunities Analysis
Strategic opportunities lie in the development of next-generation PVC films that align with "Green Building" certifications and the increasing demand for sustainable packaging. The shift toward electric vehicles (EVs) also presents a new frontier, as PVC films are used for interior aesthetic surfacing and battery insulation components. Moreover, the integration of antimicrobial properties into films for high-touch surfaces in public spaces and hospitals represents a high-value niche market that has gained momentum recently.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Electric Vehicle (EV) Interior Components | +1.1% | China, USA, Germany | 2026 - 2034 |
| Antimicrobial Film Formulations | +0.5% | Global | 2025 - 2030 |
| Smart Packaging Integration | +0.4% | Japan & South Korea | 2028 - 2034 |
Polyvinyl Chloride Pvc Films Market Challenges Impact Analysis
Operational challenges include the necessity of maintaining high quality-control standards in a market with low entry barriers for generic products. Manufacturers must navigate complex global trade policies and tariffs that can disrupt the export of finished films. Additionally, the technical challenge of improving the recyclability of multi-layered films remains a hurdle that requires cross-industry collaboration and significant capital investment in waste management infrastructure.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Recycling Logistics for Multi-Layer Films | -0.6% | Global | 2025 - 2034 |
| Trade Tariffs and Geo-Political Tensions | -0.4% | USA-China Trade | 2025 - 2028 |
Polyvinyl Chloride Pvc Films Market - Updated Report Scope
This report provides a granular analysis of the global Polyvinyl Chloride (PVC) films industry, covering historical trends from 2020 to 2024 and providing detailed projections through 2034. The scope encompasses rigid, flexible, and semi-rigid films across various end-use sectors including packaging, construction, medical, and automotive. It offers a comprehensive look at the competitive landscape, regulatory environment, and technological advancements driving the next decade of market evolution.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 14.7 Billion |
| Market Forecast in 2034 | USD 22.8 Billion |
| Growth Rate | 4.5% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Nan Ya Plastics, Berry Global, Tekra, Mitsubishi Chemical, Klöckner Pentaplast, Achilles Corporation, Hishi Plastics, Toray Industries, Avery Dennison, Ergis Group, RKW Group, Westlake Chemical, Caprihans India, Shide Group, Formosa Plastics, LG Chem, Shin-Etsu Chemical, Inovyn (INEOS), Kaneka Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Polyvinyl Chloride (PVC) films market is segmented by product type, manufacturing process, and end-use application to provide a multidimensional view of growth opportunities. Rigid films are primarily utilized in the pharmaceutical blister packaging and credit card sectors, where structural integrity is paramount. In contrast, flexible films dominate the industrial wrapping and consumer goods sectors due to their elasticity and clarity. The manufacturing process segment highlights the dominance of calendering for high-volume production, while extrusion techniques are gaining ground for specialized, thin-gauge film requirements.
The application-based segmentation reveals that the packaging industry remains the largest consumer, but the automotive and healthcare sectors are showing the highest rate of adoption for specialized film variants. For instance, automotive-grade PVC films are increasingly used for dashboards and door panels to provide a premium finish and durability. Meanwhile, in the healthcare sector, the transition from glass to flexible PVC bags for fluids has become a standard, driving consistent volume demand globally.
- By Product Type:
- Rigid PVC Films
- Flexible PVC Films
- Semi-Rigid PVC Films
- By Manufacturing Process:
- Calendering
- Extrusion (Blown and Cast)
- Others
- By End-Use Application:
- Packaging: Food & Beverage, Pharmaceuticals, Consumer Goods, Industrial
- Construction: Flooring, Waterproofing Membranes, Decorative Laminates
- Medical: IV Bags, Blood Bags, Tubing Components
- Automotive: Interior Trim, Protective Coatings, Upholstery
- Stationery and Labels: Tape Backing, Office Supplies, Signage
Regional Highlights
- Asia-Pacific (APAC): Holds the largest market share (45%+) and is the fastest-growing region. China and India are the primary engines of growth, supported by massive infrastructure investment and a robust pharmaceutical manufacturing sector.
- North America: A mature market characterized by high demand for medical-grade and high-barrier packaging films. The region is a leader in implementing phthalate-free regulations, driving innovation in safer chemical formulations.
- Europe: Focuses heavily on the circular economy and sustainable manufacturing. Germany and Italy are key hubs for technical PVC films used in automotive and high-end construction applications.
- Latin America: Expected to show steady growth as the retail and food packaging sectors modernize in Brazil and Mexico.
- Middle East & Africa: Growth is primarily linked to the construction sector and the localization of manufacturing to reduce import dependency.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Polyvinyl Chloride Pvc Films Market. These organizations are selected based on their market reach, product portfolio innovation, and strategic influence on global supply chains.
- Nan Ya Plastics Corporation
- Klöckner Pentaplast
- Mitsubishi Chemical Group
- Berry Global Inc.
- Tekra (A Division of EIS)
- Achilles Corporation
- Hishi Plastics (Mitsubishi Chemical)
- Toray Industries, Inc.
- Avery Dennison Corporation
- Ergis Group
- RKW Group
- Westlake Chemical Corporation
- Caprihans India Limited
- Shide Group
- Formosa Plastics Corporation
- LG Chem Ltd.
- Shin-Etsu Chemical Co., Ltd.
- Inovyn (INEOS Group)
- Kaneka Corporation
- Piedmont Plastics
Frequently Asked Questions
What is the current market size of the global Polyvinyl Chloride Pvc Films market?
The market is estimated to be valued at USD 15.4 Billion in 2026, with a projected growth to USD 22.8 Billion by 2034, following a steady CAGR of 4.5%.
Which industry is the primary consumer of PVC films?
The packaging industry, particularly for food and pharmaceuticals, remains the largest consumer, followed closely by the construction and medical sectors.
How are environmental regulations affecting the PVC films market?
Regulations like REACH in Europe and FDA guidelines in the US are driving manufacturers to replace traditional phthalates with safer, bio-based plasticizers, influencing product development and cost structures.
What region offers the highest growth potential for PVC film manufacturers?
The Asia-Pacific region, led by China and India, offers the highest growth potential due to rapid industrialization, urbanization, and a growing consumer middle class.
What are the key differences between rigid and flexible PVC films in terms of application?
Rigid PVC films are used where structural integrity and high barrier properties are needed, such as pharma blister packs, while flexible PVC films are preferred for applications requiring elasticity, like stretch wraps and IV bags.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
