Polymethyl Methacrylate Market
Polymethyl Methacrylate Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_704353 | Published On : October 19, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Polymethyl Methacrylate Market Size
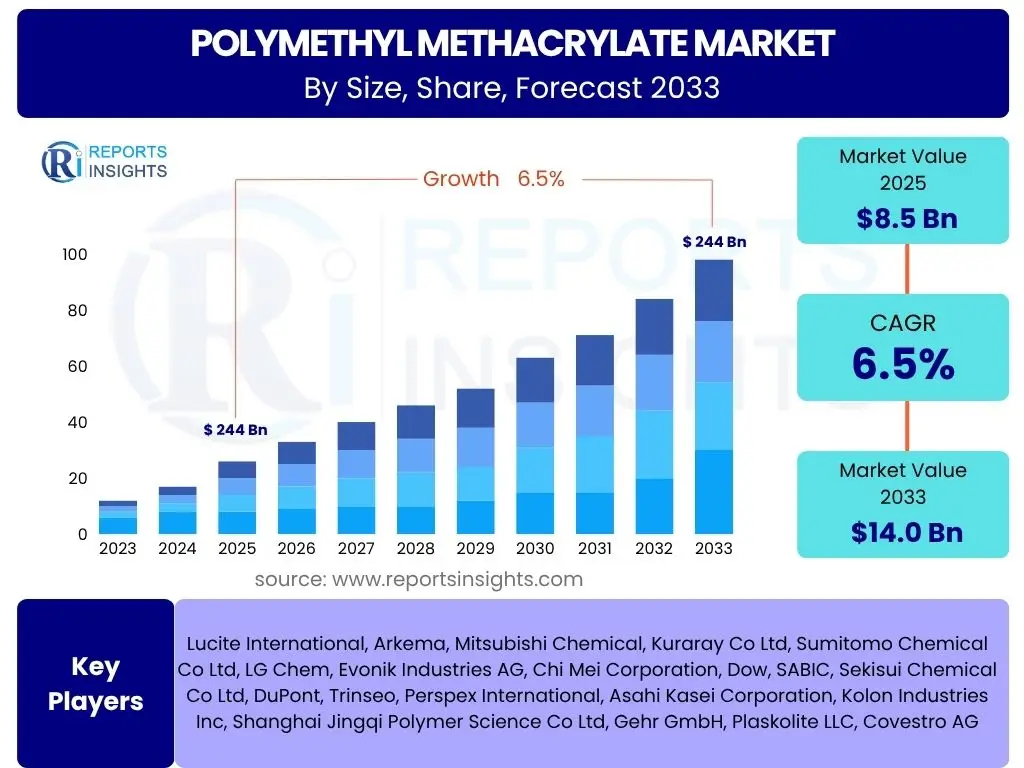
According to Reports Insights Consulting Pvt Ltd, The Polymethyl Methacrylate Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 5.82 Billion in 2026 and is projected to reach USD 9.98 Billion by the end of the forecast period in 2034.
Key Polymethyl Methacrylate Market Trends & Insights
The global Polymethyl Methacrylate (PMMA) market is undergoing a significant transformation driven by the transition toward lightweight materials in the automotive and aerospace industries. Advanced research into optical clarity and UV resistance has positioned PMMA as a superior alternative to traditional glass. Current market trends indicate a strong shift toward bio-based PMMA resins as manufacturers strive to meet stringent environmental sustainability goals. Furthermore, the integration of PMMA in high-tech applications, such as liquid crystal displays (LCDs) and light-emitting diodes (LEDs), continues to expand the material's footprint in the electronics sector. Competitive benchmarking reveals that leading players are focusing on backward integration to secure the supply of Methyl Methacrylate (MMA) monomer, thereby mitigating price volatility and ensuring consistent quality across various grades.
- Largest Region: Asia-Pacific remains the dominant market, accounting for over 45% of the global share due to massive industrialization in China and India.
- Fastest Growing Region: Southeast Asia is projected to be the fastest-growing sub-region, fueled by rapid urbanization and infrastructure development.
- Largest Segment by Form: Extruded sheets represent the largest segment by volume, utilized extensively in the construction and signage industries.
- Largest Segment by Application: The Signs and Displays segment holds the highest market share, followed closely by the Automotive sector.
- Leading Grade: Optical grade PMMA is witnessing the highest demand growth due to the proliferation of smartphone and television production.
Key Takeaways Polymethyl Methacrylate Market Size & Forecast
The Polymethyl Methacrylate market is characterized by robust demand across diversified end-use industries, particularly in emerging economies. Strategic analysis suggests that the forecast period will see a surge in specialized PMMA applications, such as medical devices and solar panels. The increasing adoption of PMMA in the healthcare sector for bone cements and intraocular lenses is creating high-margin opportunities for chemical manufacturers. As global supply chains stabilize, the focus is shifting toward regionalized production hubs to reduce logistics costs and carbon footprints. Stakeholders are also investing heavily in chemical recycling technologies to convert PMMA waste back into high-purity MMA, supporting a circular economy model.
- Dominant Country: China is the single largest consumer and producer of PMMA globally, significantly influencing market pricing and supply dynamics.
- Strategic Application: The automotive industry is the primary driver for high-impact PMMA grades used in rear lights, indicators, and interior trim.
- Technological Shift: There is a notable transition from traditional cast sheets to high-performance extruded pellets for injection molding applications.
- Economic Factor: Fluctuations in crude oil prices directly impact the production cost of MMA, which remains a critical variable for PMMA market stability.
- Sustainability Focus: Development of R-PMMA (Recycled PMMA) is becoming a core strategic pillar for European and North American manufacturers.
Polymethyl Methacrylate Market Drivers Analysis
The primary driver for the PMMA market is the global automotive industry's push for lightweighting. As electric vehicles (EVs) become more prevalent, reducing the overall weight of the vehicle is essential to maximize battery range. PMMA offers a weight reduction of up to 50% compared to glass while maintaining excellent weatherability and scratch resistance. Additionally, the rapid expansion of the construction sector in developing nations is boosting demand for PMMA sheets in glazing, roofing, and sound barriers. The material's high light transmittance (92%) makes it indispensable for modern architectural designs and energy-efficient building solutions.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Automotive Lightweighting & EV Adoption | +1.8% | Germany, USA, China | 2025 - 2034 |
| Rising Demand for LED & Flat Panel Displays | +1.5% | South Korea, Japan, Taiwan | 2025 - 2030 |
| Infrastructure Growth in Emerging Markets | +1.2% | India, Brazil, Indonesia | 2026 - 2034 |
| Expansion of Medical Grade Applications | +0.7% | Western Europe, North America | 2025 - 2034 |
Polymethyl Methacrylate Market Restraints Analysis
Despite its versatility, the PMMA market faces challenges related to the availability and price volatility of its primary raw material, Methyl Methacrylate (MMA). Disruptions in the global supply of acetone and methanol, which are key precursors, can lead to sharp increases in production costs. Furthermore, PMMA faces stiff competition from cheaper substitutes like Polycarbonate (PC) and Polystyrene (PS) in certain low-end applications. Environmental concerns regarding the persistence of acrylic polymers in landfills also prompt regulatory bodies to impose stricter recycling mandates, which may increase operational costs for manufacturers in the short term.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility (MMA) | -0.9% | Global | 2025 - 2028 |
| Competition from Polycarbonate Substitutes | -0.6% | Asia-Pacific, Europe | 2025 - 2034 |
| Stringent Environmental Regulations | -0.4% | European Union | 2026 - 2034 |
Polymethyl Methacrylate Market Opportunities Analysis
The emergence of bio-based monomers presents a significant growth opportunity for the PMMA industry. Research into deriving MMA from biomass rather than petrochemicals is gaining momentum, appealing to eco-conscious brands and consumers. Additionally, the expansion of the solar energy sector offers a new frontier for PMMA, where it is used as a concentrator and protective layer for photovoltaic cells due to its high transparency and durability. The development of antimicrobial PMMA for use in high-touch surfaces in hospitals and public transportation also represents a high-potential niche market following the global focus on hygiene and health safety.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based PMMA Resins | +1.4% | Germany, France, USA | 2027 - 2034 |
| Solar Photovoltaic Encapsulation | +1.1% | China, India, Australia | 2025 - 2034 |
| 3D Printing and Additive Manufacturing | +0.8% | USA, Japan | 2026 - 2034 |
Polymethyl Methacrylate Market Challenges Impact Analysis
One of the core challenges is the difficulty in recycling PMMA to its original optical quality. While mechanical recycling is possible, it often results in a loss of clarity and physical properties, limiting the use of recycled material in premium applications. Furthermore, the market must navigate complex trade dynamics, including anti-dumping duties on MMA and PMMA sheets in various jurisdictions. Maintaining profitability while adhering to the lowering of VOC (Volatile Organic Compound) emissions during the polymerization process requires significant capital investment in advanced manufacturing technology.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Recycling Limitations & Downcycling Issues | -0.5% | North America, Europe | 2025 - 2034 |
| Trade Barriers & Anti-dumping Duties | -0.4% | Global Trade Routes | 2025 - 2030 |
| VOC Emission Compliance Costs | -0.3% | China, European Union | 2025 - 2034 |
Polymethyl Methacrylate Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global Polymethyl Methacrylate market, covering various forms, grades, and end-use applications. The study provides quantitative and qualitative insights into market drivers, restraints, and opportunities across six major regions. It includes a comprehensive evaluation of the competitive landscape, featuring the strategies of top market players and their R&D initiatives. The report is designed to assist stakeholders in making informed investment decisions by providing a 10-year forecast and analyzing the impact of emerging technologies and regulatory shifts on the market trajectory.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.48 Billion |
| Market Forecast in 2034 | USD 9.98 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Mitsubishi Chemical Group Corporation, Evonik Industries AG, Sumitomo Chemical Co., Ltd., Arkema S.A., SABIC (Saudi Basic Industries Corporation), LG Chem, Ltd., Asahi Kasei Corporation, Trinseo S.A., Kuraray Co., Ltd., CHIMEI Corporation, Plaskolite LLC, Röhm GmbH, Saudi Arabia Acrylic Ester Company (SAMCO), Lotte Chemical Corporation, Kolon Industries, Inc., DOW Chemical Company, Toray Industries, Inc., Chi Mei Corporation, Formosa Plastics Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Polymethyl Methacrylate market is segmented based on form, grade, and application to provide a granular view of the industry. Extruded sheets dominate the market by volume, as they offer a cost-effective solution for large-scale construction and signage projects. Cast sheets, although more expensive, are preferred for high-end applications requiring superior optical clarity and thermal stability. The market is also bifurcated by grade, with Optical Grade PMMA witnessing rapid growth due to its role in the manufacturing of light guide plates (LGPs) for modern electronic devices. Application-wise, the automotive sector is a major revenue contributor, utilizing PMMA for a wide range of interior and exterior components.
- By Form:
- Extruded Sheets (Largest segment for signage and construction)
- Cast Sheets (High-performance grade for specialized glazing)
- Pellets (Primary form for injection molding in automotive/electronics)
- Beads (Used in specialized coatings and dental applications)
- By Grade:
- General Purpose Grade (Standard utility applications)
- Optical Grade (High light transmittance for displays and lenses)
- Medical Grade (Biocompatible grade for implants and labware)
- Impact Modified Grade (Enhanced toughness for industrial use)
- By Application:
- Automotive (Tail lights, instrument clusters, windows)
- Construction (Glazing, roofing, sound barriers, domes)
- Electronics (Monitor screens, mobile phone panels, LED lighting)
- Signs & Displays (Billboards, retail displays, illuminated signs)
- Medical (Intraocular lenses, bone cement, dental prosthetics)
- Others (Sanitary ware, furniture, solar panels)
Regional Highlights
- Asia-Pacific: The region is the largest market, driven by China's dominant position as the world's electronics and automotive manufacturing hub. India is also emerging as a significant consumer due to its growing urban infrastructure.
- North America: A major market for Medical Grade PMMA, supported by a highly developed healthcare sector and advanced research in biomedical engineering. The US is a key contributor to innovation in PMMA-based optical devices.
- Europe: The automotive powerhouse, with Germany and France leading the adoption of high-performance PMMA for lightweight vehicle components. Europe is also at the forefront of the bio-based PMMA and chemical recycling transition.
- Latin America: Growth is primarily centered in Brazil and Mexico, where the automotive assembly and construction sectors are expanding steadily.
- Middle East & Africa: Demand is largely driven by large-scale infrastructure projects and the region's focus on diversifying its industrial base beyond oil and gas.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Polymethyl Methacrylate Market.- Mitsubishi Chemical Group Corporation
- Evonik Industries AG
- Sumitomo Chemical Co., Ltd.
- Arkema S.A.
- SABIC (Saudi Basic Industries Corporation)
- LG Chem, Ltd.
- Asahi Kasei Corporation
- Trinseo S.A.
- Kuraray Co., Ltd.
- CHIMEI Corporation
- Plaskolite LLC
- Röhm GmbH
- Saudi Arabia Acrylic Ester Company (SAMCO)
- Lotte Chemical Corporation
- Kolon Industries, Inc.
- DOW Chemical Company
- Toray Industries, Inc.
- Chi Mei Corporation
- Formosa Plastics Corporation
Frequently Asked Questions
What is the primary difference between cast and extruded PMMA?
Cast PMMA is produced by pouring liquid monomer into a mold, resulting in higher molecular weight and superior optical clarity, making it ideal for precision engraving and high-end glazing. Extruded PMMA is manufactured by pushing pellets through an extruder, making it more cost-effective for high-volume production but with slightly lower thermal stability and chemical resistance.
How is the growth of electric vehicles (EVs) impacting the PMMA market?
EV adoption is a major driver for the PMMA market because manufacturers are under pressure to reduce vehicle weight to extend battery range. PMMA is increasingly used to replace glass in windows and sunroofs, as it is 50% lighter, offers excellent UV protection, and provides high impact resistance.
Is PMMA considered an environmentally friendly plastic?
Standard PMMA is a petroleum-based thermoplastic and is not biodegradable. However, it is 100% recyclable. Recent industry advancements have led to the development of Bio-PMMA, derived from renewable sources, and R-PMMA, which uses chemical recycling to return the polymer to its original monomer state without loss of quality.
What are the key applications of medical-grade PMMA?
Medical-grade PMMA is highly valued for its biocompatibility and transparency. Key applications include the manufacturing of intraocular lenses for cataract surgery, bone cement for orthopedic procedures, and various dental prosthetics such as dentures and crowns.
Which factors influence the price of PMMA on a global scale?
The price of PMMA is primarily influenced by the cost of its raw material, Methyl Methacrylate (MMA), which is linked to crude oil and natural gas prices. Other factors include global supply-demand imbalances, energy costs for energy-intensive extrusion processes, and regional trade tariffs.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
