Polyethylene Terephthalate Additives Market
Polyethylene Terephthalate Additives Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711882 | Published On : November 20, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Polyethylene Terephthalate Additives Market Size
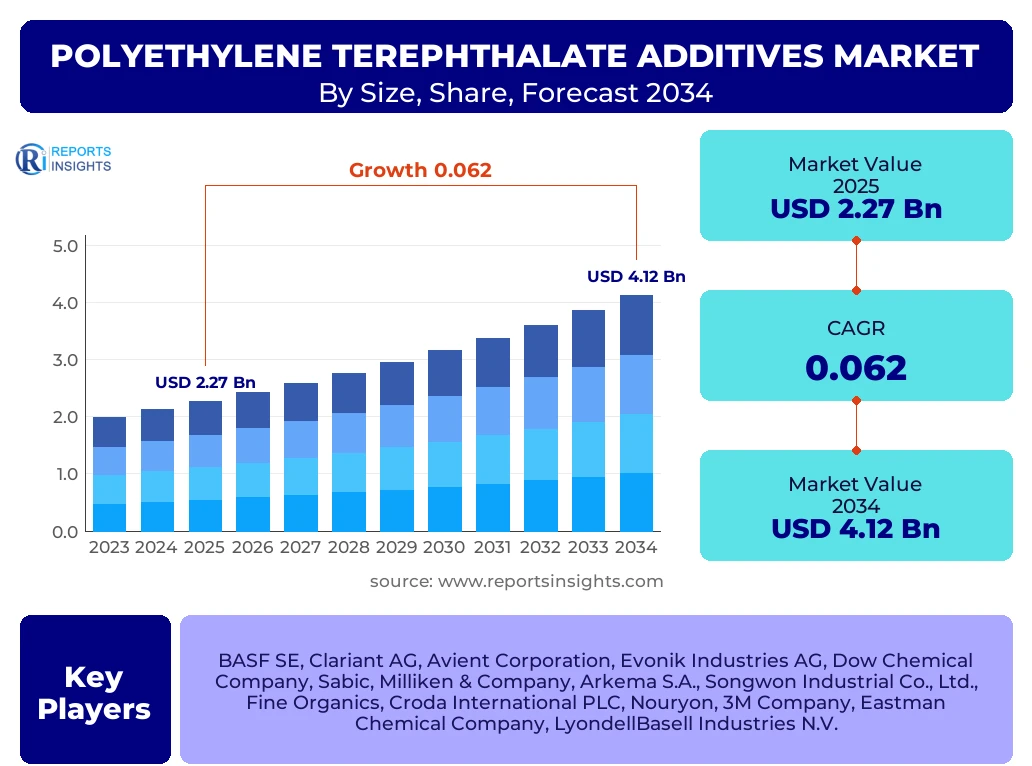
According to Reports Insights Consulting Pvt Ltd, The Polyethylene Terephthalate Additives Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 2.41 Billion in 2026 and is projected to reach USD 4.12 Billion by the end of the forecast period in 2034.
Key Polyethylene Terephthalate Additives Market Trends & Insights
The global landscape for Polyethylene Terephthalate (PET) additives is undergoing a transformative shift driven by the dual imperatives of high-performance packaging and environmental sustainability. As global regulatory bodies tighten mandates on plastic waste, the market is witnessing an unprecedented surge in the demand for recycling-assist additives, such as chain extenders and stabilizers, which restore the mechanical properties of recycled PET (rPET). Stakeholders are increasingly prioritizing additives that facilitate a circular economy without compromising the aesthetic and functional integrity of the final product. Furthermore, the integration of advanced barrier technologies to extend the shelf life of carbonated beverages and sensitive food products remains a primary area of innovation, particularly in the Asia-Pacific region where consumer demand is rapidly expanding.
- Asia-Pacific is the largest and fastest-growing region, fueled by massive beverage production in China and India.
- Nucleating agents and oxygen scavengers represent the largest segments in terms of value share due to their critical role in packaging performance.
- Sustainability-focused additives, specifically those designed for rPET processing, are experiencing the highest CAGR within the additive type segment.
- The food and beverage packaging industry continues to be the dominant end-user, accounting for over 50% of the total market share.
Key Takeaways Polyethylene Terephthalate Additives Market Size & Forecast
The trajectory of the Polyethylene Terephthalate Additives market is fundamentally linked to the evolution of the global packaging sector and the automotive industry’s drive toward lightweighting. Research indicates that the shift from traditional glass and metal packaging to PET-based solutions in the pharmaceutical and personal care sectors is creating significant tailwinds for additive manufacturers. Market forecasts suggest that the integration of UV stabilizers and anti-yellowing agents will become standard as brands seek to maintain premium product appearance over longer storage durations. Moreover, the strategic positioning of key players in emerging markets is expected to consolidate the supply chain, leading to more cost-effective localized production of high-performance additives.
- China and India are identified as the leading countries for market expansion due to industrialization and urban consumption patterns.
- Anti-stat and anti-fog additives are gaining traction in the specialized film and sheet market for high-end electronics and food display packaging.
- The forecast period 2025–2034 will see a significant shift toward bio-based additives to meet stringent ESG (Environmental, Social, and Governance) targets.
- Technological advancements in masterbatch delivery systems are improving additive dispersion, thereby reducing overall material waste and cost for converters.
Polyethylene Terephthalate Additives Market Drivers Analysis
The primary catalysts for the PET additives market revolve around the rising demand for sophisticated packaging solutions that offer both durability and environmental compatibility. The rapid growth of the e-commerce sector has necessitated packaging materials that can withstand rigorous logistics while remaining lightweight to minimize shipping costs. Additionally, the increasing consumer preference for processed and ready-to-drink (RTD) beverages is pushing manufacturers to utilize oxygen scavengers and UV stabilizers to preserve flavor and nutritional content, thereby driving the consumption of high-value additives.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Demand for rPET and Circular Economy Mandates | +1.8% | European Union, North America | 2025 - 2034 |
| Expansion of Food & Beverage Sector in Emerging Economies | +2.1% | India, China, Southeast Asia | 2025 - 2030 |
| Technological Innovation in Barrier and Scavenging Properties | +1.3% | Global | 2026 - 2034 |
Polyethylene Terephthalate Additives Market Restraints Analysis
Market growth is somewhat tempered by the volatility of raw material prices, which are closely tied to the petrochemical industry. Fluctuations in the cost of chemical precursors can lead to inconsistent pricing for additives, impacting the profit margins of plastic converters. Additionally, stringent regulatory hurdles regarding food-contact materials mean that new additive formulations must undergo lengthy and expensive approval processes before reaching the market, which can stifle innovation in smaller firms.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Petrochemical Feedstock Prices | -0.9% | Global | 2025 - 2034 |
| Strict Regulatory Standards for Food Contact Materials | -0.6% | USA (FDA), Europe (EFSA) | 2025 - 2030 |
Polyethylene Terephthalate Additives Market Opportunities Analysis
There is a substantial opportunity in the development of multi-functional masterbatches that combine several additives into a single delivery system. This allows manufacturers to simplify their production lines and improve operational efficiency. Furthermore, the burgeoning automotive and electronics sectors are increasingly utilizing PET-based composites for interior components and circuit housings, creating a niche market for high-temperature stabilizers and flame-retardant additives specifically tailored for PET resins.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of High-Performance Bio-Based Additives | +1.5% | Western Europe, Japan | 2027 - 2034 |
| Expansion into Medical-Grade PET Packaging | +1.2% | Global | 2026 - 2034 |
Polyethylene Terephthalate Additives Market Challenges Impact Analysis
One of the most pressing challenges is the technical complexity involved in maintaining the clarity and mechanical properties of PET when high concentrations of recycled content are used. The presence of impurities in the recycling stream requires highly specialized additives that are often more expensive than standard variants. Moreover, the industry faces pressure from environmental groups to reduce overall plastic usage, which may lead to a shift toward alternative materials like glass or aluminum in certain premium segments.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Maintaining Clarity and Aesthetic in High-Recycle Content | -0.7% | Developed Markets | 2025 - 2034 |
| Competition from Alternative Packaging Materials | -0.5% | Global | 2025 - 2034 |
Polyethylene Terephthalate Additives Market - Updated Report Scope
This report provides a comprehensive examination of the Polyethylene Terephthalate Additives market, encompassing a detailed analysis of additive types, application areas, and end-user industries. The scope extends to a granular regional assessment, covering key manufacturing hubs and consumption markets globally. It highlights the competitive landscape by profiling industry leaders and evaluating their strategic initiatives, R&D focus, and market positioning. The report also integrates macroeconomic indicators and regulatory frameworks to provide a holistic view of the market dynamics over the forecast period of 2025 to 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.27 Billion |
| Market Forecast in 2034 | USD 4.12 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Clariant AG, Avient Corporation, Evonik Industries AG, Dow Chemical Company, Sabic, Milliken & Company, Arkema S.A., Songwon Industrial Co., Ltd., Fine Organics, Croda International PLC, Nouryon, 3M Company, Eastman Chemical Company, LyondellBasell Industries N.V. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Polyethylene Terephthalate Additives market reflects the diverse functional requirements across various industries. Nucleating agents lead the market by type, as they significantly reduce the cooling time during injection molding and improve the clarity of the final product. The packaging application, specifically bottles, remains the largest segment, driven by the global beverage industry's reliance on PET for its lightweight and shatterproof qualities. End-use analysis reveals that while Food & Beverage is the dominant force, the Automotive and Electronics segments are emerging as high-growth areas due to the increasing use of PET in high-performance engineering plastics.
- By Additive Type:
- Nucleating Agents: Essential for increasing crystallization rates and improving mechanical properties.
- Oxygen Scavengers: Critical for extending the shelf life of oxidation-sensitive products like beer and fruit juices.
- UV Stabilizers: Prevent degradation and discoloration of PET when exposed to sunlight.
- Impact Modifiers: Enhance the toughness and durability of PET for industrial and automotive applications.
- Chain Extenders: Vital for increasing the molecular weight of recycled PET to ensure processability.
- By Application:
- Bottles: The primary application, encompassing mineral water, carbonated soft drinks, and alcoholic beverages.
- Films and Sheets: Used extensively in food packaging trays and electronic display components.
- Fibers: Applied in the textile industry for synthetic fabrics and carpets.
- By End-Use Industry:
- Food & Beverage: The highest consumer of PET additives for packaging solutions.
- Pharmaceuticals: Increasing use of PET for medicine bottles and blister packs due to its barrier properties.
- Automotive: Growing utilization of PET in interior trims and under-the-hood components.
Regional Highlights
- Asia-Pacific: Dominates the global market with a share of approximately 42%, driven by the massive manufacturing bases in China, India, and Vietnam. The region is also the fastest-growing due to rising middle-class consumption and rapid urbanization.
- North America: A mature market characterized by a strong focus on high-performance additives and sustainable packaging. The U.S. market is a leader in the development of advanced oxygen scavenging technologies.
- Europe: The leading region for regulatory-driven innovation. Strict EU directives on single-use plastics and recycling targets are propelling the demand for additives that facilitate PET circularity.
- Latin America: Showing steady growth, particularly in Brazil and Mexico, where the beverage industry is expanding its footprint and upgrading packaging standards.
- Middle East & Africa: Emerging as a potential hub for PET production, with investments in petrochemical infrastructure supporting the localized manufacture of plastic additives.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Polyethylene Terephthalate Additives Market.
- BASF SE
- Clariant AG
- Avient Corporation
- Evonik Industries AG
- Dow Chemical Company
- Sabic
- Milliken & Company
- Arkema S.A.
- Songwon Industrial Co., Ltd.
- Fine Organics
- Croda International PLC
- Nouryon
- 3M Company
- Eastman Chemical Company
- LyondellBasell Industries N.V.
Frequently Asked Questions
What is the current market size and projected growth of the Polyethylene Terephthalate Additives market?
The market is estimated at USD 2.41 Billion in 2026 and is expected to reach USD 4.12 Billion by 2034, growing at a CAGR of 6.2% over the forecast period. This growth is driven by increased demand for sustainable packaging and advanced barrier properties.
Which type of PET additive is currently leading the market?
Nucleating agents are currently the leading additive type. They are essential for optimizing the production process by increasing crystallization rates, which improves both the manufacturing efficiency and the physical clarity of PET products.
How is the demand for recycled PET (rPET) impacting the additives market?
The push for a circular economy has significantly increased the demand for chain extenders and stabilizers. These additives are crucial for restoring the molecular weight and mechanical properties of recycled PET, allowing it to be used in high-quality packaging applications.
Which region holds the largest share of the Polyethylene Terephthalate Additives market?
The Asia-Pacific region holds the largest market share, accounting for over 40% of global demand. This dominance is due to the region's vast food and beverage industry and the concentration of major plastic resin and additive manufacturing facilities.
What are the primary challenges facing manufacturers in this market?
Key challenges include the volatility of petrochemical-based raw material prices and the technical difficulty of maintaining product quality (such as color and transparency) when using high percentages of recycled material.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
