Polyetheramine Market
Polyetheramine Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711398 | Published On : October 31, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Polyetheramine Market Size
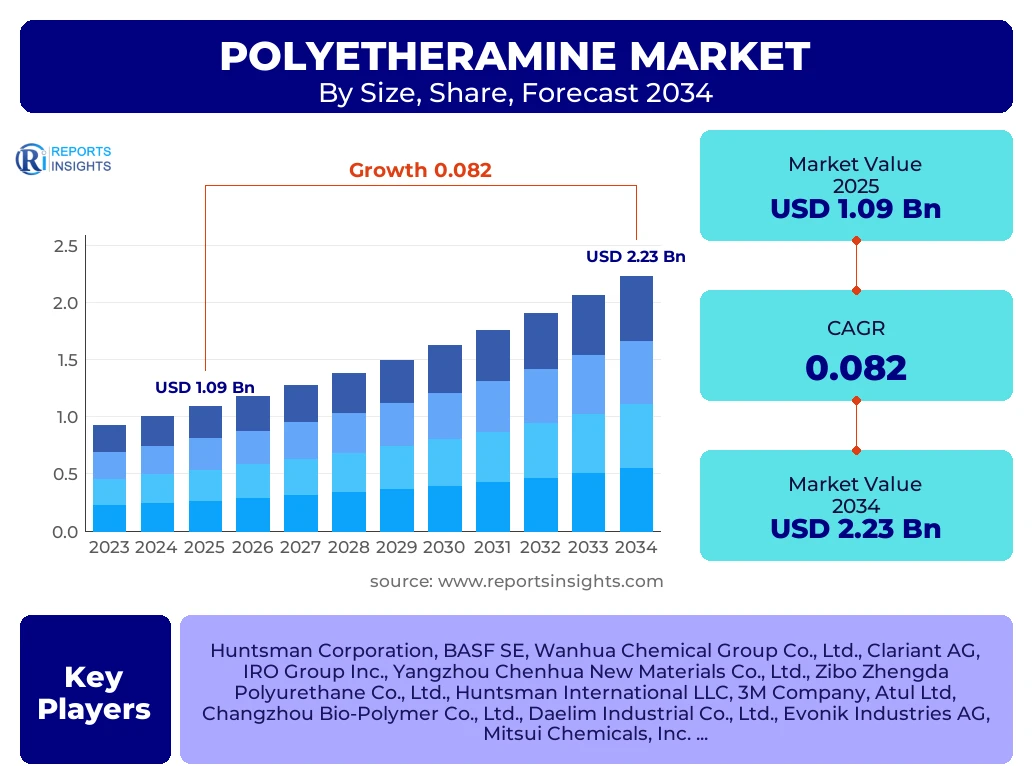
According to Reports Insights Consulting Pvt Ltd, The Polyetheramine Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.2% between 2025 and 2034. The market is estimated at USD 1.18 Billion in 2026 and is projected to reach USD 2.23 Billion by the end of the forecast period in 2034.
Key Polyetheramine Market Trends & Insights
The global demand for polyetheramines is undergoing a significant transformation driven by the escalating transition toward renewable energy and high-performance industrial coatings. Market intelligence indicates that the integration of polyetheramines in wind turbine blade manufacturing remains the primary catalyst for volume growth, particularly as offshore wind projects scale in capacity. Simultaneously, the automotive sector is increasingly adopting these chemicals for lightweighting through advanced epoxy composites and fuel additives. Competitive benchmarking reveals a strategic shift among leading manufacturers toward specialized, low-viscosity diamines and triamines that offer superior thermal stability and moisture resistance in extreme environments.
- Asia Pacific remains the largest and fastest-growing regional market, underpinned by massive infrastructure spending and chemical manufacturing hubs in China and India.
- The Epoxy Resin Curing Agent segment holds the largest market share, driven by demand in the construction and aerospace industries.
- Polyurea coatings are emerging as the fastest-growing application segment due to their rapid curing properties and durability in waterproofing applications.
- Increased focus on bio-based polyetheramine variants is becoming a key trend as companies align with global sustainability and decarbonization mandates.
Key Takeaways Polyetheramine Market Size & Forecast
The polyetheramine market is characterized by a concentrated competitive landscape where technological innovation in molecular weight distribution and amine functionality determines market leadership. Analysts observe that the forecast period will see a stabilization of raw material costs, such as propylene oxide and ammonia, which will likely improve profit margins for primary producers. The surge in electric vehicle (EV) production globally necessitates advanced battery housing materials where polyetheramines play a crucial role in structural adhesives. Furthermore, the expansion of the construction sector in the Middle East and Southeast Asia provides a robust pipeline for polyurea-based protective coatings.
- China is the leading country in both production capacity and domestic consumption, accounting for over 35% of the global market share.
- The Wind Energy sector is the single most influential end-user, with a high correlation between global wind capacity additions and polyetheramine demand.
- Technological advancements in "cool-curing" polyetheramines are opening new opportunities in temperature-sensitive manufacturing environments.
- Strategic mergers and long-term supply agreements between amine producers and epoxy formulators are stabilizing the value chain.
Polyetheramine Market Drivers Analysis
The primary growth engines for the polyetheramine market are rooted in the global shift toward sustainable infrastructure and advanced material science. As nations commit to net-zero targets, the wind energy sector has emerged as a voracious consumer of polyetheramines, which are essential for the production of durable, long-span composite blades. Additionally, the rapid urbanization in emerging economies is driving the demand for high-performance adhesives and sealants in the construction industry, where polyetheramines offer unmatched flexibility and chemical resistance.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Wind Energy Expansion (Blade Composites) | +3.1% | Global (Strong in China & EU) | 2025 - 2034 |
| Automotive Lightweighting & EV Adhesives | +2.4% | Germany, USA, Japan | 2026 - 2034 |
| Demand for Polyurea Waterproofing in Infrastructure | +1.8% | India, UAE, Saudi Arabia | 2025 - 2030 |
Polyetheramine Market Restraints Analysis
Despite robust growth prospects, the market faces headwinds from the volatility of petrochemical feedstock prices. The production of polyetheramines is highly dependent on the availability and pricing of propylene oxide and ethylene oxide, which are subject to global energy market fluctuations. Furthermore, stringent environmental regulations regarding the handling and disposal of specialty chemicals in the European Union and North America impose additional compliance costs on manufacturers, potentially slowing down the adoption in cost-sensitive applications.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility (Propylene Oxide) | -1.5% | Global | Short to Medium Term |
| Strict Environmental & REACH Regulations | -0.9% | Europe (EU), North America | 2025 - 2034 |
Polyetheramine Market Opportunities Analysis
Opportunities in the polyetheramine sector are increasingly found in the development of niche applications and the exploration of green chemistry. The rise of 3D printing and additive manufacturing using epoxy-based resins presents a nascent but high-value opportunity for specialized amines. Moreover, the aging infrastructure in developed nations necessitates large-scale rehabilitation projects where polyurea coatings can provide rapid, long-lasting solutions, offering a significant growth runway for regional distributors and service providers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based Polyetheramines | +1.4% | Western Europe, North America | 2028 - 2034 |
| Infrastructure Retrofitting in North America | +1.2% | USA, Canada | 2025 - 2032 |
| Emergence of Advanced 3D Printing Resins | +0.7% | South Korea, Japan, Taiwan | 2027 - 2034 |
Polyetheramine Market Challenges Impact Analysis
The industry must navigate complex technical and logistical challenges, including the need for highly specialized storage and transport conditions to maintain product purity. Technical challenges also involve the formulation complexities when substituting traditional amines with polyetheramines in established industrial processes. Additionally, the geopolitical landscape and trade barriers can disrupt the supply of critical precursors, forcing manufacturers to diversify their sourcing strategies and invest in localized production facilities to mitigate risk.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Technical Formulation Complexities | -0.6% | Global | 2025 - 2034 |
| Geopolitical Supply Chain Disruptions | -1.1% | Asia Pacific, Middle East | 2025 - 2028 |
Polyetheramine Market - Updated Report Scope
This report provides a comprehensive architectural analysis of the global polyetheramine market, encompassing historical data, current valuation, and multi-decade forecasts. It evaluates the technical specifications of monoamines, diamines, and triamines across diverse industrial verticals. The scope extends to a deep dive into the regulatory environment, competitive positioning of the top 20 global entities, and a granular regional assessment to provide stakeholders with actionable strategic intelligence.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.09 Billion |
| Market Forecast in 2034 | USD 2.23 Billion |
| Growth Rate | 8.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Huntsman Corporation, BASF SE, Wanhua Chemical Group Co., Ltd., Clariant AG, IRO Group Inc., Yangzhou Chenhua New Materials Co., Ltd., Zibo Zhengda Polyurethane Co., Ltd., Huntsman International LLC, 3M Company, Atul Ltd, Changzhou Bio-Polymer Co., Ltd., Daelim Industrial Co., Ltd., Evonik Industries AG, Mitsui Chemicals, Inc., Yantai Minsheng Chemicals Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The polyetheramine market is segmented based on molecular structure and industrial utility, reflecting the diverse chemical requirements of modern manufacturing. The diamine segment continues to dominate the market due to its versatility in curing epoxy resins and its critical role in the synthesis of polyurea. Triamines are witnessing increased uptake in applications requiring higher cross-linking density, such as specialized aerospace components and high-strength industrial flooring. Fuel additives represent a mature yet stable segment, where polyetheramines are utilized to improve engine performance and reduce emissions.
- By Type:
- Monoamine: Primarily used in fuel additives and specialized chemical intermediates.
- Diamine: The largest segment, essential for epoxy curing and polyurea elastomers.
- Triamine: Used for high-performance applications requiring superior structural integrity.
- By Application:
- Epoxy Resin: Dominant application in composites and protective coatings.
- Polyurea: Rapidly growing segment for waterproofing and heavy-duty liners.
- Fuel Additives: Vital for internal combustion engine efficiency.
- Adhesives & Sealants: Expanding use in automotive and construction sectors.
- By End-User:
- Wind Energy: Leading consumer for wind blade manufacturing.
- Construction: Key for flooring, roofing, and structural repairs.
- Automotive: Focus on lightweighting and structural bonding.
- Aerospace: High-value segment for composite materials.
Regional Highlights
- Asia Pacific: Holds the largest market share (approx. 42%) and is the fastest-growing region. Growth is driven by China's dominance in wind turbine manufacturing and India's burgeoning infrastructure sector.
- North America: A mature market focused on high-tech applications in aerospace and automotive. The U.S. is a major hub for polyetheramine innovation and fuel additive consumption.
- Europe: Driven by strict environmental regulations and a strong emphasis on renewable energy. Germany and Denmark are key players in wind energy technology utilizing polyetheramines.
- Middle East & Africa: Represents a significant growth opportunity for polyurea coatings in oil and gas infrastructure and desalination plants.
- Latin America: Emerging demand in Brazil and Mexico for automotive manufacturing and industrial construction.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Polyetheramine Market.- Huntsman Corporation
- BASF SE
- Wanhua Chemical Group Co., Ltd.
- Clariant AG
- IRO Group Inc.
- Yangzhou Chenhua New Materials Co., Ltd.
- Zibo Zhengda Polyurethane Co., Ltd.
- Huntsman International LLC
- 3M Company
- Atul Ltd
- Changzhou Bio-Polymer Co., Ltd.
- Daelim Industrial Co., Ltd.
- Evonik Industries AG
- Mitsui Chemicals, Inc.
- Yantai Minsheng Chemicals Co., Ltd.
- Manali Petrochemicals Limited
- Zibo Dexin Lianbang Chemical Industry Co., Ltd.
Frequently Asked Questions
What is the primary driver for the Polyetheramine market growth through 2034?
The primary driver is the global expansion of the wind energy sector, where polyetheramines are essential for manufacturing high-performance composite wind turbine blades, alongside the increasing demand for polyurea coatings in infrastructure.
Which region currently dominates the Polyetheramine market share?
Asia Pacific currently dominates the market, accounting for over 40% of the total share, driven by large-scale industrialization, infrastructure development, and a strong manufacturing base in China and India.
How are polyetheramines used in the automotive industry?
In the automotive sector, polyetheramines are used as fuel additives to improve engine performance and as key components in structural adhesives and lightweight epoxy composites for electric vehicles.
What are the different types of Polyetheramines available in the market?
The market is categorized into Monoamines, Diamines, and Triamines, with Diamines being the most widely used due to their versatility in epoxy curing and polyurea synthesis.
What challenges do manufacturers face in this market?
Manufacturers face challenges such as the volatility of raw material prices (like propylene oxide), stringent environmental regulations, and the technical complexity of formulating products for niche high-performance applications.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
