Plastic Decking Market
Plastic Decking Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711459 | Published On : November 02, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Plastic Decking Market Size
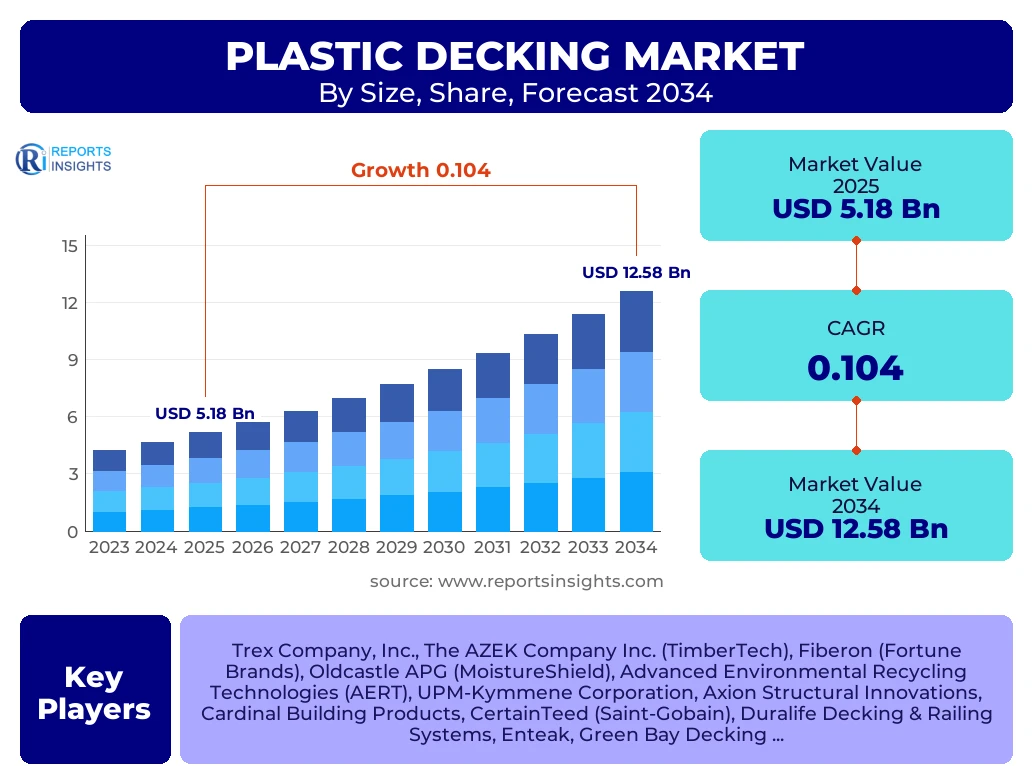
According to Reports Insights Consulting Pvt Ltd, The Plastic Decking Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 10.4% between 2025 and 2034. The market is estimated at USD 5.72 Billion in 2026 and is projected to reach USD 12.58 Billion by the end of the forecast period in 2034.
Key Plastic Decking Market Trends & Insights
The global plastic decking market is undergoing a significant transformation driven by the convergence of sustainable manufacturing and the rising consumer preference for high-performance outdoor living spaces. As homeowners and commercial developers pivot away from traditional timber due to its intensive maintenance requirements and susceptibility to environmental degradation, advanced polymer-based decking solutions have emerged as the primary alternative. Regional analysis indicates that while North America remains the structural backbone of the industry, the Asia-Pacific region is witnessing unprecedented acceleration fueled by rapid urbanization and the expansion of the hospitality sector. Competitive benchmarking reveals that market leaders are increasingly differentiating themselves through "capped" polymer technology, which provides superior resistance to UV radiation, moisture, and staining compared to first-generation uncapped products. Furthermore, the integration of circular economy principles, where post-consumer plastic waste is upcycled into premium construction materials, has become a core strategic pillar for leading manufacturers.
- Largest Region: North America remains the dominant market by value, accounting for over 45% of the global share, primarily due to the established outdoor living culture in the United States and Canada.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period, driven by infrastructure development in China, India, and Southeast Asia.
- Leading Material Segment: High-Density Polyethylene (HDPE) represents the largest material segment, valued for its durability and compatibility with recycled feedstocks.
- Dominant Application: The Residential sector continues to hold the majority of the market share as home renovation and improvement projects remain resilient.
- Technology Trend: Capped Composite and Capped Polymer decking are rapidly replacing uncapped variants due to enhanced aesthetic longevity and warranty protections.
Key Takeaways Plastic Decking Market Size & Forecast
The forecast period from 2025 to 2034 suggests a decade of robust expansion, characterized by a shift toward premiumization and eco-conscious consumption. Market size projections are supported by a steady increase in the replacement cycle of aging wood decks with long-lasting plastic alternatives. Stakeholders are focusing on the total cost of ownership (TCO) as a primary selling point, highlighting that while plastic decking requires a higher upfront investment, the absence of sanding, staining, and sealing costs provides a superior internal rate of return over a 20-year period. The market is also benefiting from advancements in extrusion technology, allowing for more realistic wood-grain textures and variegated coloring that mimics exotic hardwoods, thereby capturing the high-end architectural segment.
- Projected Value: The market is set to surpass the USD 12 billion mark by 2034, doubling its current footprint within the decade.
- Market Driver: The "Nesting" trend, where consumers prioritize home-based recreation, is a permanent structural driver for the residential decking market.
- Regional Leader: The United States is the single largest country-level market, supported by a mature distribution network of big-box retailers and specialized contractors.
- Material Evolution: PVC decking is gaining traction in coastal regions due to its superior moisture resistance and heat-dissipation properties compared to standard composites.
- Sustainability Impact: Increased regulatory pressure on forest conservation is indirectly boosting the demand for synthetic decking solutions globally.
Plastic Decking Market Drivers Analysis
The primary catalysts for the plastic decking market include the escalating demand for low-maintenance building materials and the global surge in residential remodeling activities. As leisure time becomes more valued, consumers are increasingly unwilling to perform the annual maintenance required by natural wood. Additionally, the rising awareness of environmental sustainability is driving the adoption of products made from recycled plastics, such as detergent bottles and plastic bags, which are major components of modern plastic decking. The growth of the global real estate sector and the trend toward "outdoor rooms"—which treat decks as functional extensions of the indoor living area—further solidify the market's upward trajectory.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rise in Residential Renovation and Remodeling | +3.2% | North America & Western Europe | 2025–2034 |
| Shift Toward Low-Maintenance Materials | +2.8% | Global | 2025–2030 |
| Advancements in Recycled Material Processing | +1.5% | Developed Economies | 2026–2034 |
| Expansion of Commercial Outdoor Spaces | +1.2% | Asia-Pacific & Middle East | 2027–2034 |
Plastic Decking Market Restraints Analysis
Despite the positive growth outlook, the market faces restraints such as high initial installation costs and sensitivity to raw material price fluctuations. Plastic decking can be two to three times more expensive than pressure-treated lumber, which remains a barrier for budget-conscious consumers, particularly in developing regions. Furthermore, the industry is highly dependent on the petrochemical sector for virgin polymers and the stability of global recycling supply chains, both of which are subject to volatility due to geopolitical tensions and energy price swings.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Upfront Investment | -1.8% | Emerging Markets | 2025–2034 |
| Volatility in Petrochemical Feedstock Prices | -1.2% | Global | 2025–2028 |
| Competition from Sustainably Sourced Timber | -0.5% | Northern Europe & Canada | 2026–2034 |
Plastic Decking Market Opportunities Analysis
Significant opportunities lie in the development of "Cool Deck" technology, which addresses the historical challenge of plastic boards retaining excessive heat in direct sunlight. Innovation in thermal-reflective pigments is opening doors in hotter climates like the Southern United States, Australia, and the Middle East. Additionally, the expansion of e-commerce distribution channels for bulky building materials and the integration of modular, "DIY-friendly" decking systems represent untapped potential for reaching a broader consumer base that prefers self-installation over professional contracting.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Heat-Resistant Technology Innovation | +2.1% | Australia, GCC Countries, Southern US | 2026–2034 |
| Modular & DIY Decking Kits | +1.4% | Europe & North America | 2025–2030 |
| Growth in Hospitality and Tourism Infrastructure | +1.7% | Southeast Asia & Latin America | 2027–2034 |
Plastic Decking Market Challenges Impact Analysis
The plastic decking industry must navigate challenges related to regulatory compliance and product standardization. As the market expands, different regions are implementing stricter fire safety codes for building materials used in wildland-urban interfaces. Ensuring that plastic decking meets high-level fire resistance ratings (such as Class A) without compromising structural integrity or aesthetic appeal is a technical hurdle. Additionally, managing the end-of-life disposal or recycling of composite materials remains a challenge, as the multi-material nature of some products makes them difficult to re-process compared to pure polymers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stricter Fire Safety Regulations | -0.9% | California (US), Australia, EU | 2025–2034 |
| Complex End-of-Life Recycling Processes | -0.6% | Western Europe | 2028–2034 |
| Counterfeit and Low-Quality Imports | -0.4% | Global | 2025–2034 |
Plastic Decking Market - Updated Report Scope
This comprehensive report provides a granular analysis of the global plastic decking landscape, covering technological advancements, competitive dynamics, and regulatory influences across five major geographic regions. The scope includes a detailed breakdown of material types, including polyethylene, polypropylene, and polyvinyl chloride, alongside an evaluation of construction types from solid to hollow boards. The study integrates historical data from 2020 to 2024 to provide a contextually grounded forecast through 2034, ensuring that stakeholders can identify long-term structural shifts versus short-term market noise.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.18 Billion |
| Market Forecast in 2034 | USD 12.58 Billion |
| Growth Rate | 10.4% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Trex Company, Inc., The AZEK Company Inc. (TimberTech), Fiberon (Fortune Brands), Oldcastle APG (MoistureShield), Advanced Environmental Recycling Technologies (AERT), UPM-Kymmene Corporation, Axion Structural Innovations, Cardinal Building Products, CertainTeed (Saint-Gobain), Duralife Decking & Railing Systems, Enteak, Green Bay Decking, Integrity Composites LLC, NewTechWood, Tamko Building Products, Thermory AS, Universal Forest Products, Inc., WPC Decking, Xi'an MexyTech Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The plastic decking market is segmented primarily by material, product type, and application, with material science playing the most critical role in defining market value. HDPE remains the dominant material due to its balance of cost, strength, and environmental profile. PVC is the preferred choice for premium applications requiring high fire resistance and low heat retention. The shift from uncapped to capped decking represents the most significant movement in product types, as the protective polymer shell used in capped products virtually eliminates fading and mold issues. In terms of application, while residential renovation continues to drive the volume, the commercial sector is expanding rapidly as municipalities recognize the long-term maintenance savings of using plastic composites for public boardwalks and park infrastructure.
- Material Segmentation:
- High-Density Polyethylene (HDPE): Leading segment due to high recycled content and durability.
- Polyvinyl Chloride (PVC): High-growth segment preferred for luxury residential and marine environments.
- Polypropylene (PP): Growing use in specialized industrial and commercial decking.
- Low-Density Polyethylene (LDPE) and Others: Used primarily in budget-friendly or blended composite options.
- Type Segmentation:
- Capped Plastic Decking: The industry standard for modern installations, offering a protective outer layer.
- Uncapped Plastic Decking: Declining share, used mostly in cost-sensitive or temporary structures.
- Application Segmentation:
- Residential: Includes single-family homes and multi-family housing complexes.
- Commercial: Includes hotels, resorts, office buildings, and public infrastructure projects.
- Industrial: Specialized applications in manufacturing facilities and shipping areas.
Regional Highlights
North America is the global leader in the plastic decking market, supported by a vast existing housing stock and a strong cultural emphasis on outdoor living. The United States specifically benefits from a highly developed distribution network and the presence of the industry's largest manufacturers. In Europe, the market is driven by stringent environmental regulations and a high demand for sustainable building materials in countries like Germany, France, and the UK. The Asia-Pacific region, however, is the fastest-growing market, with China and India leading the way through massive urban development and a burgeoning middle class that is increasingly investing in home aesthetics. The Middle East is also emerging as a niche market for high-end, heat-resistant plastic decking used in luxury tourism projects.
- North America: Holds the largest market share (45%+) with the US being the primary revenue generator.
- Europe: Leading the market in the adoption of circular economy principles and bio-based plastic blends.
- Asia-Pacific: Forecasted to grow at a CAGR exceeding 12%, driven by infrastructure and commercial development.
- Latin America: Growing interest in the hospitality sector, specifically in coastal regions of Brazil and Mexico.
- Middle East & Africa: Demand is focused on high-performance materials capable of withstanding extreme UV and temperature fluctuations.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Plastic Decking Market.- Trex Company, Inc.
- The AZEK Company Inc. (TimberTech)
- Fiberon (Fortune Brands Innovations)
- Oldcastle APG (MoistureShield)
- Advanced Environmental Recycling Technologies (AERT)
- UPM-Kymmene Corporation
- Axion Structural Innovations
- CertainTeed (Saint-Gobain)
- Duralife Decking & Railing Systems
- NewTechWood
- Universal Forest Products, Inc. (UFPI)
- Tamko Building Products
- Cardinal Building Products
- Green Bay Decking
- Thermory AS
- Xi'an MexyTech Co., Ltd.
- Integrity Composites LLC
- Eva-Last
- WPC Decking
- Enteak
Frequently Asked Questions
What is the expected growth rate of the plastic decking market through 2034?
The plastic decking market is projected to grow at a CAGR of 10.4% from 2025 to 2034, driven by the increasing demand for sustainable and low-maintenance outdoor building materials.
Which material is most commonly used in plastic decking?
High-Density Polyethylene (HDPE) is the most widely used material due to its excellent durability, moisture resistance, and its ability to incorporate high percentages of recycled content.
How does plastic decking compare to traditional wood in terms of cost?
While plastic decking has a higher initial purchase and installation price, its long-term cost is significantly lower than wood because it eliminates the need for regular staining, sealing, and repair.
Which region currently leads the global plastic decking market?
North America currently leads the market, accounting for nearly half of the global share, supported by a mature home improvement sector and strong consumer preference for outdoor living spaces.
What is the difference between capped and uncapped plastic decking?
Capped decking features an extra protective polymer layer that provides superior resistance to fading, scratching, and mold, whereas uncapped decking is more prone to environmental wear over time.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
