Phosphate Esters Market
Phosphate Esters Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711376 | Published On : October 30, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Phosphate Esters Market Size
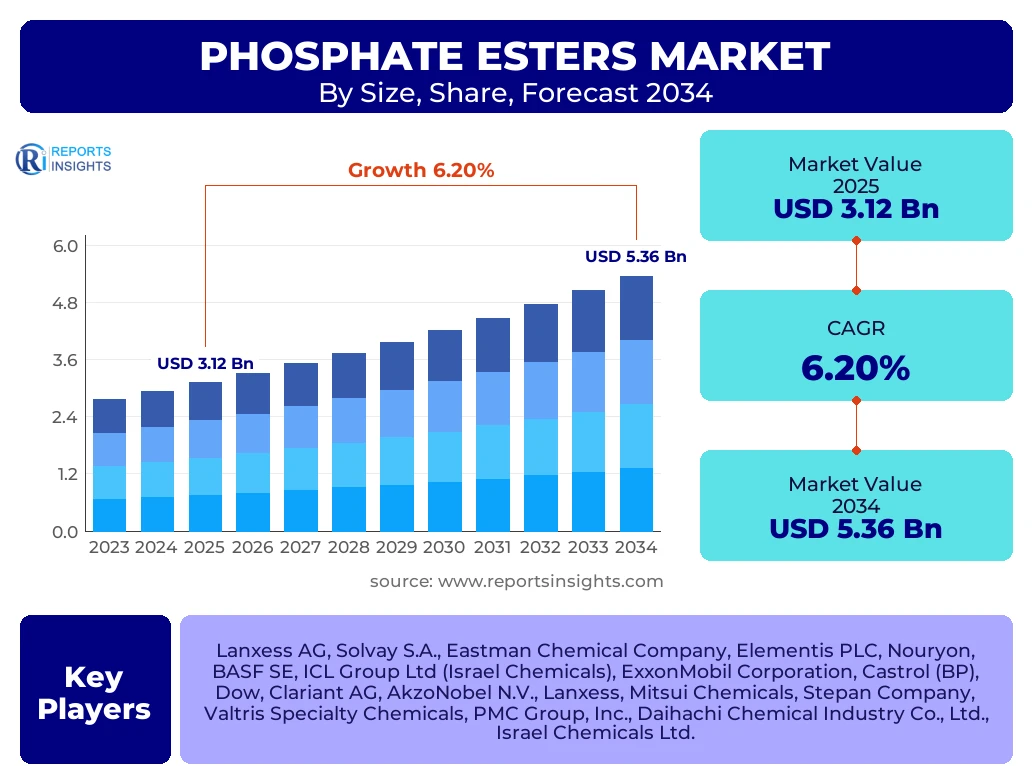
According to Reports Insights Consulting Pvt Ltd, The Phosphate Esters Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 3.31 Billion in 2026 and is projected to reach USD 5.36 Billion by the end of the forecast period in 2034.
Key Phosphate Esters Market Trends & Insights
The global Phosphate Esters market is undergoing a significant transformation driven by the escalating demand for fire-resistant materials and high-performance industrial lubricants. Market participants are increasingly focusing on the development of halogen-free flame retardants to comply with stringent environmental regulations such as REACH and the EPA’s toxic substances control initiatives. Furthermore, the integration of phosphate esters in the formulation of eco-friendly surfactants and agricultural chemicals is emerging as a dominant trend, particularly in emerging economies where industrialization is accelerating. Competitive benchmarking reveals that leading players are investing heavily in R&D to enhance the hydrolytic stability and thermal resistance of their ester products, ensuring they meet the rigorous requirements of the aerospace and automotive sectors.
- Asia-Pacific is the largest and fastest-growing regional market, accounting for over 40% of the total value share due to rapid infrastructure development.
- The Flame Retardants segment remains the largest application category, driven by strict building safety codes and electronics manufacturing.
- Triaryl Phosphate Esters represent the largest product segment in terms of market share, utilized extensively in hydraulic fluids and plasticizers.
- Increasing adoption of electric vehicles (EVs) is fostering a new trend in the demand for specialized dielectric fluids and heat transfer esters.
Key Takeaways Phosphate Esters Market Size & Forecast
The market forecast indicates a robust upward trajectory supported by the recovery of the global construction sector and the expansion of the automotive industry. Strategic shifts toward sustainable chemical production and the replacement of traditional phthalate plasticizers with phosphorus-based alternatives are shaping the long-term outlook. Analysts observe that while raw material price volatility remains a concern, the technological shift toward multi-functional esters—those serving both as plasticizers and flame retardants—is providing a significant competitive edge to diversified chemical manufacturers.
- China and India are identified as the primary growth engines, collectively contributing to the majority of the incremental volume demand through 2034.
- The shift from chlorinated to non-chlorinated phosphate esters is a critical market pivot, driven by consumer safety concerns and ecological protection laws.
- Industrial lubricants and hydraulic fluids are expected to see a CAGR of 5.8%, bolstered by the modernization of manufacturing plants in North America and Europe.
- Market consolidation is anticipated as top-tier companies engage in strategic acquisitions to secure raw phosphorus supply chains and expand their specialty chemical portfolios.
Phosphate Esters Market Drivers Analysis
The primary catalyst for the Phosphate Esters market is the global intensification of fire safety regulations across the construction and transportation industries. As urban density increases, the demand for fire-resistant polymers and interior materials has surged, positioning phosphate esters as a preferred non-halogenated flame retardant solution. Additionally, the increasing complexity of industrial machinery requires advanced lubrication systems that offer high-pressure performance and fire resistance, which are inherent properties of synthetic phosphate ester fluids.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Fire Safety Regulations in Building Codes | +2.1% | North America and European Union | 2025 - 2034 |
| Expansion of the Global Agrochemical Sector | +1.4% | Brazil, India, and China | 2026 - 2030 |
| Rising Demand for Halogen-Free Flame Retardants | +1.8% | Global | 2025 - 2034 |
| Automotive Lightweighting and EV Battery Safety | +0.9% | Germany, Japan, and USA | 2027 - 2034 |
Phosphate Esters Market Restraints Analysis
Despite the positive growth outlook, the market faces headwinds from the inherent toxicity associated with certain triaryl phosphate esters, leading to increased regulatory scrutiny. Furthermore, the high cost of production compared to conventional petroleum-based lubricants and plasticizers often limits market penetration in price-sensitive regions. The volatility of phosphoric acid prices, a key precursor, also introduces margin risks for manufacturers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Environmental Concerns and REACH Regulations | -1.2% | European Union | 2025 - 2034 |
| Volatile Raw Material (Phosphorus) Pricing | -0.8% | Global | 2025 - 2028 |
| Competition from Bio-based Plasticizers | -0.5% | North America | 2028 - 2034 |
Phosphate Esters Market Opportunities Analysis
The development of bio-derived phosphate esters presents a massive opportunity for manufacturers seeking to align with the global "Green Chemistry" movement. There is also a burgeoning opportunity in the electronics sector, where the miniaturization of components necessitates materials with superior thermal stability and dielectric properties. Emerging economies in Southeast Asia offer untapped potential for expansion in the surfactant and textile processing sub-sectors.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| R&D in Bio-Based Phosphate Ester Formulations | +1.5% | Western Europe and USA | 2026 - 2034 |
| Infrastructure Growth in ASEAN Countries | +1.2% | Vietnam, Indonesia, and Thailand | 2025 - 2032 |
| Application in EV Dielectric Cooling Fluids | +1.0% | South Korea and China | 2027 - 2034 |
Phosphate Esters Market Challenges Impact Analysis
Navigating the complex global regulatory landscape remains the most significant challenge for market participants. The disposal and recyclability of products containing phosphate esters are under constant review by environmental agencies. Additionally, the technical challenge of maintaining hydrolytic stability in humid environments for certain ester types requires continuous innovation and adds to the overall cost of the final formulation.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Managing Hydrolytic Stability in Tropical Climates | -0.6% | South Asia and Latin America | 2025 - 2034 |
| Logistical Constraints in Phosphorus Supply Chain | -0.4% | Africa and Middle East | 2025 - 2027 |
Phosphate Esters Market - Updated Report Scope
This comprehensive market research report provides a granular analysis of the global Phosphate Esters industry, encompassing historical data from 2020 and offering projections through 2034. The scope includes a detailed breakdown of product types, application areas, and end-user industries across six major geographic regions. The report evaluates the competitive landscape, examining the market share, strategic initiatives, and technological advancements of the leading industry participants to provide a holistic view of the market's future trajectory.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3.12 Billion |
| Market Forecast in 2034 | USD 5.36 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Lanxess AG, Solvay S.A., Eastman Chemical Company, Elementis PLC, Nouryon, BASF SE, ICL Group Ltd (Israel Chemicals), ExxonMobil Corporation, Castrol (BP), Dow, Clariant AG, AkzoNobel N.V., Lanxess, Mitsui Chemicals, Stepan Company, Valtris Specialty Chemicals, PMC Group, Inc., Daihachi Chemical Industry Co., Ltd., Israel Chemicals Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Phosphate Esters market is segmented by type, application, and end-use industry, reflecting the diverse utility of these chemical compounds. The Triaryl Phosphate segment dominates the market due to its widespread use in large-volume applications such as fire-resistant hydraulic fluids. Meanwhile, the Trialkyl segment is witnessing rapid growth in the surfactant industry because of its excellent emulsifying properties. Application-wise, the flame retardant segment leads in terms of value, while the lubricant segment is experiencing significant growth due to the expansion of the aerospace and heavy machinery sectors.
- By Type:
- Triaryl Phosphate Esters
- Trialkyl Phosphate Esters
- Alkyl-Aryl Phosphate Esters
- Chlorinated Phosphate Esters
- By Application:
- Flame Retardants (Largest Application)
- Lubricants & Hydraulic Fluids
- Surfactants
- Plasticizers
- Pesticides & Agricultural Chemicals
- Others (Textile Finishes, Antifoaming Agents)
- By End-Use:
- Building & Construction
- Automotive & Transportation
- Electronics & Electrical Appliances
- Agriculture
- Industrial Machinery
- Pulp & Paper
Regional Highlights
- Asia-Pacific: The largest and fastest-growing region, driven by China’s massive manufacturing base and India’s burgeoning construction sector. The region accounts for a significant portion of global demand for flame-retardant polymers and agrochemicals.
- North America: A mature market focused on high-performance industrial lubricants and stringent fire safety standards in the aerospace industry. The U.S. remains a key hub for innovation in halogen-free ester technologies.
- Europe: Characterized by intense regulatory pressure from the REACH framework, leading to a rapid shift toward eco-friendly and non-toxic phosphate ester varieties. Germany and France are the leading consumers in the automotive sector.
- Latin America: Growth is primarily driven by the agricultural sector in Brazil and Argentina, where phosphate esters are used as surfactants and intermediate chemicals in pesticides.
- Middle East & Africa: Emerging demand from the oil and gas industry for high-pressure hydraulic fluids and fire-resistant lubricants in refinery operations.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Phosphate Esters Market.- Lanxess AG
- Solvay S.A.
- Eastman Chemical Company
- Elementis PLC
- Nouryon
- BASF SE
- ICL Group Ltd (Israel Chemicals)
- ExxonMobil Corporation
- Castrol (BP)
- Dow
- Clariant AG
- AkzoNobel N.V.
- Mitsui Chemicals
- Stepan Company
- Valtris Specialty Chemicals
- PMC Group, Inc.
- Daihachi Chemical Industry Co., Ltd.
- Croda International Plc
- Thor Group
- Suez (Specialty Chemicals Division)
Frequently Asked Questions
What are the primary applications of Phosphate Esters in the modern industry?
Phosphate esters are primarily used as flame retardants in plastics and electronics, high-performance lubricants and hydraulic fluids in aviation and industrial machinery, and as surfactants and plasticizers in various chemical formulations. Their fire-resistant properties make them essential for safety-critical applications.
Why is the market shifting toward halogen-free phosphate esters?
The shift is driven by environmental and health regulations that aim to reduce the toxicity and smoke acidity associated with halogenated flame retardants. Non-halogenated phosphate esters offer a more sustainable profile while maintaining high fire-suppression efficiency.
Which region holds the largest share of the Phosphate Esters market?
The Asia-Pacific region currently holds the largest market share, fueled by the rapid industrialization, infrastructure growth, and the concentration of electronics and automotive manufacturing in China, India, and Japan.
How do phosphate esters contribute to the electric vehicle (EV) industry?
In the EV sector, phosphate esters are used in specialized dielectric cooling fluids and battery housing materials to provide superior thermal management and fire protection, which are critical for the safety and performance of high-energy-density battery systems.
What are the main factors influencing the price of Phosphate Esters?
The price is significantly influenced by the cost of raw phosphorus and phosphoric acid, regulatory compliance costs, and the complexity of the synthetic processes required to produce high-purity specialty esters for aerospace and electronic applications.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
