Phosgene Market
Phosgene Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711647 | Published On : November 10, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Phosgene Market Size
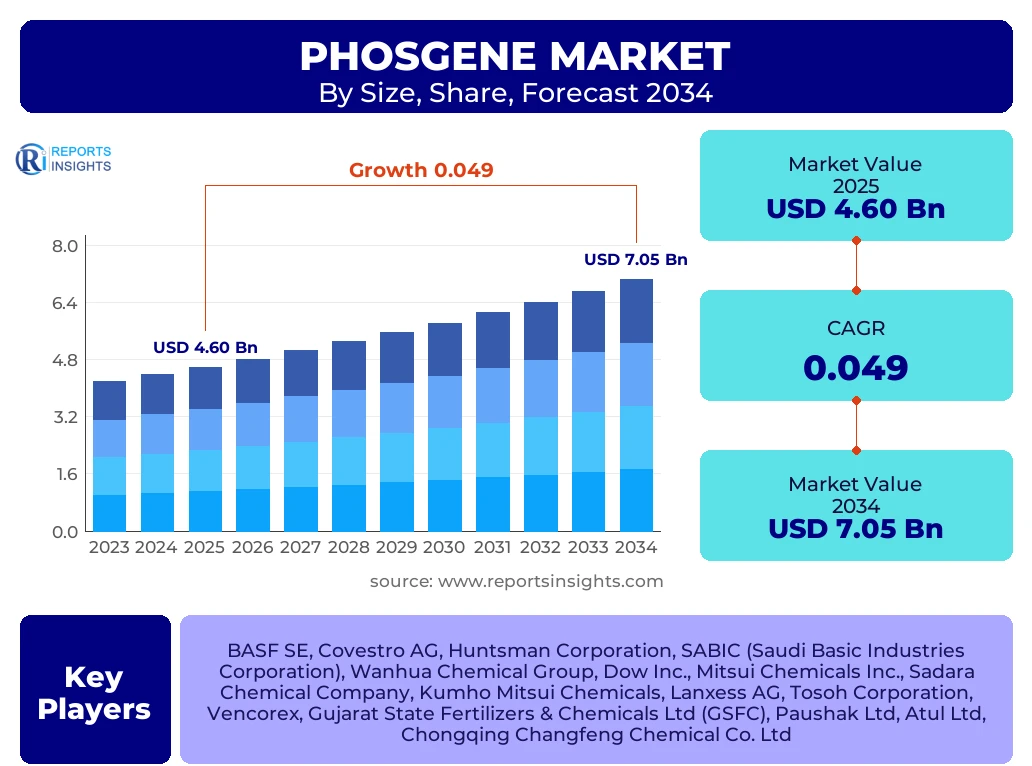
According to Reports Insights Consulting Pvt Ltd, The Phosgene Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.9% between 2025 and 2034. The market is estimated at USD 4.82 Billion in 2026 and is projected to reach USD 7.05 Billion by the end of the forecast period in 2034.
Key Phosgene Market Trends & Insights
The phosgene market is undergoing a significant transformation driven by the shift toward captive production and the tightening of international safety regulations. As a highly toxic chemical intermediate, the logistics of transporting phosgene are prohibitively complex and hazardous, leading major industrial players to integrate phosgene generation units directly within their manufacturing complexes. This trend toward "on-site" production ensures a closed-loop system, minimizing environmental exposure and logistical risks. Furthermore, the rising demand for high-performance plastics, particularly polycarbonates and polyurethanes, remains the primary engine of growth. While non-phosgene routes for polycarbonate production are gaining some traction due to environmental concerns, the cost-efficiency and established infrastructure of phosgene-based synthesis continue to dominate the industrial landscape, especially in emerging economies where infrastructure development is at an all-time high.
- Largest Region: Asia-Pacific, led predominantly by China and India, remains the dominant force in the global phosgene market due to massive industrialization and chemical manufacturing capacity.
- Fastest Growing Region: Asia-Pacific is also the fastest-growing region, fueled by rising automotive production and construction activities in Southeast Asia.
- Largest Segment by Application: The Isocyanates segment, specifically for the production of MDI and TDI, holds the largest market share, accounting for over 60% of total consumption.
- Technological Shift: Increased adoption of digital monitoring systems and automated leak detection in phosgene plants to enhance operational safety and comply with ESG mandates.
Key Takeaways Phosgene Market Size & Forecast
The forecast for the phosgene market remains robust, anchored by its indispensable role as a building block for essential materials in the construction, automotive, and pharmaceutical sectors. Market analysts observe that while the chemical is subject to intense scrutiny under the Chemical Weapons Convention (CWC), its industrial utility is unparalleled. The growth of the global population and the subsequent demand for housing have catalyzed the demand for polyurethane insulation, which is a direct byproduct of phosgene-derived isocyanates. Additionally, the pharmaceutical industry relies on phosgene for the synthesis of complex intermediates used in life-saving medications, ensuring a stable, non-cyclical demand stream that balances the more volatile industrial sectors.
- Dominant Country: China is the leading producer and consumer, driven by its status as the global hub for polyurethane and polycarbonate manufacturing.
- Material Substitution: While non-phosgene processes exist, they currently lack the scale and economic viability to replace phosgene in the production of high-grade MDI.
- Regulatory Influence: Stricter environmental and safety protocols are forcing older plants to modernize, leading to a consolidation of the market among technically advanced players.
- Strategic Integration: Vertical integration is the most critical success factor for companies, as it mitigates the risks associated with raw material supply chains and toxic material handling.
Phosgene Market Drivers Analysis
The growth of the phosgene market is primarily propelled by the escalating demand for high-durability materials in modern infrastructure and the rapid expansion of the global automotive industry. As a precursor to isocyanates and polycarbonates, phosgene is essential for creating lightweight, energy-efficient materials that align with global sustainability goals in building insulation and vehicle weight reduction. The following drivers highlight the specific catalysts for market expansion.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Polyurethane Demand | +1.8% | Global / China / USA | 2025 - 2034 |
| Growth in Polycarbonate for Electronics | +1.2% | South Korea / Japan / China | 2026 - 2030 |
| Pharmaceutical Intermediate Synthesis | +0.9% | Europe / North America | 2025 - 2034 |
| Agrochemical Production Expansion | +1.0% | India / Brazil / USA | 2027 - 2034 |
Phosgene Market Restraints Analysis
The primary restraints acting on the phosgene market are its extreme toxicity and the subsequent regulatory burden placed on manufacturers. Accidental releases can be catastrophic, leading to stringent international oversight and high insurance costs. Furthermore, the push for "green chemistry" has led some manufacturers to seek alternative synthesis routes, which, although currently expensive, pose a long-term threat to phosgene demand.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Safety & Environmental Regulations | -1.1% | European Union (REACH) / USA (EPA) | 2025 - 2034 |
| Development of Non-Phosgene Routes | -0.8% | Japan / Germany | 2028 - 2034 |
| High Capital Investment for On-site Plants | -0.6% | Developing Nations | 2025 - 2030 |
Phosgene Market Opportunities Analysis
Emerging opportunities in the phosgene market are found in the development of safer, micro-reactor technologies that allow for the "just-in-time" production of phosgene in small quantities, reducing the risks of large-scale storage. Additionally, the rising demand for specialized pesticides and herbicides in the agriculture sector provides a significant growth avenue for phosgene-based chemical intermediates.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Micro-reactor Synthesis Technology | +1.4% | Germany / USA / Switzerland | 2026 - 2034 |
| Specialty Agrochemical Demand | +1.1% | Latin America / India | 2025 - 2032 |
| Advanced Polymer Alloys for EVs | +1.3% | China / North America | 2026 - 2034 |
Phosgene Market Challenges Impact Analysis
The market faces significant challenges regarding public perception and the high technical barrier to entry. Managing the supply chain for chlorine and carbon monoxide—the primary precursors—also introduces logistical complexities, especially in regions with fluctuating energy prices or unstable regulatory environments.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Public Perception and Safety Stigma | -0.5% | Global | Ongoing |
| Volatile Precursor (CO & Cl2) Pricing | -0.7% | Europe / Asia | 2025 - 2028 |
Phosgene Market - Updated Report Scope
This report provides a granular analysis of the global phosgene market, encompassing production volumes, consumption patterns, and pricing dynamics across various end-use industries. It evaluates the impact of technological advancements on captive production and provides a detailed forecast of market trends through 2034, focusing on safety, compliance, and industrial demand for high-performance chemical derivatives.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.60 Billion |
| Market Forecast in 2034 | USD 7.05 Billion |
| Growth Rate | 4.9% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Covestro AG, Huntsman Corporation, SABIC (Saudi Basic Industries Corporation), Wanhua Chemical Group, Dow Inc., Mitsui Chemicals Inc., Sadara Chemical Company, Kumho Mitsui Chemicals, Lanxess AG, Tosoh Corporation, Vencorex, Gujarat State Fertilizers & Chemicals Ltd (GSFC), Paushak Ltd, Atul Ltd, Chongqing Changfeng Chemical Co. Ltd |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The phosgene market is segmented primarily by its chemical derivatives, which define its ultimate industrial utility. Isocyanates represent the most significant segment, as they are the primary precursors for polyurethanes used in everything from mattress foam to high-performance building insulation. Polycarbonates follow closely, serving as essential materials for the electronics and automotive sectors due to their transparency and impact resistance. The market is also segmented by application, where the plastics and polymer industry remains the largest consumer, followed by agriculture, where phosgene-based carbamates are used in the production of herbicides and insecticides. The pharmaceutical sector, though smaller in volume, represents a high-value segment where phosgene is used for synthesizing complex active pharmaceutical ingredients (APIs).
- Isocyanates: Includes MDI (Methylene diphenyl diisocyanate) and TDI (Toluene diisocyanate), primarily used for polyurethane foams and coatings.
- Polycarbonates: Used in optical discs, electronic components, and automotive glazing.
- Agrochemicals: Essential for the synthesis of specific pesticides and crop protection chemicals.
- Pharmaceuticals: Utilized in the production of chloroformates and other intermediates for drug synthesis.
- Fine Chemicals: Specialized applications in dyes, pigments, and flavorings.
Regional Highlights
- Asia-Pacific: The undisputed leader in the phosgene market, holding over 50% of the global share. China is the primary hub, driven by massive investments in MDI and polycarbonate facilities to support its domestic construction and electronics industries. India is also emerging as a significant player as its chemical sector matures.
- Europe: A mature market characterized by high regulatory standards and a focus on safety. Germany remains the key manufacturing center, with companies like BASF and Covestro leading the way in phosgene production and safety innovation.
- North America: Market growth is driven by the demand for polyurethane in energy-efficient housing and the recovery of the automotive sector. The Gulf Coast of the United States is a critical hub for phosgene-related industrial activity.
- Middle East and Africa: Growing as a strategic hub for downstream chemical production, with Saudi Arabia expanding its capacity in isocyanates and polycarbonates to diversify its industrial base.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Phosgene Market.- BASF SE
- Covestro AG
- Huntsman Corporation
- SABIC (Saudi Basic Industries Corporation)
- Wanhua Chemical Group
- Dow Inc.
- Mitsui Chemicals Inc.
- Sadara Chemical Company
- Kumho Mitsui Chemicals
- Lanxess AG
- Tosoh Corporation
- Vencorex
- Gujarat State Fertilizers & Chemicals Ltd (GSFC)
- Paushak Ltd
- Atul Ltd
- Chongqing Changfeng Chemical Co. Ltd
Frequently Asked Questions
What is the primary industrial use of phosgene?
The primary use of phosgene is as a chemical intermediate in the production of isocyanates (MDI and TDI), which are essential for manufacturing polyurethanes. It is also used extensively in the production of polycarbonates and various agrochemicals and pharmaceuticals.
Why is phosgene mostly produced on-site (captive production)?
Due to its extreme toxicity and the risks associated with transportation, phosgene is typically manufactured on-site at the point of use. This captive production model minimizes the risk of accidental release during transit and complies with stringent safety regulations.
Which region dominates the global phosgene market?
The Asia-Pacific region, particularly China, dominates the global market. This is due to the region's vast chemical manufacturing infrastructure and the high demand for polyurethane and polycarbonate materials in the construction and automotive sectors.
What are the main regulatory challenges facing the phosgene market?
The market faces strict oversight under the Chemical Weapons Convention (CWC) and environmental regulations like REACH in Europe and the EPA in the US. These regulations mandate rigorous safety protocols, leak detection, and reporting requirements for manufacturers.
Are there viable alternatives to phosgene for polycarbonate production?
Yes, non-phosgene routes (such as oxidative carbonylation or transesterification) exist for polycarbonate synthesis. However, while these methods are safer, the phosgene-based interfacial process currently remains more cost-effective and prevalent for high-scale industrial production.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
