Pet Milk Replacers Market
Pet Milk Replacers Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711463 | Published On : November 02, 2026 |
Format : 


 | Author : Hameer Thakur
Pet Milk Replacers Market Size
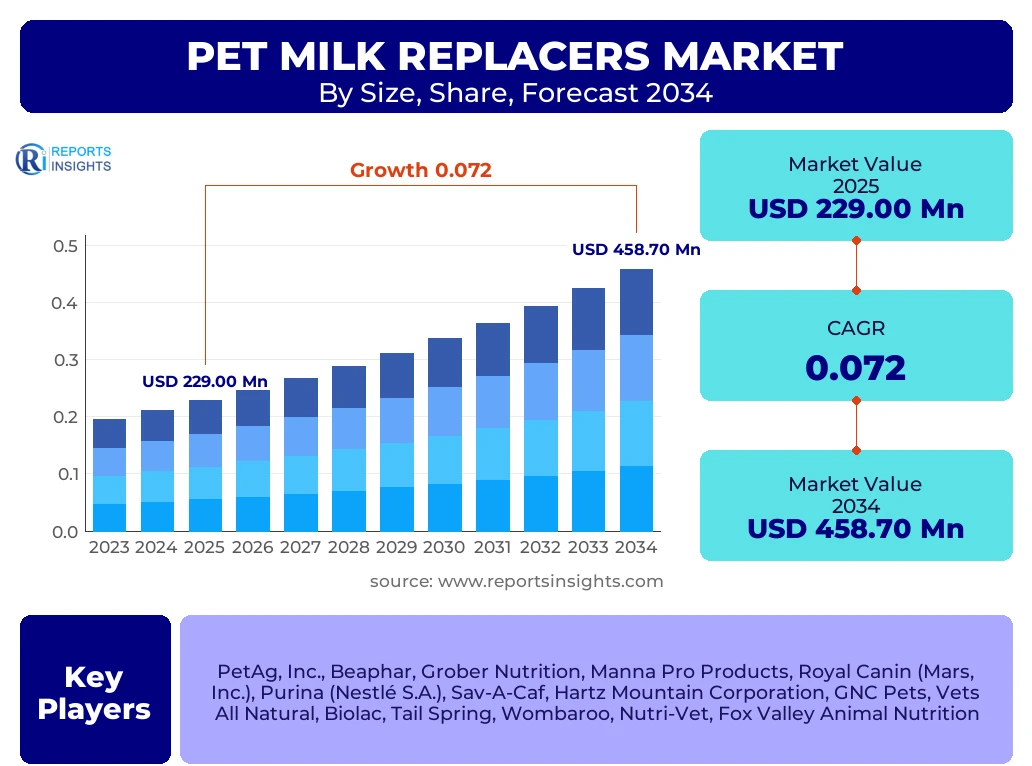
According to Reports Insights Consulting Pvt Ltd, The Pet Milk Replacers Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.2% between 2025 and 2034. The market is estimated at USD 245.50 Million in 2026 and is projected to reach USD 458.70 Million by the end of the forecast period in 2034.
Key Pet Milk Replacers Market Trends & Insights
The global pet milk replacers market is undergoing a significant transformation driven by the macro-trend of pet humanization and the professionalization of pet breeding. Modern pet owners are increasingly viewing their animals as integral family members, leading to a heightened demand for specialized nutritional products that mirror human-grade quality. This shift has catalyzed the development of species-specific formulations that address the unique physiological requirements of neonatal puppies, kittens, and small mammals. The integration of functional ingredients, such as prebiotics, probiotics, and essential fatty acids like DHA, has become a standard in premium segments, as consumers prioritize long-term health outcomes over mere caloric intake. Furthermore, the rise of e-commerce and specialized pet retail platforms has expanded the accessibility of these niche products, allowing manufacturers to reach a global audience with high-potency, shelf-stable powdered and liquid solutions.
- Largest Region: North America remains the dominant market shareholder, supported by high pet ownership rates and a well-established veterinary infrastructure.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR due to rising disposable incomes, urban sprawl, and the rapid adoption of Western pet care standards in China and India.
- Largest Segment by Type: Powdered milk replacers hold the largest market share because of their extended shelf life, cost-effectiveness, and ease of storage for both retail consumers and professional breeders.
- Leading Pet Type: The kitten segment is witnessing robust growth, often outpacing puppies in certain urban markets where cats are preferred for apartment living.
- Key Distribution Trend: Online retail channels are the fastest-growing distribution segment, facilitated by subscription models and the convenience of home delivery for heavy or bulk-purchased pet supplies.
Key Takeaways Pet Milk Replacers Market Size & Forecast
The trajectory of the pet milk replacers market is fundamentally tied to the increasing survival rates of orphaned or rejected neonatal pets and the growing awareness of supplemental feeding benefits. Market analysis indicates that while historical growth was driven primarily by emergency interventions, current demand is being bolstered by proactive nutritional supplementation in large litters and the use of milk replacers as high-protein toppers for aging or convalescing animals. Strategic investments in research and development are focusing on reducing the gastrointestinal distress often associated with bovine-based milk substitutes by incorporating hydrolyzed proteins and lactose-reduced formulations. As the industry moves toward 2034, the focus will likely shift toward sustainable sourcing and clean-label ingredients to satisfy the demands of the eco-conscious pet parent demographic.
- Market Valuation: The total market value is expected to nearly double by 2034, reflecting a stable and resilient demand profile.
- Leading Country: The United States continues to be the primary revenue generator, characterized by a high penetration of premium pet food products and specialized neonatal care services.
- Emerging Opportunity: The development of goat-milk-based replacers is gaining traction as a hypoallergenic and highly digestible alternative to traditional cow-milk formulas.
- Technological Integration: Advanced micro-encapsulation technologies are being utilized to preserve the bioactivity of immunoglobulins and vitamins within the milk powder.
- Strategic Consolidation: Large-scale pet nutrition conglomerates are increasingly acquiring niche milk replacer brands to diversify their specialty care portfolios.
Pet Milk Replacers Market Drivers Analysis
The primary catalyst for market expansion is the escalating rate of pet adoption globally, particularly among younger demographics who prioritize comprehensive animal wellness. Additionally, the advancement of veterinary science has educated pet owners on the critical importance of colostrum-like nutrients during the first weeks of a pet's life, leading to higher adoption of milk replacers for supplemental feeding. The transition from general-purpose animal milk to species-specific formulations ensures better growth trajectories and lower mortality rates in kittens and puppies.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Pet Humanization & Premiumization | +1.8% | Global (Strongest in North America & Europe) | 2025 - 2034 |
| Advancements in Neonatal Veterinary Care | +1.5% | Western Europe, USA, Japan | 2026 - 2030 |
| Expansion of E-commerce Distribution | +1.2% | China, India, Brazil | 2025 - 2034 |
| Increased Awareness of Supplemental Nutrition | +1.1% | Australia, Canada, UK | 2025 - 2032 |
Pet Milk Replacers Market Restraints Analysis
Despite the positive growth outlook, the market faces challenges related to the high cost of specialized premium formulations, which can be a barrier for low-income pet owners. Furthermore, the persistence of traditional, often nutritionally inadequate, homemade milk recipes in rural or developing regions continues to limit the penetration of commercial milk replacers. Regulatory hurdles regarding the fortification of animal feed with certain synthetic vitamins also pose a challenge for global product standardization.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Premium & Specialty Products | -0.8% | Latin America, Southeast Asia | 2025 - 2034 |
| Prevalence of Homemade Alternative Recipes | -0.6% | Rural India, Africa, Parts of Asia | 2025 - 2030 |
| Strict Regulatory Compliance for Additives | -0.4% | European Union, China | 2026 - 2034 |
Pet Milk Replacers Market Opportunities Analysis
The market is ripe for innovation in the plant-based and alternative protein space, catering to pet owners who follow vegan or sustainable lifestyles. There is also a significant opportunity in developing personalized nutrition plans for neonatal pets based on breed-specific growth charts and metabolic needs. Expanding into untapped markets in the Middle East and Africa, where pet ownership is rising among the burgeoning middle class, represents a long-term strategic growth avenue for global manufacturers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Plant-Based/Vegan Replacers | +1.4% | USA, Germany, UK | 2027 - 2034 |
| Personalized & Breed-Specific Nutrition | +1.1% | Global (Niche segments) | 2026 - 2034 |
| Untapped Markets in Emerging Economies | +0.9% | UAE, Saudi Arabia, South Africa | 2028 - 2034 |
Pet Milk Replacers Market Challenges Impact Analysis
Supply chain volatility, particularly regarding the sourcing of high-quality dairy proteins and specialized fats, remains a persistent concern for manufacturers. Additionally, maintaining the delicate balance of micronutrients to prevent developmental issues like nutritional cataracts in kittens requires rigorous quality control and expensive clinical testing. Competitiveness from large-scale general pet food manufacturers entering the specialty milk space also puts pressure on smaller, dedicated brands.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Dairy Ingredient Pricing | -0.7% | Global (Impacts profit margins) | 2025 - 2034 |
| Stringent Clinical Testing Requirements | -0.5% | North America, Europe | 2025 - 2034 |
| Market Saturation in Traditional Segments | -0.3% | USA, Japan | 2030 - 2034 |
Pet Milk Replacers Market - Updated Report Scope
This comprehensive report provides a detailed analysis of the global pet milk replacers industry, covering technical specifications, market dynamics, and competitive landscapes. The scope encompasses various formulations, including powders and liquids, across multiple pet categories and distribution channels. It offers actionable insights for stakeholders looking to navigate the evolving regulatory environment and consumer preferences over the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 229.00 Million |
| Market Forecast in 2034 | USD 458.70 Million |
| Growth Rate | 7.2% CAGR |
| Number of Pages | 258 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | PetAg, Inc., Beaphar, Grober Nutrition, Manna Pro Products, Royal Canin (Mars, Inc.), Purina (Nestlé S.A.), Sav-A-Caf, Hartz Mountain Corporation, GNC Pets, Vets All Natural, Biolac, Tail Spring, Wombaroo, Nutri-Vet, Fox Valley Animal Nutrition |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The pet milk replacers market is segmented to reflect the diverse needs of different animal species and the logistical requirements of various consumer groups. The primary differentiation occurs between powdered and liquid formats, with powder dominating due to its long-term viability and ease of transport. However, the liquid segment is gaining popularity for its convenience and readiness for immediate use, especially in emergency rescue scenarios. Segmentation by pet type reveals that puppies and kittens are the primary consumers, though there is a growing niche for exotic small mammals and equine foals in specific agricultural and hobbyist markets.
- By Product Form:
- Powdered: Preferred for bulk use and shelf stability.
- Liquid: Targeted at consumers seeking convenience and precision in dosage.
- By Pet Category:
- Dogs (Puppies): Largest market by volume due to high adoption rates.
- Cats (Kittens): Fast-growing segment driven by feline popularity in urban areas.
- Others: Includes rabbits, ferrets, hamsters, and foals.
- By Ingredient Source:
- Bovine-based: Traditional and most widely available.
- Goat-milk based: Rising popularity due to high digestibility and low allergenicity.
- Plant-based: Emerging niche for vegan-oriented pet owners.
- By Distribution Channel:
- Veterinary Clinics: Critical for medical-grade and prescription-based formulas.
- Online Platforms: Dominating for repeat purchases and variety.
- Offline Specialty Stores: Important for immediate, physical expert consultation.
Regional Highlights
- North America: Currently the largest market globally, characterized by high spending per pet and a sophisticated retail environment. The United States leads this region with a robust demand for premium, scientifically-backed neonatal nutrition.
- Europe: A mature market with a strong emphasis on regulatory standards and animal welfare. Germany, France, and the UK are key contributors, with a growing trend toward organic and ethically sourced pet milk replacers.
- Asia-Pacific: The fastest-growing region, fueled by the rapid expansion of the middle class in China, India, and Southeast Asia. The increasing cultural shift toward keeping pets as companions rather than working animals is a major growth driver.
- Latin America: Showing steady growth, particularly in Brazil and Mexico, where urban pet ownership is rising alongside improvements in the pet-care retail infrastructure.
- Middle East & Africa: An emerging market with significant potential in urban centers like Dubai and Johannesburg, where high-end pet services are becoming more common.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Pet Milk Replacers Market.- PetAg, Inc.
- Beaphar
- Grober Nutrition
- Manna Pro Products
- Royal Canin (Mars, Inc.)
- Purina (Nestlé S.A.)
- Sav-A-Caf
- Hartz Mountain Corporation
- GNC Pets
- Vets All Natural
- Biolac
- Tail Spring
- Wombaroo
- Nutri-Vet
- Fox Valley Animal Nutrition
- Lambert Kay
- Zalig
- Milk Specialties Global
Frequently Asked Questions
What are the main benefits of pet milk replacers over cow's milk?
Pet milk replacers are formulated to match the specific nutritional profile of a mother pet's milk, which contains higher protein, fat, and essential antibodies. Standard cow's milk often contains too much lactose and insufficient nutrients for puppies or kittens, which can lead to diarrhea, dehydration, and stunted growth.
How long can powdered pet milk replacer be stored?
Generally, unopened powdered milk replacer has a shelf life of 12 to 24 months if stored in a cool, dry place. Once opened, it is recommended to be used within 3 months, or kept in the refrigerator or freezer to extend its freshness and maintain the potency of the vitamins and probiotics.
Which is better: liquid or powdered milk replacer?
Both have advantages. Powdered replacers are more cost-effective and have a longer shelf life, making them ideal for large litters or professional breeders. Liquid replacers offer convenience and eliminate mixing errors, making them excellent for emergency situations or for pet owners who prefer a ready-to-use solution.
Can pet milk replacers be used for adult pets?
Yes, milk replacers can be used as a nutritional supplement for adult pets that are recovering from surgery, are pregnant or nursing, or are aging and require easily digestible protein. However, it should only be used as a supplement and not as a primary food source for adult animals.
What is driving the growth of the goat milk replacer segment?
Goat milk is naturally lower in lactose and has smaller fat globules compared to cow milk, making it significantly easier for neonatal pets to digest. It is also less likely to cause allergic reactions, which has made it a preferred choice for owners of pets with sensitive digestive systems.
Author
H
Hameer Thakur is a Manger Food and Beverages Research with over 8+ years of experience in the Food and Beverages Industry. He possesses extensive expertise in food and beverage market intelligence, consumer behavior analysis, demand forecasting, competitive benchmarking, product innovation assessment, pricing strategy, supply chain evaluation, regulatory compliance analysis, and market trend forecasting across packaged foods and beverage segments. His comprehensive research and data-driven insights enable organizations to make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, respond to evolving consumer preferences, and strengthen their competitive positioning in the global food and beverages market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
