Paraffin Wax Emulsions Market
Paraffin Wax Emulsions Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711644 | Published On : November 10, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Paraffin Wax Emulsions Market Size
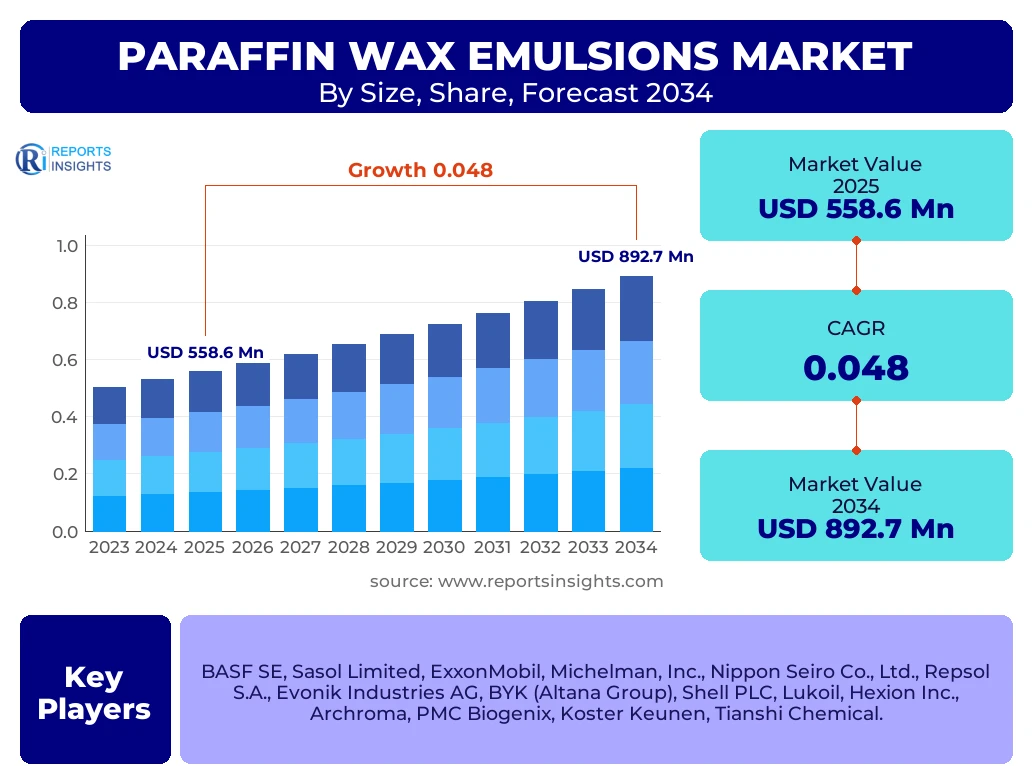
According to Reports Insights Consulting Pvt Ltd, The Paraffin Wax Emulsions Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.8% between 2025 and 2034. The market is estimated at USD 585.4 Million in 2026 and is projected to reach USD 892.7 Million by the end of the forecast period in 2034.
Key Paraffin Wax Emulsions Market Trends & Insights
The global demand for paraffin wax emulsions is undergoing a significant transformation, driven by the industrial shift toward water-based systems and the increasing stringency of environmental regulations regarding Volatile Organic Compounds (VOCs). Market participants are increasingly focusing on the development of high-stability emulsions that offer superior moisture resistance and lubricating properties across diverse industrial substrates. Regional dynamics indicate a massive pivot toward the Asia-Pacific region, where rapid urbanization and infrastructure development are catalyzing the consumption of wood-based panels and construction chemicals. Furthermore, the integration of bio-based additives within traditional paraffin formulations is emerging as a critical trend to meet the sustainability mandates of large-scale enterprise stakeholders in the European and North American markets.
- Asia-Pacific is the largest and fastest-growing region, fueled by massive wood processing and construction sectors in China and India.
- The Wood and Wood Products segment holds the largest market share due to the intensive use of emulsions as sizing agents in MDF and particleboard production.
- Technological advancements in emulsification techniques are allowing for smaller particle sizes, enhancing the penetration and performance of the wax in porous substrates.
- Rising demand for sustainable packaging is driving the adoption of paraffin wax emulsions in the paper and board coating industry.
Key Takeaways Paraffin Wax Emulsions Market Size & Forecast
The market trajectory for paraffin wax emulsions remains robust, underpinned by the essential nature of these materials in protecting and enhancing the durability of industrial goods. As the global economy focuses on circularity and reduced solvent usage, water-borne paraffin emulsions are positioned as a primary solution for moisture barrier applications. Analysts observe that the market is transitioning from a commodity-driven landscape to a value-added specialized sector where formulation expertise determines competitive advantage. The forecast period will likely see strategic consolidations as companies aim to secure raw material supply chains and expand their geographical footprints into emerging manufacturing hubs.
- The global market value is set to exceed USD 890 Million by 2034, maintaining a steady upward momentum.
- China remains the leading country globally in terms of both production capacity and domestic consumption.
- The shift toward non-ionic emulsions is gaining traction due to their high compatibility with various chemical additives in complex formulations.
- Construction and civil engineering applications are emerging as high-impact growth areas for moisture-proofing concrete and gypsum products.
Paraffin Wax Emulsions Market Drivers Analysis
The primary catalyst for the Paraffin Wax Emulsions market is the sustained growth in the wood-based panel industry. Paraffin wax emulsions are indispensable in the manufacturing of Medium Density Fiberboard (MDF) and Oriented Strand Board (OSB), where they act as critical sizing agents to prevent thickness swelling and enhance water resistance. Additionally, the global push for eco-friendly coating solutions has accelerated the replacement of solvent-based waxes with water-emulsified alternatives, particularly in the paints and inks industry. The expansion of the construction sector in emerging economies also provides a steady demand stream for concrete curing agents and gypsum board additives.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Growth in Wood-based Panel Manufacturing | +1.8% | Global (Strongest in APAC and Eastern Europe) | 2025 - 2034 |
| Regulatory Pressure on VOC Emissions | +1.2% | Europe and North America | 2025 - 2030 |
| Expansion of Construction & Infrastructure | +1.0% | India, China, Southeast Asia | 2026 - 2034 |
Paraffin Wax Emulsions Market Restraints Analysis
A significant restraint facing the market is the volatility in crude oil prices, which directly affects the cost of paraffin wax, a byproduct of petroleum refining. As refineries shift toward more modern processes like hydrocracking, the availability of traditional slack wax—the primary feedstock for emulsions—has become more constrained. Furthermore, the increasing competition from synthetic waxes and bio-based alternatives like soy or beeswax emulsions poses a threat to the market share of traditional paraffin-based products, especially in high-end cosmetic and food-contact applications.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Petroleum Feedstock Prices | -0.9% | Global | Ongoing |
| Competition from Bio-based Wax Substitutes | -0.5% | Europe and North America | 2027 - 2034 |
Paraffin Wax Emulsions Market Opportunities Analysis
Opportunities abound in the development of specialized emulsions for the paper and packaging industry, particularly for compostable and recyclable food packaging solutions. As the world moves away from single-use plastics, wax-coated paper products offer a viable moisture-resistant alternative. There is also significant potential in the agricultural sector, where paraffin emulsions are used as seed coatings and anti-transpirants to improve crop yields in arid regions. Emerging nanotechnology applications, where nano-emulsions provide superior surface coverage with less material, represent a high-value growth frontier for innovative chemical manufacturers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Sustainable Packaging Coatings | +1.5% | North America and Western Europe | 2026 - 2034 |
| Agricultural Seed Coating Applications | +0.7% | Latin America and Africa | 2028 - 2034 |
Paraffin Wax Emulsions Market Challenges Impact Analysis
One of the primary challenges is maintaining the shelf-life stability of emulsions under varying climatic conditions during transportation and storage. Phase separation and microbial degradation can significantly impact product quality, necessitating the use of expensive stabilizers and biocides. Additionally, the complex regulatory landscape regarding food-contact materials requires rigorous testing and certification, which can be a barrier for smaller manufacturers looking to enter the packaging or pharmaceutical segments. Balancing performance with cost-efficiency remains a persistent challenge in price-sensitive markets like the textile industry.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Product Stability and Shelf-life Issues | -0.4% | MEA and Tropical Regions | Continuous |
| Stringent Food-Contact Regulations | -0.6% | Global | 2025 - 2034 |
Paraffin Wax Emulsions Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global paraffin wax emulsions industry, covering the historical period of 2020 to 2024 and providing a detailed forecast through 2034. The research identifies critical growth levers across various end-use industries including wood, construction, textiles, and paper. It provides a granular breakdown of the market by ionic nature and solid content, offering strategic insights into competitive positioning and regional market maturity. This report is designed to assist stakeholders in identifying high-growth segments and navigating the technical complexities of the evolving wax emulsion landscape.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 558.6 Million |
| Market Forecast in 2034 | USD 892.7 Million |
| Growth Rate | 4.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Sasol Limited, ExxonMobil, Michelman, Inc., Nippon Seiro Co., Ltd., Repsol S.A., Evonik Industries AG, BYK (Altana Group), Shell PLC, Lukoil, Hexion Inc., Archroma, PMC Biogenix, Koster Keunen, Tianshi Chemical. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the paraffin wax emulsions market reflects the diverse functional requirements of different industrial sectors. By analyzing the ionic nature of the emulsions—Anionic, Cationic, and Non-ionic—we gain insight into their compatibility with various substrates and chemical environments. Anionic emulsions remain the workhorse of the industry due to their excellent wetting properties and cost-effectiveness in wood and paper applications. Cationic emulsions, though smaller in market share, are vital for specific applications where substrate bonding is critical, such as in certain textile treatments and road construction. Non-ionic emulsions are witnessing the fastest growth because of their exceptional chemical stability and versatility in complex formulations like paints and cosmetics.
- By Type:
- Anionic Paraffin Wax Emulsions
- Cationic Paraffin Wax Emulsions
- Non-ionic Paraffin Wax Emulsions
- By Application:
- Wood & Wood Products (MDF, OSB, Particleboard)
- Construction (Gypsum, Concrete curing)
- Paper & Packaging (Coating, Sizing)
- Textiles (Softening, Water repellency)
- Coatings, Inks & Polishes
- Others (Cosmetics, Agrochemicals, Leather)
- By Solid Content:
- Low Solid Content (Below 30%)
- Medium Solid Content (30%-50%)
- High Solid Content (Above 50%)
Regional Highlights
- Asia-Pacific: This region is the global powerhouse for the paraffin wax emulsions market, accounting for over 40% of the total market share. The dominance is attributed to the presence of massive wood-processing industries in China, Vietnam, and Malaysia, alongside a booming construction sector in India.
- North America: The market is characterized by a high demand for specialized wax emulsions in the packaging and coatings sectors. The focus on sustainable materials and technological innovation drives the steady growth of the regional market.
- Europe: Europe leads in the adoption of stringent environmental regulations, pushing the market toward low-VOC and bio-compatible emulsions. Germany and the UK are key markets for automotive polishes and high-end wood coatings.
- Latin America: Growth is primarily driven by the agricultural sector in Brazil and Argentina, where wax emulsions are used for crop protection and seed treatment.
- Middle East & Africa: The market is emerging, with increasing utilization in construction activities and the development of local textile manufacturing hubs in countries like Turkey and Egypt.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Paraffin Wax Emulsions Market.- BASF SE
- Sasol Limited
- ExxonMobil Corporation
- Michelman, Inc.
- Nippon Seiro Co., Ltd.
- Repsol S.A.
- Evonik Industries AG
- BYK-Chemie GmbH (Altana)
- Shell PLC
- Lukoil
- Hexion Inc.
- Archroma
- PMC Biogenix
- Koster Keunen
- Tianshi Chemical
- Chuwax
- Marchem
- Euroceras
- Sinopec
- Clariant AG
Frequently Asked Questions
What is the projected growth rate of the Paraffin Wax Emulsions market?
The global Paraffin Wax Emulsions market is expected to grow at a Compound Annual Growth Rate (CAGR) of 4.8% from 2025 to 2034, reaching an estimated value of USD 892.7 Million.
Which industry is the primary consumer of paraffin wax emulsions?
The wood and wood products industry is the largest consumer, utilizing paraffin wax emulsions as sizing agents in the production of panels like MDF and OSB to provide moisture resistance.
Which region holds the largest share of the Paraffin Wax Emulsions market?
The Asia-Pacific region currently holds the largest market share and is also the fastest-growing region due to rapid industrialization and construction activities in China and India.
What are the key technical types of wax emulsions available?
Paraffin wax emulsions are primarily categorized based on their ionic nature into Anionic, Cationic, and Non-ionic types, each serving different substrate compatibility needs.
How is the move toward sustainability affecting the market?
Sustainability is driving the development of water-based, low-VOC emulsions and the inclusion of bio-based or natural waxes to replace or supplement traditional petroleum-derived paraffin.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
