Paper Dyes Market
Paper Dyes Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711592 | Published On : November 07, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Paper Dyes Market Size
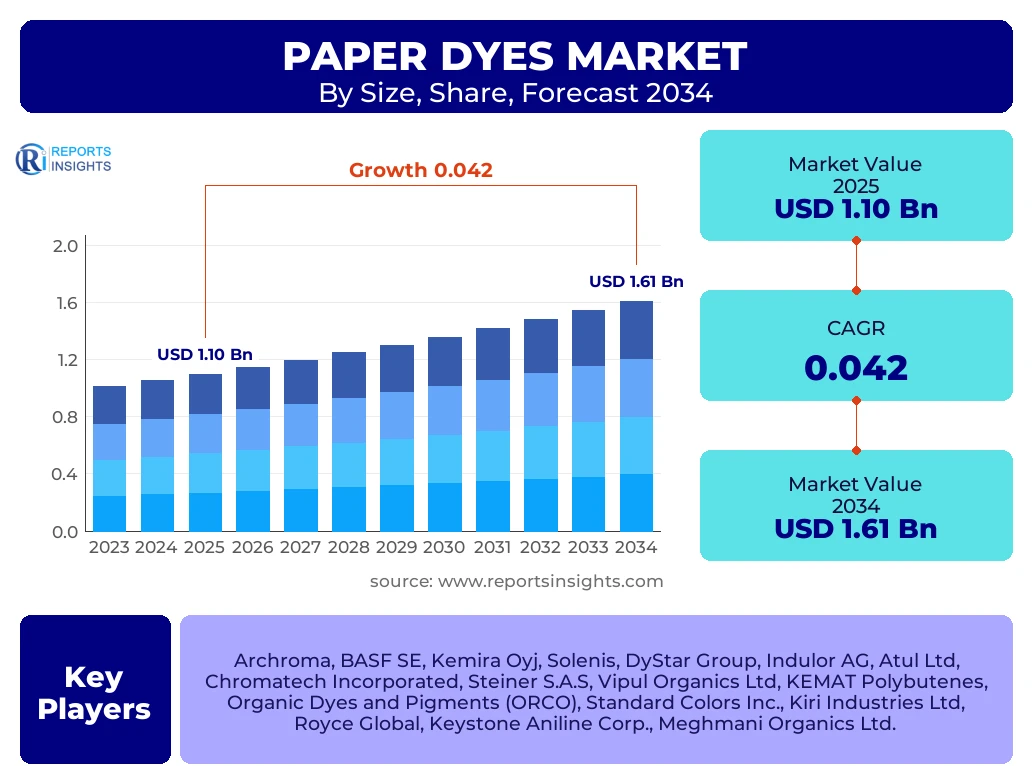
According to Reports Insights Consulting Pvt Ltd, The Paper Dyes Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.2% between 2025 and 2034. The market is estimated at USD 1.15 Billion in 2026 and is projected to reach USD 1.61 Billion by the end of the forecast period in 2034.
The global valuation of the paper dyes industry is undergoing a significant transformation, driven primarily by the transition from traditional print media toward specialized packaging and tissue applications. As consumer behavior shifts toward sustainable materials, the demand for high-quality, biodegradable, and non-toxic colorants has intensified. This market evolution is characterized by a strategic focus on cationic direct dyes and sulfur dyes that offer superior affinity for cellulose fibers, ensuring minimal color bleed and high retention rates during the manufacturing process. The expansion of the e-commerce sector has specifically bolstered the demand for colored corrugated packaging, creating a consistent revenue stream for dye manufacturers specializing in high-performance brown and aesthetic primary hues.
Furthermore, technical advancements in liquid dye formulations are streamlining the production workflow for paper mills by reducing dust hazards and improving dosing accuracy. The integration of closed-loop color management systems and automated liquid dispensing technology has allowed manufacturers to achieve higher color consistency while reducing chemical waste. From a geographical perspective, the migration of paper production hubs toward emerging economies in Asia-Pacific has repositioned the center of market gravity. These regions are prioritizing cost-effective yet visually appealing paper products for both domestic consumption and export, thereby necessitating a robust supply chain for synthetic and organic paper colorants.
Key Paper Dyes Market Trends & Insights
The Paper Dyes market is currently navigating a period of intense regulatory scrutiny and technological disruption. Market intelligence indicates a sharp rise in the adoption of bio-based dyes as brands seek to align with global circular economy goals. In particular, the demand for tissue and decorative paper in the European and North American markets is driving innovation in "food-contact safe" dyes. Analyzing competitive benchmarking reveals that leading players are increasingly investing in R&D to develop dyes with enhanced bleachability, which is a critical factor in the recycling efficiency of colored paper products. The shift toward sustainable packaging has made the "unbleached look" popular, yet even these products often require subtle tinting to maintain brand consistency across different batches of recycled pulp.
- Largest Region: Asia-Pacific remains the dominant powerhouse, accounting for over 45% of the total market share due to the massive concentration of paper mills in China, India, and Southeast Asia.
- Fastest Growing Region: Southeast Asia is projected to witness the highest growth rate, fueled by industrial relocation and the rapid expansion of the regional packaging industry.
- Largest Segment by Share: The Packaging and Board segment holds the majority share, driven by the global ban on single-use plastics and the subsequent rise in paper-based alternatives.
- Form Preference: Liquid dyes are rapidly outpacing powder forms due to their ease of handling, lack of airborne particulates, and superior solubility in continuous dyeing processes.
Key Takeaways Paper Dyes Market Size & Forecast
Strategic analysis of the Paper Dyes market trajectory suggests that the forecast period will be defined by a convergence of environmental compliance and functional performance. As digital printing continues to penetrate the paper industry, dye formulations are being optimized to provide better substrates for inkjet and laser technologies. Stakeholders are focusing on "cationic" dye variants which offer excellent exhaustion rates, reducing the environmental load on mill effluent treatment plants. The market forecast also highlights a pivot toward specialized colorants for premium tissue and hygiene products, where skin sensitivity and non-migration of color are paramount consumer requirements.
- Packaging Dominance: The transition to paper-based e-commerce packaging is the single most significant volume driver for the global market through 2034.
- Regulatory Influence: REACH and FDA compliance for paper dyes used in food wrapping and hygiene products are creating high entry barriers for low-quality dye manufacturers.
- Technological Shift: The industry is moving toward automated "on-machine" tinting systems that require high-purity liquid dyes to prevent nozzle clogging and shade variations.
- Leading Countries: China, the United States, and Germany remain the primary hubs for both production and consumption of high-grade paper colorants.
Paper Dyes Market Drivers Analysis
The primary catalysts for the Paper Dyes market involve the structural shift in the global packaging ecosystem and the rising consumer preference for aesthetically pleasing consumer goods. As the world moves away from plastic, paper is being re-engineered for durability and visual appeal, necessitating advanced dyeing techniques. Additionally, the growth of the tissue and hygiene sector, particularly in emerging economies, provides a stable foundation for market expansion. The increasing utilization of recycled paper also drives the market, as secondary fibers often require significant tinting to mask impurities and achieve a standardized final appearance.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Eco-friendly Packaging Demand | +1.8% | Global / North America & Europe | 2025–2034 |
| Growth in Tissue and Hygiene Products | +1.2% | APAC & Latin America | 2025–2030 |
| Advancements in Liquid Dye Dosing Technology | +0.7% | Europe & North America | 2026–2032 |
| Rise in Recycled Paper Processing | +0.5% | Global | 2025–2034 |
Paper Dyes Market Restraints Analysis
Despite growth opportunities, the market faces headwinds from volatile raw material costs, particularly in the petrochemical-derived intermediates used for synthetic dyes. Environmental regulations regarding wastewater discharge from dyeing operations are becoming more stringent, requiring paper mills to invest heavily in advanced filtration and treatment systems. Furthermore, the persistent decline in traditional newsprint and writing paper reduces the volume demand for certain types of basic and acid dyes that were once the industry standard.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Effluent Treatment Regulations | -0.9% | Europe & China | 2025–2034 |
| Fluctuation in Raw Material Prices | -0.6% | Global | Ongoing |
| Decline in Traditional Print Media | -0.5% | Global / North America | 2025–2034 |
Paper Dyes Market Opportunities Analysis
The ongoing research into organic and vegetable-based dyes presents a massive opportunity for differentiation in a commoditized market. Companies that can pioneer vibrant, high-fastness dyes from renewable sources will likely capture premium segments of the decorative and luxury packaging market. Additionally, the development of dyes specifically optimized for high-speed digital inkjet overprinting on paper substrates is a burgeoning niche. The expansion of the organized retail sector in Africa and Southeast Asia also offers untapped potential for basic and direct dye applications in lower-cost packaging formats.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based Colorants | +1.4% | Europe & North America | 2027–2034 |
| Inkjet-Compatible Paper Coatings | +0.9% | Global / Japan | 2026–2031 |
| Customization in Luxury Packaging | +0.6% | Global / MEA | 2025–2034 |
Paper Dyes Market Challenges Impact Analysis
Key challenges include maintaining color consistency when using fluctuating qualities of recycled pulp, which often contains residual inks and contaminants. The high energy intensity of dye manufacturing and the logistics of transporting large volumes of liquid dyes also pose operational hurdles. Moreover, the industry must constantly adapt to changing consumer safety standards, such as the elimination of specific aromatic amines and heavy metals from dye formulations, which requires frequent and costly product re-engineering.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Achieving Uniformity in Recycled Pulp | -0.7% | Global | Ongoing |
| Compliance with New Safety Standards | -0.4% | European Union / USA | 2025–2030 |
| High Operational Costs for Small Mills | -0.3% | APAC & MEA | 2025–2028 |
Paper Dyes Market - Updated Report Scope
This comprehensive market report provides a deep-dive analysis into the global paper dyes ecosystem, covering chemical compositions, delivery forms, and specific end-use applications across six major geographical regions. It evaluates the impact of the circular economy on dye selection and provides detailed forecasts based on the interplay of industrial growth and regulatory constraints. The report includes a rigorous assessment of the competitive landscape, highlighting strategic maneuvers such as mergers, product launches, and technological collaborations among the top 20 industry leaders.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.10 Billion |
| Market Forecast in 2034 | USD 1.61 Billion |
| Growth Rate | 4.2% CAGR |
| Number of Pages | 245 Pages |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Archroma, BASF SE, Kemira Oyj, Solenis, DyStar Group, Indulor AG, Atul Ltd, Chromatech Incorporated, Steiner S.A.S, Vipul Organics Ltd, KEMAT Polybutenes, Organic Dyes and Pigments (ORCO), Standard Colors Inc., Kiri Industries Ltd, Royce Global, Keystone Aniline Corp., Meghmani Organics Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Paper Dyes market is segmented primarily by chemical type and physical form to reflect the diverse operational requirements of modern paper mills. Direct dyes dominate the landscape due to their high affinity for cellulose and ease of application in both sizing press and wet-end processes. The transition from powder to liquid forms is a critical sub-segment trend, driven by the automation of color kitchens in large-scale industrial mills. Application-based segmentation shows a definitive shift toward the Packaging and Board sector, which now utilizes a significant portion of sulfur and direct brown dyes for industrial applications.
- By Type:
- Direct Dyes (Cationic and Anionic)
- Acid Dyes (High solubility and brightness)
- Basic Dyes (Primarily for unbleached pulps and mechanical pulps)
- Sulfur Dyes (High volume, cost-effective for deep shades)
- By Form:
- Liquid (Preferred for continuous dyeing and automation)
- Powder/Granules (Traditional use, ease of storage in small-scale operations)
- By Application:
- Packaging & Board (Corrugated boxes, folding cartons)
- Writing & Printing (Office paper, stationary)
- Coated Paper (Magazines, high-end advertising)
- Tissue & Decorative (Napkins, facial tissues, gift wraps)
Regional Highlights
- Asia-Pacific (APAC): The largest market globally, APAC is characterized by massive production capacities in China and India. The region benefits from lower manufacturing costs and a burgeoning domestic packaging market. It is also the fastest-growing region due to rapid industrialization in Southeast Asia.
- North America: A mature market focusing on high-specialty dyes for the tissue and hygiene sectors. There is a strong emphasis on regulatory compliance and the development of sustainable, food-contact-approved colorants.
- Europe: The leader in sustainable innovation. European manufacturers are at the forefront of developing bio-based dyes and high-efficiency effluent treatment solutions. The market is driven by strict environmental mandates and premium packaging requirements.
- Latin America: Growth is centered in Brazil and Mexico, primarily driven by the pulp and paper export industry and the increasing demand for consumer goods packaging.
- Middle East and Africa (MEA): Emerging as a key region for basic and direct dyes, as domestic paper production increases to meet the needs of a growing retail and industrial sector.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Paper Dyes Market. These organizations are selected based on their market share, product portfolio breadth, innovation capabilities, and geographical reach.
- Archroma
- BASF SE
- Kemira Oyj
- Solenis
- DyStar Group
- Indulor AG
- Atul Ltd
- Chromatech Incorporated
- Steiner S.A.S
- Vipul Organics Ltd
- KEMAT Polybutenes
- Organic Dyes and Pigments (ORCO)
- Standard Colors Inc.
- Kiri Industries Ltd
- Royce Global
- Keystone Aniline Corp.
- Meghmani Organics Ltd
Frequently Asked Questions
What is the primary driver for the Paper Dyes market growth through 2034?
The primary driver is the global shift from plastic packaging to sustainable paper-based alternatives, particularly in the e-commerce and food service sectors, which requires high volumes of specialized colorants.
Why are liquid dyes becoming more popular than powder dyes?
Liquid dyes offer several industrial advantages, including dust-free handling, easier automated dosing, higher solubility in cold water, and better color consistency in continuous paper manufacturing processes.
Which region holds the largest share of the Paper Dyes market?
Asia-Pacific currently holds the largest market share, driven by the high concentration of paper manufacturing hubs in China and India and increasing demand for industrial packaging.
How do environmental regulations impact the paper dye industry?
Regulations such as REACH and FDA standards force manufacturers to eliminate toxic intermediates and heavy metals, while also mandating more efficient effluent treatment to remove color from wastewater.
What role do cationic direct dyes play in the market?
Cationic direct dyes are highly valued for their exceptional affinity for wood fibers, leading to high retention rates, clearer backwater, and better bleed fastness, which is essential for high-quality tissue and packaging.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
