Orthopedic Spine Navigation Systems Market
Orthopedic Spine Navigation Systems Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711572 | Published On : November 06, 2026 |
Format : 


 | Author : Erika Grotto
Orthopedic Spine Navigation Systems Market Size
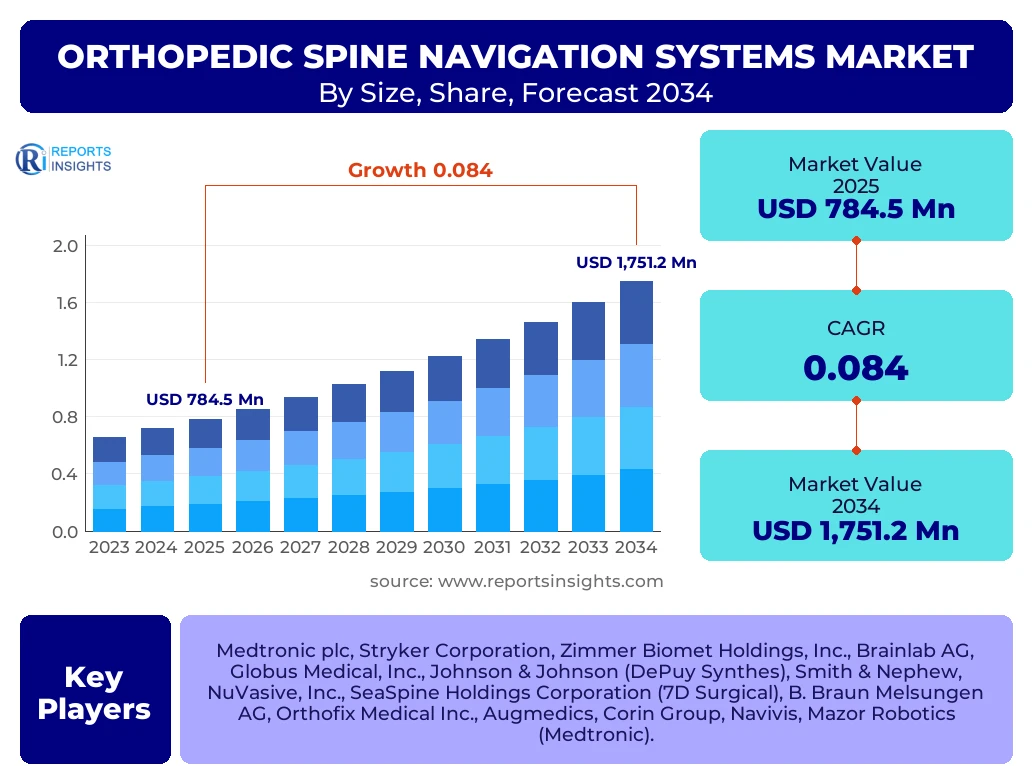
According to Reports Insights Consulting Pvt Ltd, The Orthopedic Spine Navigation Systems Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.4% between 2025 and 2034. The market is estimated at USD 850.4 Million in 2026 and is projected to reach USD 1,751.2 Million by the end of the forecast period in 2034.
Key Orthopedic Spine Navigation Systems Market Trends & Insights
The global orthopedic spine navigation systems market is undergoing a significant transformation driven by the transition from traditional open-field surgeries to minimally invasive spine surgery (MISS). Industry stakeholders are increasingly focusing on the integration of augmented reality (AR) and artificial intelligence (AI) to enhance surgical precision and reduce intraoperative radiation exposure for both patients and surgical teams. Advanced navigation platforms now offer real-time 3D visualization, which allows surgeons to map spinal anatomy with sub-millimeter accuracy, significantly reducing the risk of pedicle screw malpositioning and subsequent revision surgeries.
Current market dynamics suggest a shift toward multidisciplinary surgical platforms that combine navigation with robotic assistance. This convergence is expected to redefine the competitive landscape as hospitals prioritize integrated surgical suites over standalone navigation units. Furthermore, the adoption of intraoperative imaging technologies, such as mobile O-arm and C-arm CT scanners, is providing a seamless workflow that facilitates immediate verification of implant placement, thereby improving clinical outcomes and reducing the length of hospital stays in high-volume orthopedic centers.
- North America remains the largest regional market due to high healthcare expenditure and early adoption of robotic surgical systems.
- Asia Pacific is identified as the fastest-growing region, fueled by expanding healthcare infrastructure in China and India and a rising geriatric population.
- The Optical Navigation Systems segment holds the largest market share owing to its superior accuracy and reliability in complex spinal reconstructions.
- Hospitals represent the primary end-user segment, although Ambulatory Surgical Centers (ASCs) are gaining share due to the shift toward outpatient spinal procedures.
Key Takeaways Orthopedic Spine Navigation Systems Market Size & Forecast
The forecast period is characterized by a robust expansion in the adoption of computer-assisted surgery (CAS). The market is poised for steady growth as the burden of degenerative disc diseases and spinal stenosis increases globally. Financial modeling suggests that while initial capital investment remains high, the long-term reduction in revision rates and procedural complications provides a compelling return on investment for large-scale healthcare providers. Strategic partnerships between imaging hardware manufacturers and software developers are expected to accelerate the deployment of next-generation navigation platforms across emerging economies.
- The United States leads the global market in terms of value, supported by favorable reimbursement policies for navigated spinal fusions.
- The integration of 5G technology and remote surgical planning is emerging as a critical factor in expanding the reach of specialized spinal care to rural areas.
- Degenerative spine disorders account for the highest volume of navigated procedures, particularly in aging populations across Europe and Japan.
- The market is seeing a move toward subscription-based software models, allowing smaller facilities to access advanced navigation technology without massive upfront costs.
Orthopedic Spine Navigation Systems Market Drivers Analysis
The primary driver for the orthopedic spine navigation systems market is the escalating demand for minimally invasive surgical techniques. As patients and surgeons seek procedures that involve smaller incisions, less blood loss, and faster recovery times, the need for precise navigation becomes paramount. Traditional fluoroscopy often falls short in providing the depth perception required for complex MIS, making automated navigation systems an essential tool for modern neurosurgeons and orthopedic spine specialists.
Furthermore, the rising incidence of spinal disorders, including scoliosis, spondylolisthesis, and herniated discs, is creating a high-volume environment for surgical intervention. The global aging population is particularly susceptible to these conditions, necessitating surgical solutions that are both safe and efficient. The technological evolution of electromagnetic and optical tracking systems has also improved the ease of use, reducing the steep learning curve previously associated with surgical navigation, thus driving wider adoption among general orthopedic surgeons.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Minimally Invasive Surgery (MIS) | +2.8% | Global / North America | 2025 - 2034 |
| Aging Global Population and Degenerative Disease Prevalence | +2.1% | Japan, Germany, USA | 2025 - 2034 |
| Integration of AI and Machine Learning in Surgical Planning | +1.9% | Global / Europe | 2027 - 2034 |
| Favorable Reimbursement Landscape for CAS | +1.6% | USA, France, UK | 2025 - 2030 |
Orthopedic Spine Navigation Systems Market Restraints Analysis
Despite the technological advantages, the high cost of acquisition and maintenance remains a significant barrier to market entry for many healthcare facilities, particularly in developing nations. A typical navigation system requires a substantial capital layout, which includes the cost of the hardware, specialized surgical instruments, and recurring software licensing fees. For many mid-sized hospitals, the high volume of surgeries required to break even on such an investment is difficult to achieve, leading to a reliance on traditional surgical methods.
Another critical restraint is the technical complexity and the requirement for specialized training. While modern systems are more intuitive, they still require a significant investment in time for surgeons and operating room staff to become proficient. Intraoperative technical glitches or registration errors can also lead to delays in the surgical workflow, which can be a deterrent for busy surgical practices. Furthermore, the reliance on high-quality intraoperative imaging can sometimes increase the total procedural time if the workflow is not perfectly optimized.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Capital Expenditure and Maintenance Costs | -1.5% | India, Brazil, Southeast Asia | 2025 - 2034 |
| Steep Learning Curve and Training Requirements | -0.8% | Global | 2025 - 2028 |
Orthopedic Spine Navigation Systems Market Opportunities Analysis
The emergence of Ambulatory Surgical Centers (ASCs) as a primary setting for spinal procedures presents a massive opportunity for manufacturers to develop portable and cost-effective navigation solutions. As healthcare payers push for more procedures to be performed in outpatient settings to reduce costs, there is a growing need for "lightweight" navigation systems that do not require the heavy infrastructure of a traditional hospital operating room. Developing modular systems that can be easily integrated into existing ASC workflows will be a key growth area.
Additionally, the integration of Augmented Reality (AR) headsets and Virtual Reality (VR) for pre-operative planning and intraoperative execution represents a frontier for innovation. AR allows surgeons to maintain their line of sight on the patient while seeing navigated data overlaid on the surgical field, potentially improving ergonomics and focus. There is also a burgeoning market for navigation systems in emerging economies where healthcare modernization is a national priority, offering untapped potential for companies that can offer tiered pricing or leasing models.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Proliferation of Ambulatory Surgical Centers (ASCs) | +2.4% | USA, Canada | 2026 - 2034 |
| Development of AR-based Navigation Systems | +1.8% | Germany, Israel, USA | 2027 - 2034 |
| Market Expansion in Emerging Economies | +1.5% | China, India, Mexico | 2026 - 2034 |
Orthopedic Spine Navigation Systems Market Challenges Impact Analysis
A major challenge facing the industry is the interoperability between different hardware and software ecosystems. Many hospitals utilize imaging equipment from one vendor and navigation systems from another; ensuring these systems communicate seamlessly without data loss or latency is a constant technical hurdle. Furthermore, the rapid pace of technological advancement means that systems can become obsolete relatively quickly, making it difficult for hospitals to justify long-term investments without guaranteed upgrade paths.
Data security and the protection of patient information also pose a significant challenge as surgical suites become more "connected." With the integration of cloud-based surgical planning and AI-driven diagnostics, the risk of cyberattacks on medical devices has increased. Manufacturers must navigate stringent regulatory landscapes, such as the GDPR in Europe and HIPAA in the US, while ensuring that their systems remain functional and user-friendly in high-pressure surgical environments.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Interoperability and Data Integration Issues | -1.2% | Global | 2025 - 2030 |
| Cybersecurity and Patient Data Privacy | -0.7% | Europe, North America | 2025 - 2034 |
Orthopedic Spine Navigation Systems Market - Updated Report Scope
This report provides a comprehensive analysis of the global orthopedic spine navigation systems market, covering technological advancements, competitive dynamics, and regional growth patterns. The scope includes an in-depth evaluation of the various modalities such as optical, electromagnetic, and hybrid navigation, alongside an assessment of their applications in cervical, thoracolumbar, and sacral spine procedures. The research also explores the impact of the shift toward robotic-assisted surgeries and the growing role of AI in perioperative decision-making.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 784.5 Million |
| Market Forecast in 2034 | USD 1,751.2 Million |
| Growth Rate | 8.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Medtronic plc, Stryker Corporation, Zimmer Biomet Holdings, Inc., Brainlab AG, Globus Medical, Inc., Johnson & Johnson (DePuy Synthes), Smith & Nephew, NuVasive, Inc., SeaSpine Holdings Corporation (7D Surgical), B. Braun Melsungen AG, Orthofix Medical Inc., Augmedics, Corin Group, Navivis, Mazor Robotics (Medtronic). |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The orthopedic spine navigation systems market is segmented by technology, application, and end-user. Optical navigation currently dominates the market due to its high precision and line-of-sight tracking capabilities, which are essential for complex posterior spinal fusions. Electromagnetic navigation is also seeing growth, particularly in procedures where line-of-sight may be obstructed, as it uses magnetic fields to track instruments. The application segment is dominated by degenerative disc diseases, while the trauma segment is expected to see steady growth due to the rising incidence of road accidents and sports injuries requiring emergency spinal stabilization.
- By Technology:
- Optical Navigation Systems: High-precision cameras and infrared markers.
- Electromagnetic (EM) Navigation: Useful in crowded operating rooms without line-of-sight requirements.
- Hybrid Systems: Combining multiple modalities for enhanced surgical flexibility.
- By Application:
- Spinal Fusion: The largest application segment by volume.
- Scoliosis and Deformity Correction: High-growth segment requiring complex 3D planning.
- Spinal Trauma: Real-time navigation for urgent stabilization.
- Oncology: Precise resection of spinal tumors.
- By End-User:
- Hospitals: Primary centers for complex and multi-level spinal surgeries.
- Ambulatory Surgical Centers: Growing preference for single-level decompressions and fusions.
Regional Highlights
- North America: The largest market share holder, characterized by a highly developed healthcare system and the presence of major market players like Medtronic and Stryker. The high adoption rate of robotic-assisted spine surgery further bolsters this region.
- Europe: A mature market with strong growth in Germany, France, and the UK. European growth is driven by public healthcare initiatives and a strong focus on clinical research in surgical robotics.
- Asia Pacific: The fastest-growing region with a high CAGR. Factors include increasing healthcare investments in China, India, and South Korea, along with a massive patient pool and a rising middle class seeking advanced medical care.
- Latin America & MEA: Steady growth observed in Brazil and the GCC countries, where infrastructure upgrades and medical tourism are driving the demand for advanced surgical technologies.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Orthopedic Spine Navigation Systems Market.- Medtronic plc
- Stryker Corporation
- Zimmer Biomet Holdings, Inc.
- Brainlab AG
- Globus Medical, Inc.
- DePuy Synthes (Johnson & Johnson)
- Smith & Nephew
- SeaSpine Holdings Corporation (7D Surgical)
- B. Braun Melsungen AG
- NuVasive, Inc.
- Orthofix Medical Inc.
- Augmedics
- Corin Group
- Navivis
- Bluebelt Technologies (Smith & Nephew)
- Fiagon GmbH
- Curexo
- Xcision Medical Systems
Frequently Asked Questions
What are the main benefits of using navigation systems in spine surgery?
Navigation systems provide real-time 3D visualization, allowing for highly accurate placement of implants and pedicle screws. This reduces the risk of nerve damage, lowers the rate of revision surgeries, and decreases the amount of intraoperative radiation exposure for both the patient and the surgical staff compared to conventional fluoroscopy.
How does optical navigation differ from electromagnetic navigation?
Optical navigation uses infrared cameras to track reflective markers on surgical instruments, requiring a clear "line of sight" between the camera and the tools. Electromagnetic (EM) navigation uses a magnetic field to track instruments with sensors, which does not require a line of sight but can be sensitive to interference from metal objects in the operating room.
What is driving the growth of the market in the Asia Pacific region?
Growth in Asia Pacific is driven by rapid healthcare infrastructure development, an increasing elderly population prone to spinal issues, and rising awareness of minimally invasive procedures. Countries like China and India are seeing significant investments in medical technology, making advanced navigation systems more accessible.
Is robotic integration the future of spinal navigation?
Yes, the industry is moving toward "Robotic-Navigation" systems where the robot provides a stable guided arm and the navigation system provides the visual roadmap. This combination offers the highest level of consistency and precision, which is becoming the standard for complex spinal reconstructions in top-tier hospitals.
What are the cost implications for small hospitals adopting this technology?
For smaller hospitals, the high initial cost (often exceeding USD 500,000) is a hurdle. However, manufacturers are increasingly offering flexible financing, leasing models, and per-procedure fees to help smaller facilities adopt the technology without massive upfront capital expenditure.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
